
Kontron (XTRA:KTN) Wins Rail Contracts, Is The Valuation Discount Too Wide?
Kontron (XTRA:KTN) has just secured several contracts for the Orient/East-Med Corridor, partnering with Hitachi Rail Romania. The agreement runs for 48 months and deepens its role in railway communications across Romania and Central and Eastern Europe.
These contracts arrive at a time when Kontron’s share price has softened, with the year to date share price return down 8.43% and the 1 year total shareholder return down 16.94%, even though the 3 year total shareholder return is up 21.88%. This suggests that recent momentum has faded after earlier gains.
Scan contracts-driven stories like Kontron’s rail win across Europe with a curated set of 619 high quality undiscovered gems that are still flying under most investors’ radar.
Kontron now combines fresh rail contract wins with a share price that has pulled back. Does that mix leave more upside than downside as you weigh the current valuation next?
Price-to-Earnings of 15.2x: Is it justified?
On a P/E of 15.2x, Kontron is priced below both its peer group on 27.1x and the wider European IT sector on 18.1x. For anyone tracking contracts like the new rail deals against the current share price of €21.08, that gap is hard to ignore.
The P/E ratio compares what investors pay today for each euro of earnings. For a software and IoT solutions provider like Kontron, this measure often reflects how the market rates its ability to turn revenue into profit over time. A lower multiple in this context can indicate that expectations for future profitability are more muted than for similar businesses.
Here the story is mixed. Kontron is flagged as trading at good value compared both to peers and the broader industry, and its current P/E of 15.2x sits below an estimated fair P/E of 22.3x that our fair ratio work suggests the market could move towards. At the same time, recent earnings fell sharply, profit margins declined from 8.2% to 5.4%, and there were large one off items in the last twelve months, which can all weigh on how much investors are prepared to pay for each euro of profit.
Compared against the European IT industry, Kontron’s discount is clear. The stock trades on 15.2x earnings versus 18.1x for the sector and 27.1x for direct peers, which indicates the market is attaching a lower valuation to its earnings stream than it does for comparable companies.
Explore the SWS fair ratio for Kontron.
Result: Preferred multiple of Price-to-Earnings of 15.2x (UNDERVALUED)
Still, Kontron’s shrinking profit margins and the recent share price slide over 1 year could pressure sentiment if contract wins do not translate cleanly into earnings.
Find out about the key risks to this Kontron narrative.
Another View on Kontron using our DCF model
The P/E work presents Kontron as inexpensive. A different tool, the SWS DCF model, goes further and characterizes the stock as undervalued, with the current €21.08 price sitting below an estimated future cash flow value of €39.70. That gap raises a sharper question: is the discount mispricing or deserved?
Look into how the SWS DCF model arrives at its fair value.
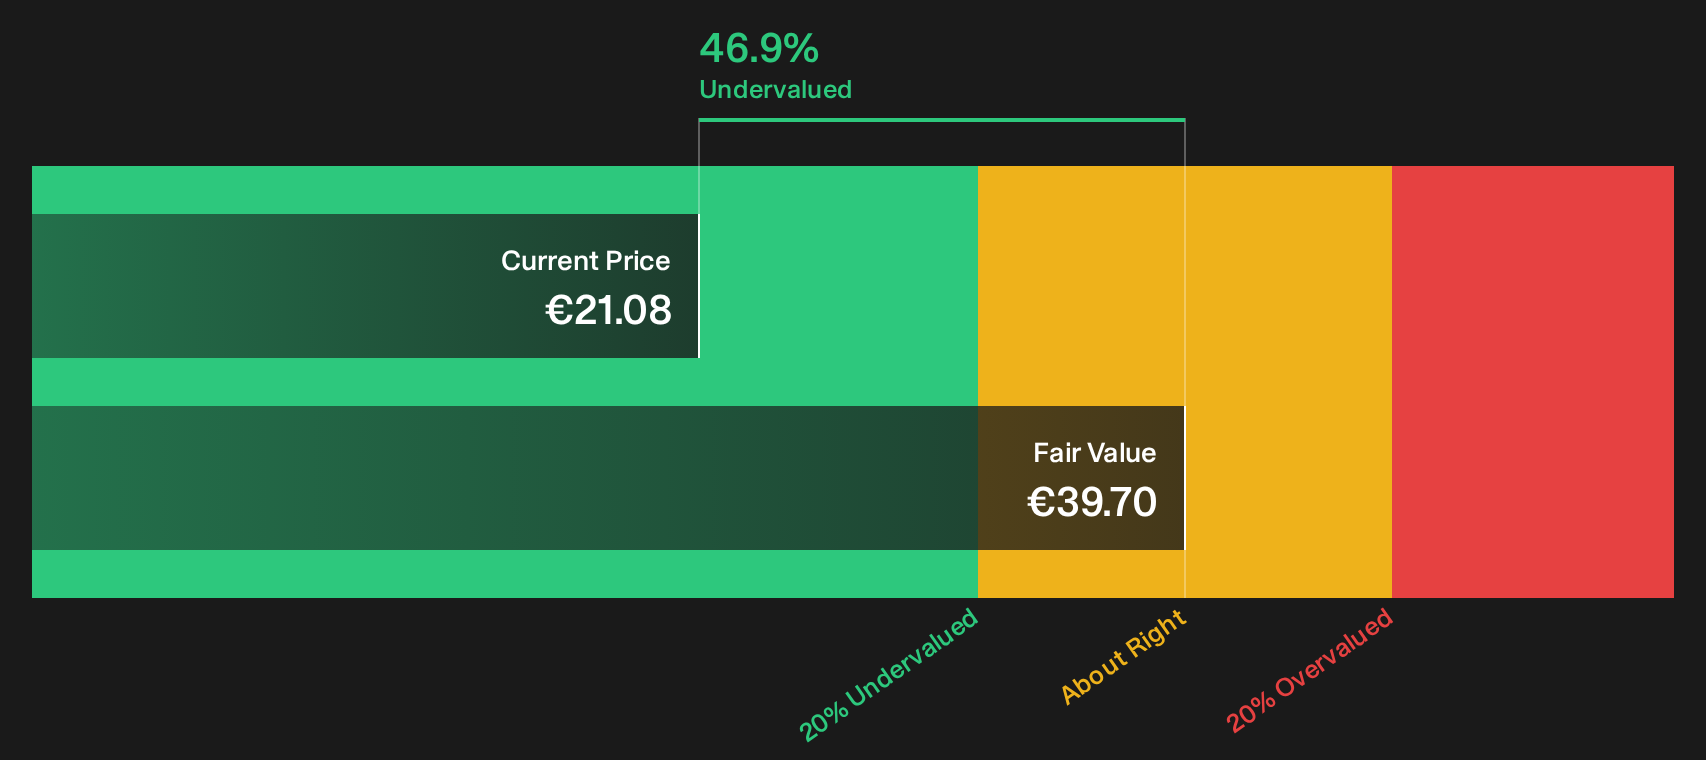
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kontron for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
That mix of contract momentum, valuation signals and shifting sentiment around Kontron will read differently to every investor. Move quickly, review the data, test your own thesis and weigh the 4 key rewards and 2 important warning signs.
Looking for more ideas beyond Kontron?
Kontron’s story is just one angle. Broaden your watchlist now, because sidelining fresh ideas can quietly cost you compounding opportunities over the next few years.
- Target potential mispricings by scanning a curated 183 high quality undervalued stocks that filters for quality businesses trading at what may be compressed valuations.
- Strengthen your income stream by reviewing a focused 161 dividend fortresses built around companies combining higher yields with resilient payout histories.
- Protect your downside by assessing a handpicked 99 resilient stocks with low risk scores that highlights businesses with steadier profiles and fewer red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com