
Alstom (ENXTPA:ALO) Shares Just Moved, So What Is Behind The Attention?
Alstom (ENXTPA:ALO) just landed a €1.2b contract with TransPennine Express for Britain’s first mainline battery-electric train fleet, putting long-term supply and maintenance revenues in sharper focus for equity investors.
These headline contracts arrive after a tough stretch for Alstom shareholders. The share price is down 38.21% year to date, and the 1-year total shareholder return has declined 24.19%, even as fresh orders in the UK and Canada have started to shift attention back to contract visibility and perceived execution risk.
Scan for other rail and infrastructure plays showing similar contract momentum by running the curated 39 power grid technology and infrastructure stocks alongside Alstom on your watchlist.
Alstom now has heavyweight contracts and a clear role in rail decarbonisation, yet the share price has fallen hard. Is a solid industrial story being mispriced, or is the lower valuation simply catching up with it?
Most Popular Narrative: 27.5% Undervalued
Alstom's most followed valuation narrative points to a fair value of €21.89 against a last close of €15.88, which frames the recent contract wins inside a much bigger earnings and margin story.
The analysts have a consensus price target of €21.89 for Alstom based on their expectations of its future earnings growth, profit margins and other risk factors.
We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Want to see what underpins that gap between price and fair value for Alstom? The narrative leans on accelerating earnings, firmer margins, and a lower future profit multiple than many investors might assume. The specific mix of growth, profitability and required P/E is where the story really gets interesting.
Result: Fair Value of €21.89 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, supply chain delays in rolling stock and the drag from low margin legacy contracts could quickly challenge this optimistic Alstom valuation story.
Find out about the key risks to this Alstom narrative.
Another View On Alstom’s Valuation
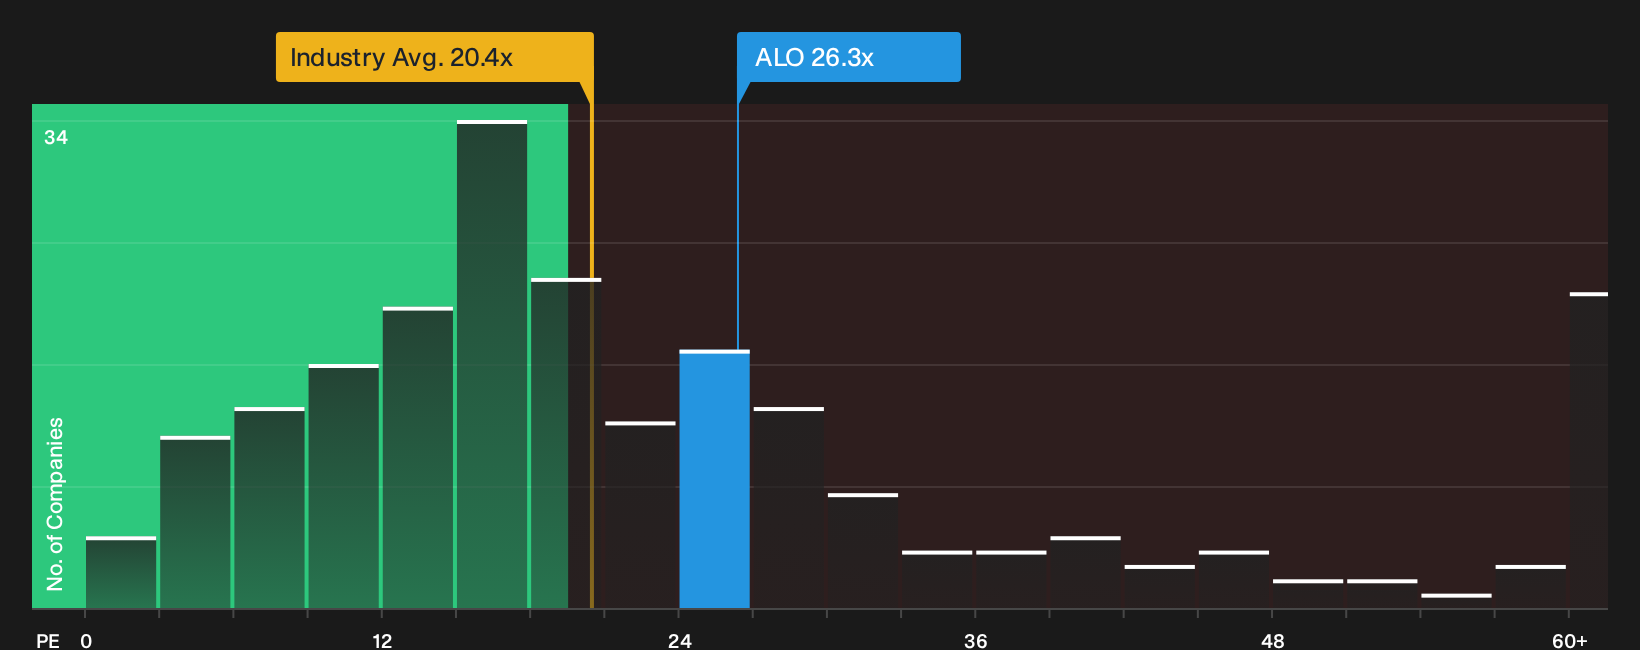
The analyst narrative frames Alstom as 27.5% undervalued, yet the market is charging a P/E of 26.3x against a European Machinery average of 20.4x and a peer average of 17x, while the fair ratio is 32.3x. That mix points to real valuation debate. Is this a mispriced opportunity or a premium that still needs more proof?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Alstom's valuation and contract momentum only matter if you evaluate them directly, so consider acting promptly and weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Alstom?
Do not stop with Alstom. Fresh opportunities sit across the market, and a quick screen can surface ideas you would not spot just scrolling headlines.
- Target value-focused opportunities by running the 183 high quality undervalued stocks that filters for quality companies trading at a discount.
- Prioritise resilience in tough markets with the 99 resilient stocks with low risk scores that highlights businesses carrying lower overall risk scores.
- Spot under-the-radar potential by using the 619 high quality undiscovered gems that surfaces quality fundamentals before they are widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com