
Sanmina Stock Price In Focus After Whistleblower Settlement Over Defense Contract Costs
- SCI Technology and parent Sanmina previously settled and saw dismissal of a whistleblower lawsuit over alleged misapplied cost accounting on U.S. defense contracts and wage law issues, agreeing to pay the government US$4.5 million plus US$1.4 million in attorneys’ fees while admitting no wrongdoing.
- The case spotlights how Sanmina’s cost accounting controls and labor compliance on government work intersect with its broader push into higher value defense and infrastructure contracts.
- We will look at how Sanmina's investment narrative interacts with the cost accounting whistleblower settlement and related compliance questions.
Scan beyond Sanmina and stress test your portfolio’s defense and infrastructure exposure with companies that pass our compliance and balance sheet filters using the list of solid balance sheet and fundamentals (23 results).
Sanmina Investment Narrative Recap
To own Sanmina, you need to believe in its push up the value chain into complex electronics for data centers, defense and infrastructure, supported by automation and full system integration. The big near term swing factor remains execution on this higher complexity mix while keeping margins under control after a year where net profit margin eased to 2.4% from 3.2%.
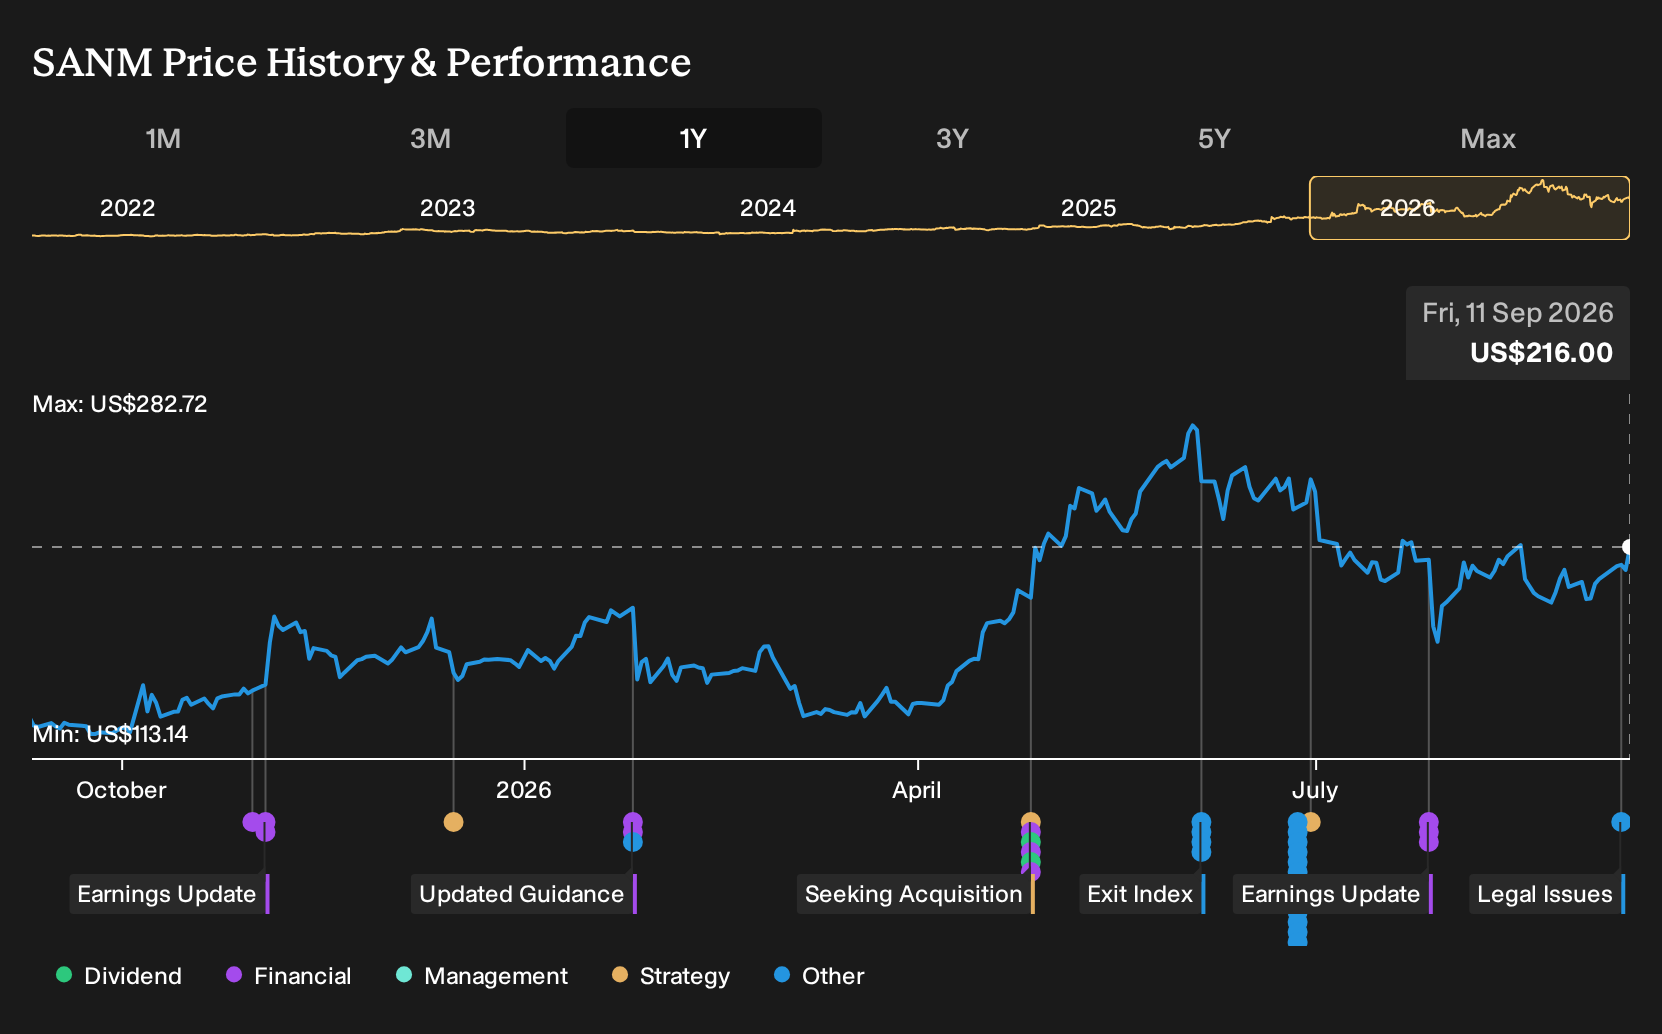
The whistleblower settlement looks financially small next to a US$11.6b market cap, so the immediate earnings impact is limited. The more relevant question is how tightly Sanmina runs cost accounting and labor compliance as it takes on larger defense and cloud contracts. Any sign of weak controls would add to existing integration and customer concentration risks.
Recent commentary around the planned acquisition of ZT Systems matters most against this legal backdrop. Management is gearing the group toward data center and AI infrastructure work, which could add US$5b to US$6b in annual run rate revenue and materially reshape how the combined operation looks and feels for customers.
That scale up would raise the bar on internal controls, inventory discipline and pricing oversight across U.S., Mexico and India facilities. ZT brings sizeable inventory and working capital exposure, so investors now have two linked questions: Can Sanmina integrate ZT cleanly while managing that inventory risk, and can it do so under sharper scrutiny of its cost accounting practices after the settlement?
Sanmina's current analyst story points to forecast revenues of US$20.6b and earnings of US$792.1m by 2029, anchored on an assumed 17.2% annual revenue growth rate and an increase in earnings of about US$484m from US$308.1m today.
Uncover why Sanmina's fair value indicates a 20% potential upside to its current price, before that discount starts to close.
Exploring Other Perspectives
One alternate view worries less about ZT Systems and more about Sanmina’s heavy tilt toward a few AI hardware programs. Those analysts already pencilled in slower progress, with revenue only reaching about US$19.9b and earnings of roughly US$701.7m by 2029. You can treat today’s legal settlement as a fresh reason to compare both narratives yourself.
Explore 2 other Sanmina fair value estimates, including one that suggests up to 84% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your Sanmina research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sanmina. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sanmina's overall financial health at a glance.
Looking for more investment ideas beyond Sanmina?
Once you have a view on Sanmina, it can help to set it alongside a wider watchlist so you can judge risk, quality and income potential across your whole portfolio rather than in isolation.
- If you want a shortlist of companies that combine strong balance sheets with solid fundamentals, start by scanning our list of solid balance sheet and fundamentals (23 results).
- For investors hunting for quality at a reasonable price, you can narrow the field to potential value opportunities with the 32 high quality undervalued stocks.
- If portfolio income is a priority and you care about dividend resilience, filter for higher yielding payers that pass our quality checks through the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com