
Is D'Ieteren Group (ENXTBR:DIE) Undervalued Following Its CEO Change And Stronger Half Year Earnings?
CEO transition and fresh earnings put D'Ieteren Group in focus
D'Ieteren Group (ENXTBR:DIE) has moved into the spotlight after appointing incoming chief executive officer Eric Machiels and releasing half year 2026 results that showed higher net income and earnings per share, alongside slightly softer sales.
D'Ieteren Group shares trade at €170.3 after a 1-day share price return of 1.73%, even though the stock has slipped over the past week and month. A 10.16% year-to-date share price gain and strong 3-year and 5-year total shareholder returns suggest longer term momentum remains intact.
Scan how D'Ieteren Group compares with other resilient compounders by reviewing our curated list of 183 high quality undervalued stocks that pair earnings strength with solid balance sheets.
D'Ieteren Group now pairs a higher share price with firmer earnings and a pending CEO change. Does that mix still leave enough upside in the risk reward, or has the recent move already done most of the work?
Most Popular Narrative: 26% Undervalued
D'Ieteren Group's most followed valuation story pegs fair value at around €230 per share, well above the recent €170.3 close. This keeps the spotlight firmly on what the portfolio might be worth as a whole rather than just the Belgian car distribution arm.
The market still tends to look at D’Ieteren through the lens of a Belgian car distributor. That lens catches the weakest part of the story, but not the most valuable one. The real debate today is whether investors are giving enough credit to Belron and the wider portfolio of mobility and aftermarket assets, or whether the holding-company discount should keep dominating the stock.
Want to see how this valuation is built? The narrative leans on cash generative assets, segment level earnings power and a holding company discount that does a lot of heavy lifting.
According to Ivoed, the fair value of €229.98 hinges on Belron's contribution to group cash flow, the role of businesses like PHE and TVH, and an explicit haircut to reflect leverage, private asset uncertainty and holding structure. That framework treats D'Ieteren Group less as a cyclical Belgian auto distributor and more as a collection of mobility and aftermarket platforms, with Belron placed at the centre of the story and D'Ieteren Automotive as the weaker piece that still shapes how the market prices the share.
The same narrative points to adjusted profit before tax of €955.6m and free cash flow of €373.9m in FY2025, alongside a proposed €2.00 dividend, as evidence that the underlying operations remain cash generative even as the automotive segment faces a tougher backdrop. It also flags internal estimates of gross net asset value around €279 per share and a discounted fair value near €237 per share after applying a 15% holding company markdown, which is where the implied 26% upside comes from when set against the current €170.3 share price.
Result: Fair Value of €229.98 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, two things could crack this story quickly. A prolonged drag at D'Ieteren Automotive or a weaker Belron cash profile would challenge the current valuation narrative.
Find out about the key risks to this D'Ieteren Group narrative.
Another view on D'Ieteren Group's valuation
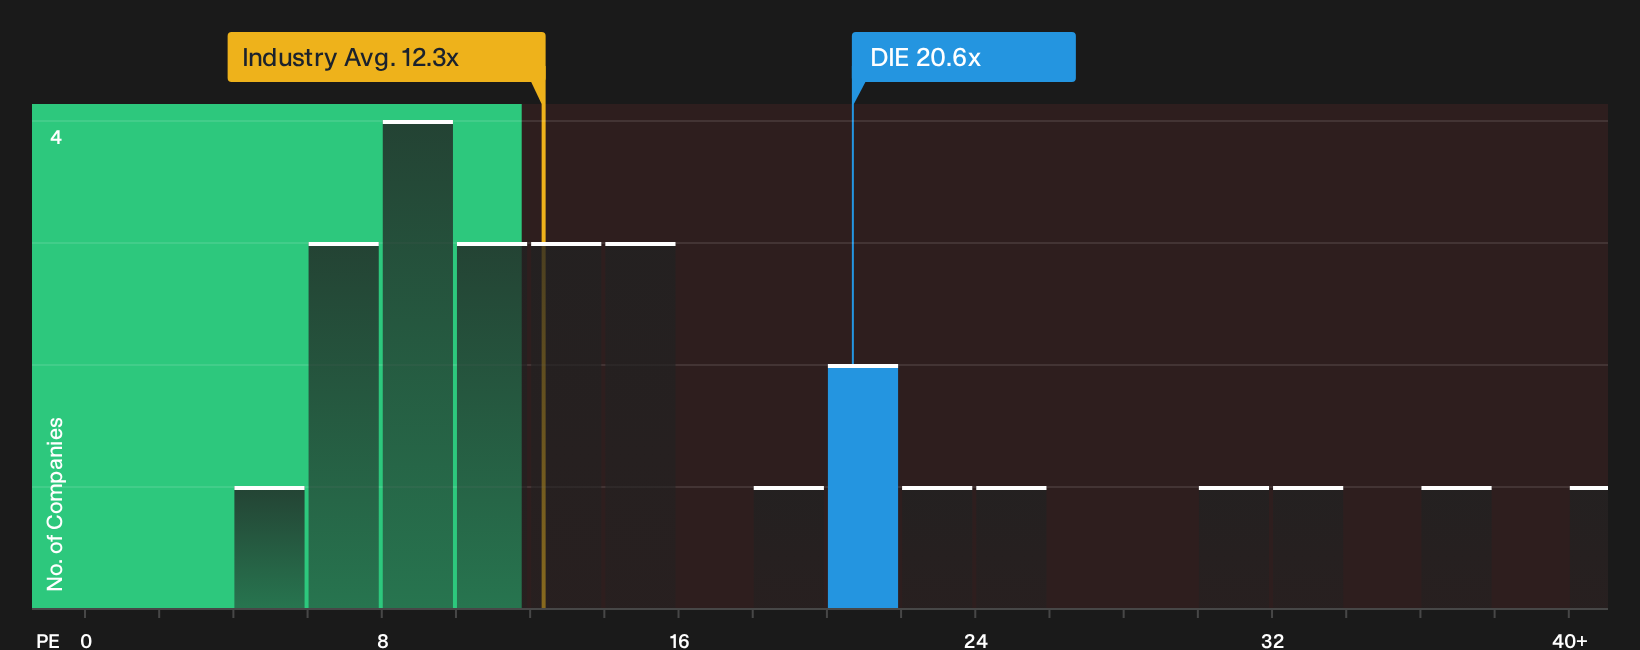
The DCF story paints D'Ieteren Group as 26% undervalued, yet the market is charging a richer 20.6x P/E compared with 12.3x for the wider European retail distributors group and 12.7x for closer peers. That premium hints at less margin for error if growth or cash flows disappoint.
For a closer look at how this pricing stacks up against fundamentals and what the fair ratio could drift toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this D'Ieteren Group story seems to sit at a finely balanced point between promise and pressure, consider acting while the data is current and stress test the thesis yourself using the 3 key rewards and 2 important warning signs.
Looking for more D'Ieteren Group style ideas?
If this D'Ieteren Group setup has sharpened your thinking, do not stop here. Broaden your watchlist now so you are not reacting after the next move.
- Zero in on quality at a discount by reviewing our focused set of 183 high quality undervalued stocks that combine earnings strength with disciplined pricing.
- Lock in potential income ideas by scanning a curated pool of 161 dividend fortresses that aim to pair higher yields with resilient cash flows.
- Prioritise resilience first by filtering for a 99 resilient stocks with low risk scores that concentrates on sturdier balance sheets and steadier return profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com