
Elco (TASE:ELCO) Dropped, So What Is Behind The Latest Update?
Elco (TASE:ELCO) is in focus after a twin update, with fresh second quarter results alongside a newly approved cash dividend of ₪0.7651288 per share, totaling ₪20,000,000 for ordinary shareholders.
At a share price of ₪126.7, Elco has seen its short-term momentum soften, with the share price return down 7.85% over the past week and 15.53% over 90 days. The 3-year total shareholder return of 17.44% contrasts with a 22.87% decline over the past year as investors weigh weaker earnings against the new dividend announcement.
Scan how Elco stacks up against other potential value ideas by reviewing a curated set of 183 high quality undervalued stocks that combine stronger fundamentals with discounted market pricing.
Bulls see Elco as a diversified group trading below estimated intrinsic value, while bears point to the sharp earnings drop and sliding share price. As you weigh valuation next, which story do the current numbers lean toward?
Preferred P/E of 138.4x: Is It Justified?
Elco screens as expensive on a simple yardstick. At a share price of ₪126.7, the stock trades on a P/E of 138.4x, while sitting at a discount of 15.6% to an estimated fair value of ₪150.15 from the SWS DCF model.
The P/E ratio compares what investors pay today for each unit of current earnings. For Elco, a P/E of 138.4x against earnings that have declined by 49.3% per year over the past 5 years suggests the market price is attaching a high value to a relatively small profit base.
That tension becomes clearer when you line Elco up against peers. Management is dealing with earnings that fell 65.7% over the past year and a net profit margin of 0.1%, yet the stock trades at a P/E that is much higher than both the IL Construction industry average of 36x and the peer average of 19.5x. Those gaps point to a valuation that is rich compared to what similar businesses command in the market.
See what the numbers say about this price — find out in our valuation breakdown..
Result: Preferred multiple of Price-to-Earnings of 138.4x (OVERVALUED)
Still, Elco’s sharp 1 year total return decline of 22.87% and earnings drop over the past 5 years could reset investor expectations quickly if sentiment weakens further.
Find out about the key risks to this Elco narrative.
Another View On Elco’s Value
The earnings based multiple paints Elco as expensive, yet the SWS DCF model points the other way. At ₪126.7, the stock trades about 15.6% below an estimated cash flow value of ₪150.15, which frames the same business as undervalued. Which lens do you trust more when profits are this thin?
Look into how the SWS DCF model arrives at its fair value.
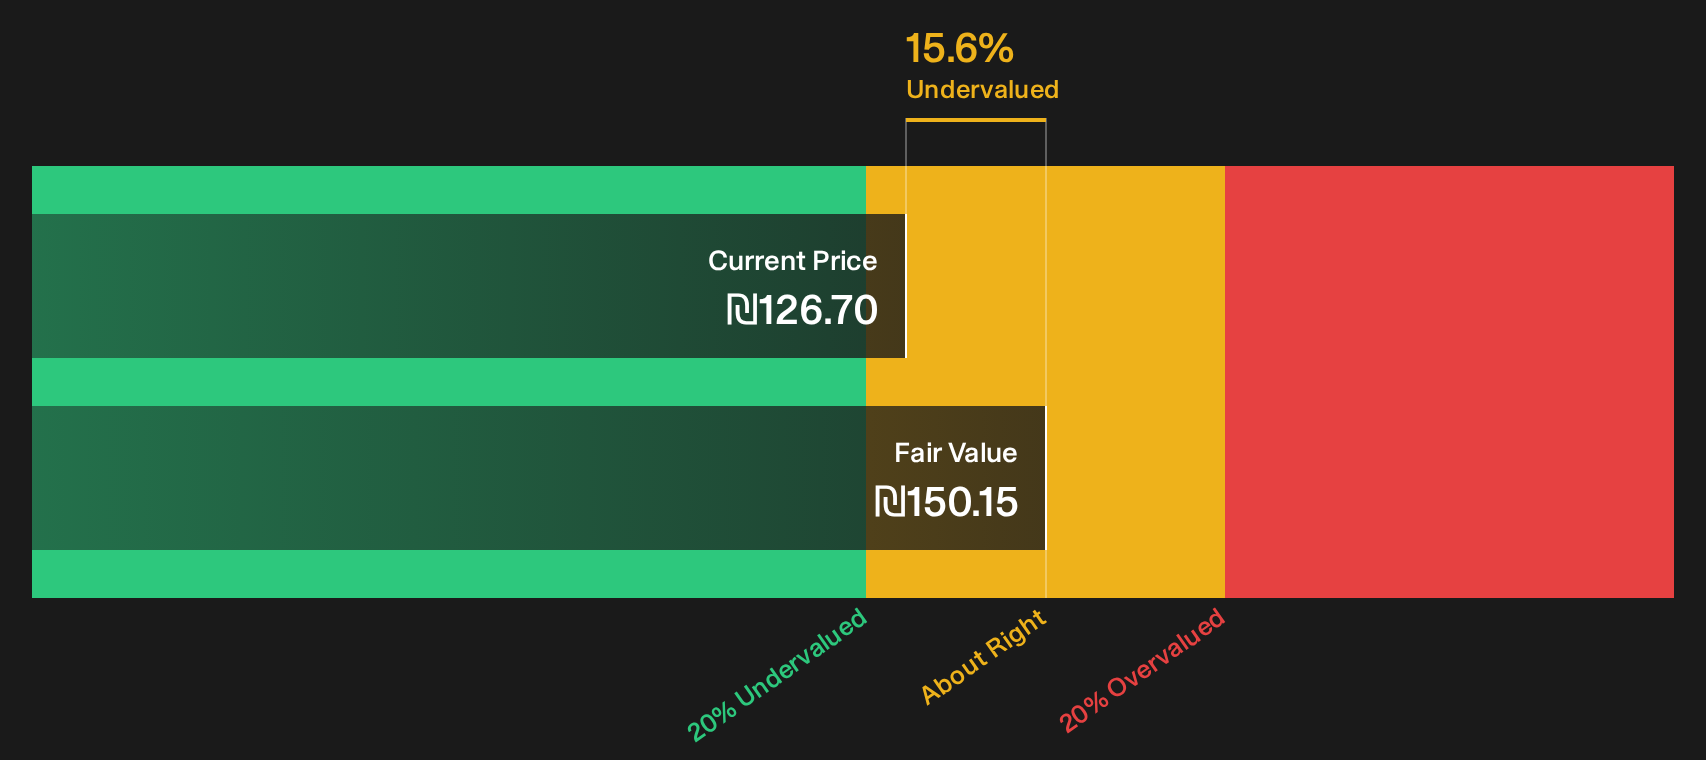
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Elco for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 183 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Elco can feel confusing, especially with both risks and potential upsides on the table. Act while the data is fresh and form your own view by weighing the 1 key reward and 4 important warning signs.
Looking For More Investment Ideas Beyond Elco?
If Elco has sharpened your focus on valuation, do not stop here. Broader research across quality watchlists can widen your opportunity set and refine your judgment.
- Target potential mispricings by scanning a curated 183 high quality undervalued stocks that pair stronger fundamentals with discounted share prices.
- Strengthen your income stream by reviewing a hand picked set of 161 dividend fortresses designed for investors who care about consistent cash payouts.
- Prioritise resilience by checking a 99 resilient stocks with low risk scores built around companies with more robust risk profiles and steadier financial characteristics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com