
Is Clas Ohlson (OM:CLAS B) Fairly Valued Following Its Higher Dividend Payout?
Clas Ohlson (OM:CLAS B) has put shareholder cash returns in focus after its 11 September AGM approved both a higher ordinary dividend and an extra payout, together totaling SEK 14 per share.
That dividend decision comes after a busy stretch for Clas Ohlson, with first quarter results on 3 September showing higher sales and earnings, and the AGM on 11 September locking in the larger cash return. The share price has gained 42.69% year to date and the 5 year total shareholder return is 491.68%, pointing to strong long term momentum even as the 7 day share price return is down 3.78%.
Scan how Clas Ohlson’s dividend move compares with other income opportunities by reviewing a curated set of 161 dividend fortresses in the market today.
Bulls see Clas Ohlson’s richer dividend as proof the current valuation still leaves room for upside. Bears point to the strong multiyear share gains and ask whether the stock already reflects the good news.
Most Popular Narrative: 1% Undervalued
Clas Ohlson’s most followed valuation storyline places fair value at SEK 437.50, very close to the last close of SEK 433.20, which keeps the focus on the cash generation behind that estimate.
The store expansion strategy, with a goal of adding approximately 10 new stores annually, combined with improvements in existing stores, is expected to sustain organic growth and enhance revenue. Efforts to establish a cost-competitive operating model, notably through optimized sourcing and inventory management, are likely to contribute to higher net margins and overall earnings.
Want to see what underpins that near one to one match between price and fair value? The narrative focuses on steady top line progress, rising profitability and a future earnings profile that has to support a richer multiple than the wider retail sector.
Result: Fair Value of SEK 437.50 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Clas Ohlson story can appear fragile if currency swings squeeze gross margins or if higher salary costs and new store spending erode profitability.
Find out about the key risks to this Clas Ohlson narrative.
Another View on Clas Ohlson’s Valuation
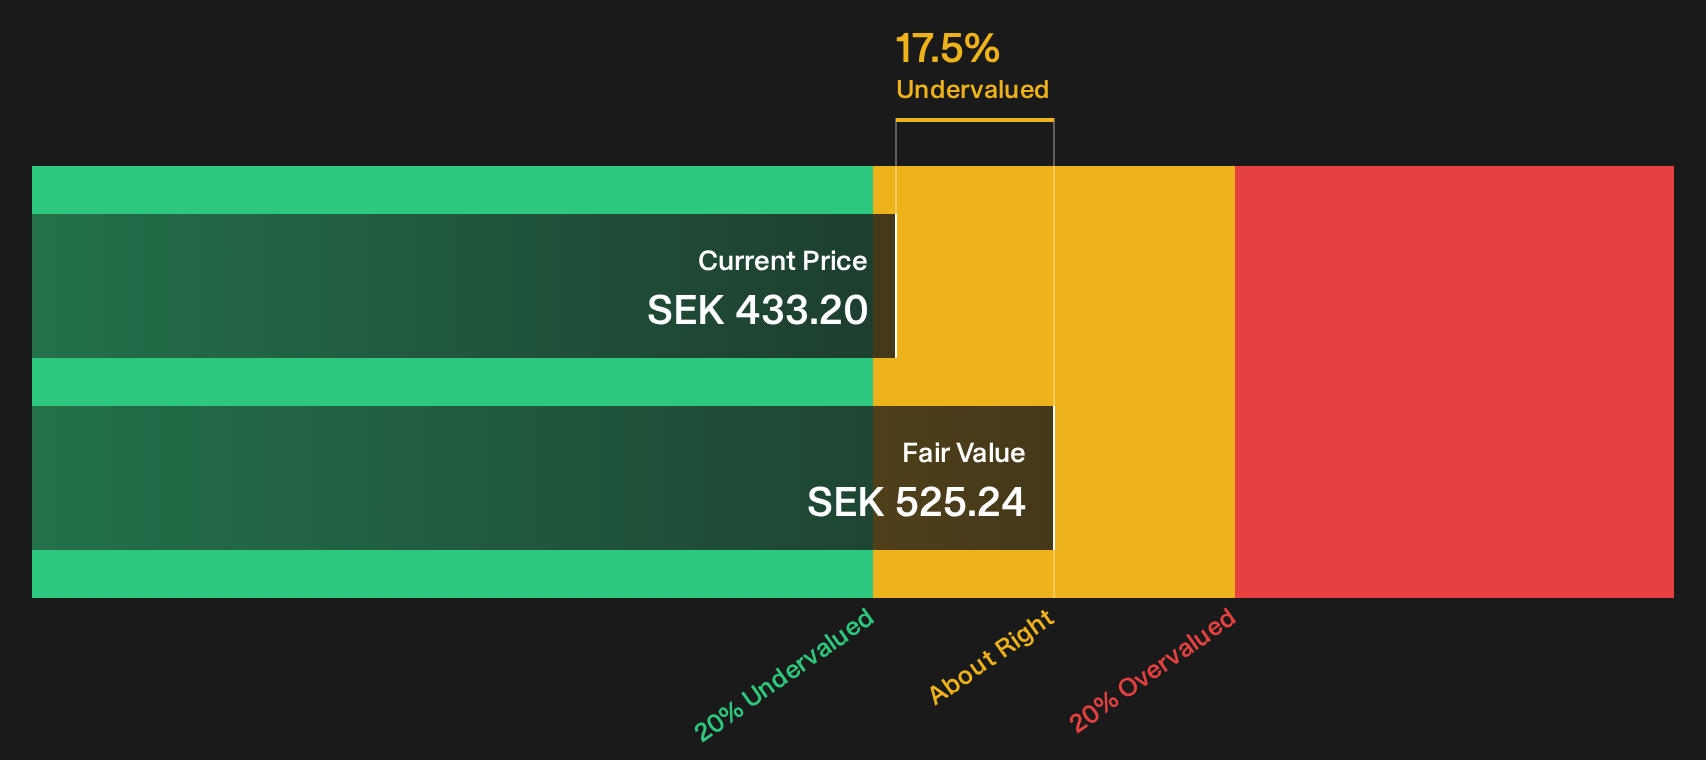
While the narrative fair value pegs Clas Ohlson close to its recent share price, the SWS DCF model presents a different picture. At SEK 433.20, the stock is priced about 17.5% below an estimated cash flow value of SEK 525.24, which frames the current level as undervalued. Which signal do you trust more: the story or the spreadsheet?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Clas Ohlson’s value and risk profile can either feel reassuring or unsettling, depending on your lens. Use the full set of numbers, sentiment markers and valuation tools available, then pressure test your own thesis against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Clas Ohlson?
Do not stop with Clas Ohlson. Broaden your watchlist using focused stock ideas so you can compare income, quality and upside potential across different corners of the market.
- Target higher yields and more durable payouts by scanning a curated set of 161 dividend fortresses that prioritise strong income profiles backed by underlying fundamentals.
- Hunt for shares that combine quality and pricing support through a carefully filtered group of 183 high quality undervalued stocks built around both balance sheet strength and cash generation.
- Zero in on financial resilience by reviewing a list of solid balance sheet and fundamentals (194 results) that highlights businesses with cleaner debt positions and room to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com