
Is Insight Enterprises (NSIT) Fully Valued As Earnings Estimates Rise?
Insight Enterprises (NSIT) is back on investors’ radar after a recent Zacks Rank upgrade to #1, supported by higher full-year earnings estimates and a sharp year-to-date share price gain.
The recent Zacks Rank upgrade comes on top of powerful momentum, with a 90 day share price return of 49.24% and a year to date share price return of 96.96% at a last close of $165.37. Total shareholder returns over one and five years of 33.29% and 82.21% respectively show how Insight Enterprises has rewarded patient holders even before this latest surge.
Scan how Insight Enterprises compares with other fast moving tech plays by reviewing the curated 89 AI infrastructure stocks that are catching renewed interest after strong earnings sentiment shifts.
Insight Enterprises has already made a big move, so the real tension now is whether to accept today’s price or wait for a cleaner pullback. The valuation work starts to answer that next.
Most Popular Narrative: 1% Overvalued
The most followed valuation view puts Insight Enterprises' fair value at $163.75, a touch below the recent $165.37 close, which keeps attention squarely on what assumptions sit underneath that gap.
The analysts have a consensus price target of $163.75 for Insight Enterprises based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $9.9 billion, earnings will come to $392.5 million, and it would be trading on a PE ratio of 13.8x, assuming you use a discount rate of 9.9%.
Want to see what kind of earnings climb and margin reset are baked into that fair value for Insight Enterprises? The key drivers may surprise you. The projected mix of recurring services, buybacks and a lower future earnings multiple tells a very specific story about where the narrative expects this business to end up.
Result: Fair Value of $163.75 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, if large enterprise tech budgets tighten or vendor program changes pressure Insight Enterprises' margins, the current analyst narrative could quickly lose conviction.
Find out about the key risks to this Insight Enterprises narrative.
Another View: SWS DCF Says Insight Enterprises Is Undervalued
The analyst narrative pegs Insight Enterprises at 1% overvalued around $163.75, yet the SWS DCF model points in the opposite direction. On that cash flow view, NSIT at $165.37 trades about 7.4% below an estimated value of $178.66, which raises a sharper question: Are earnings multiples stretched, or are cash flows being underappreciated?
Look into how the SWS DCF model arrives at its fair value.
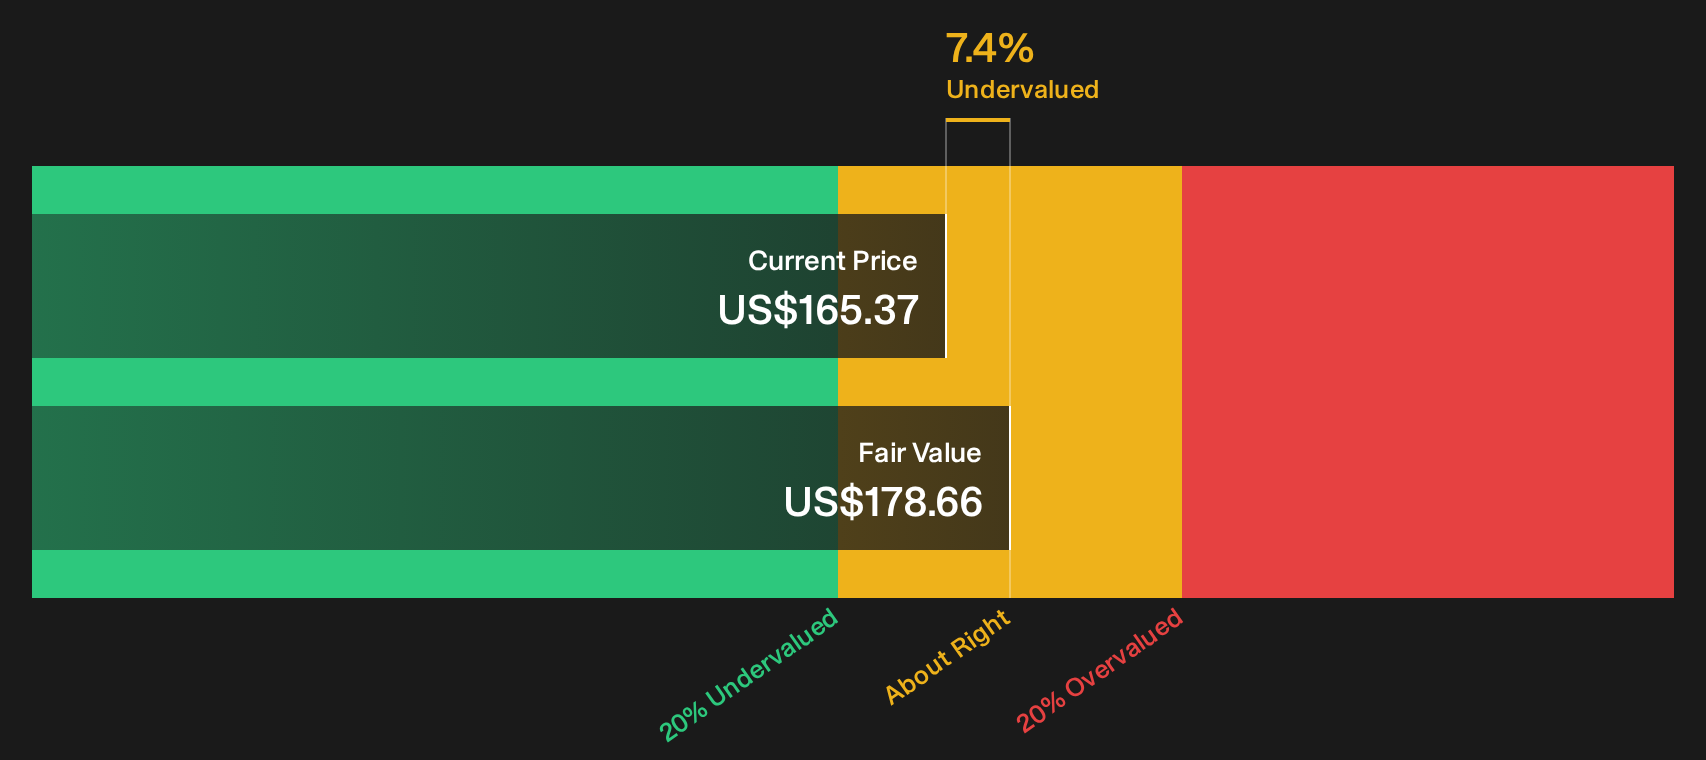
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Insight Enterprises for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Insight Enterprises story today. If you want to move before sentiment shifts again, weigh the upside against the caution flags with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Insight Enterprises?
If Insight Enterprises has sharpened your focus, do not stop here. Fresh ideas often come from looking one step wider than the obvious opportunities.
- Hunt for quality at a discount by scanning the 32 high quality undervalued stocks that line up solid fundamentals with prices that may not fully reflect them yet.
- Stack income potential on top of capital growth plans by reviewing the 6 dividend fortresses that aim to combine robust yields with resilience.
- Prioritise staying power in tougher markets by filtering for a list of solid balance sheet and fundamentals (23 results) that can better handle shocks without constant refinancing risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com