
Is Edge AI Partnership Altering The Investment Case For Capgemini (ENXTPA:CAP)?
- Ambarella announced it has engaged Capgemini to accelerate Edge and Physical AI solutions across sectors such as smart infrastructure, retail, logistics, industrial automation, healthcare, and automotive, supported by a new global Center of Excellence and Capgemini’s engineering and systems integration capabilities.
- The agreement deepens Capgemini’s role in AI workloads that sit closer to where data originates. This speaks directly to demand for higher value, complex digital transformation projects rather than more commoditised IT services.
- We will now explore how Capgemini’s deeper push into Edge and Physical AI with Ambarella could reshape the broader investment narrative.
Scan how Capgemini’s AI push compares with other potential beneficiaries of this trend by reviewing our curated list of 89 AI infrastructure stocks.
Capgemini Investment Narrative Recap
To stay comfortable as a Capgemini shareholder, you need to believe the shift toward cloud, data, and AI work will remain the main engine of higher value contracts, even as demand in some European end markets stays patchy. The Ambarella partnership fits that storyline but probably does not change the near term picture on its own.
The key short term catalyst still sits in evidence that bookings in advanced AI and automation convert cleanly into organic revenue and margin stability after a year of weaker earnings and lower net profit margins. The biggest current risk remains pressure on pricing and utilization, especially in Europe, combined with restructuring and FX noise.
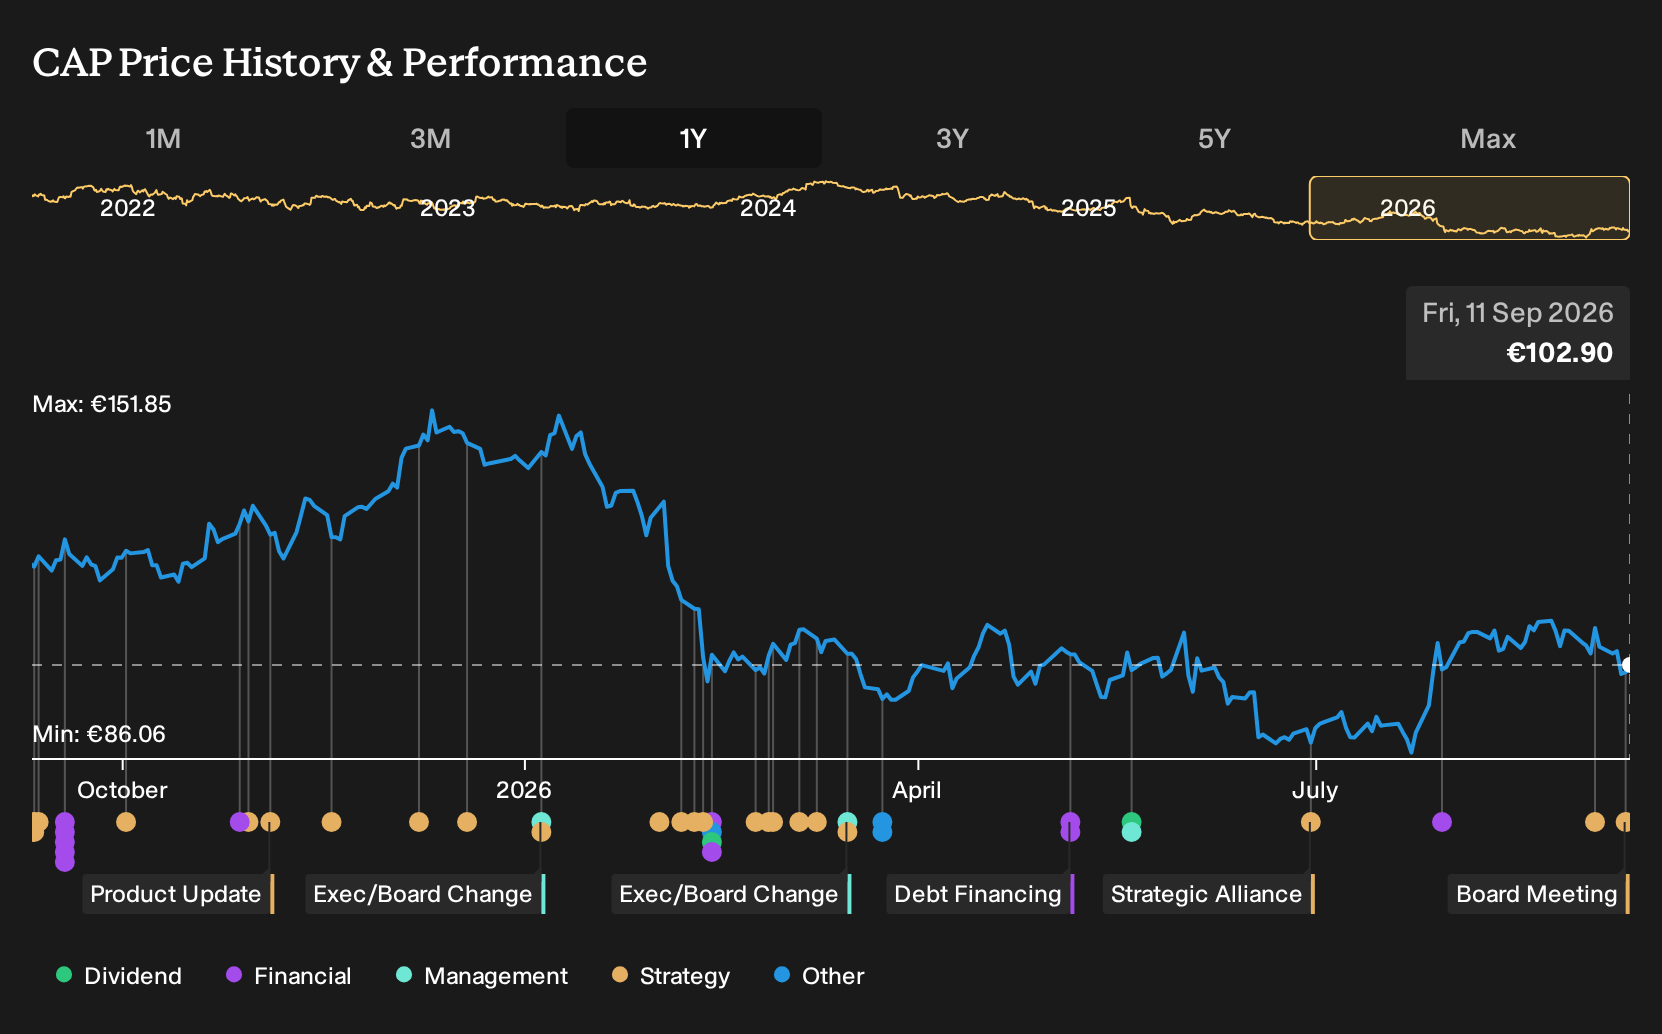
The upcoming 10 June 2026 board meeting to authorize a dedicated share buyback envelope is the most relevant adjacent announcement to watch. It would sit alongside the existing €2b multi year program and would matter mainly for how investors interpret management’s stance on cash generation and balance sheet flexibility.
For you, the operational link is simple. Consistent free cash flow and control of Capgemini’s high debt position are what make any extra repurchases sustainable. If execution on AI rich projects like the Ambarella collaboration stalls, or restructuring and tax costs stay elevated, expectations around capital returns could clash with the need to preserve financial resilience.
Capgemini’s current earnings are €1.4b, with analysts forecasting consensus earnings of €2.1b by 2029. This implies an earnings increase of about €700m and revenue growth assumptions of 4.7% per year, reaching €26.9b of revenue and €2.1b of earnings by that same year.
Uncover why Capgemini's fair value indicates a 36% potential upside to its current price, before the market closes the gap.
Exploring Other Perspectives
Pessimistic analysts focus on a different risk for Capgemini. They worry that weak sectors and pricing pressure lock the group into low growth, so their 2029 earnings view sits closer to €1.8b, not €2.5b. Those forecasts were set before the Ambarella deal and planned buyback envelope, so fresh news could shift that spread.
Explore 3 other Capgemini fair value estimates, including one that suggests as much as 65% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Capgemini research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Capgemini. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capgemini's overall financial health at a glance.
Looking For More Investment Ideas Beyond Capgemini?
Capgemini may fit your thesis on AI heavy services, but your portfolio is rarely built around a single stock. A targeted screener can help you spot other opportunities that match your risk tolerance and income goals while you weigh up Capgemini’s role.
- If you want potential mispricing with stronger fundamentals, start with a curated set of 619 high quality undiscovered gems that may not yet be widely followed by the market.
- For investors who care most about capital resilience, focus on a 99 resilient stocks with low risk scores that emphasises companies with steadier risk profiles and fewer financial red flags.
- Income oriented holders can zero in on reliable cash returns by scanning a focused group of 161 dividend fortresses that may suit a yield driven strategy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com