
What FLSmidth (CPSE:FLS)'s New Mining Services Deal Means For Shareholders
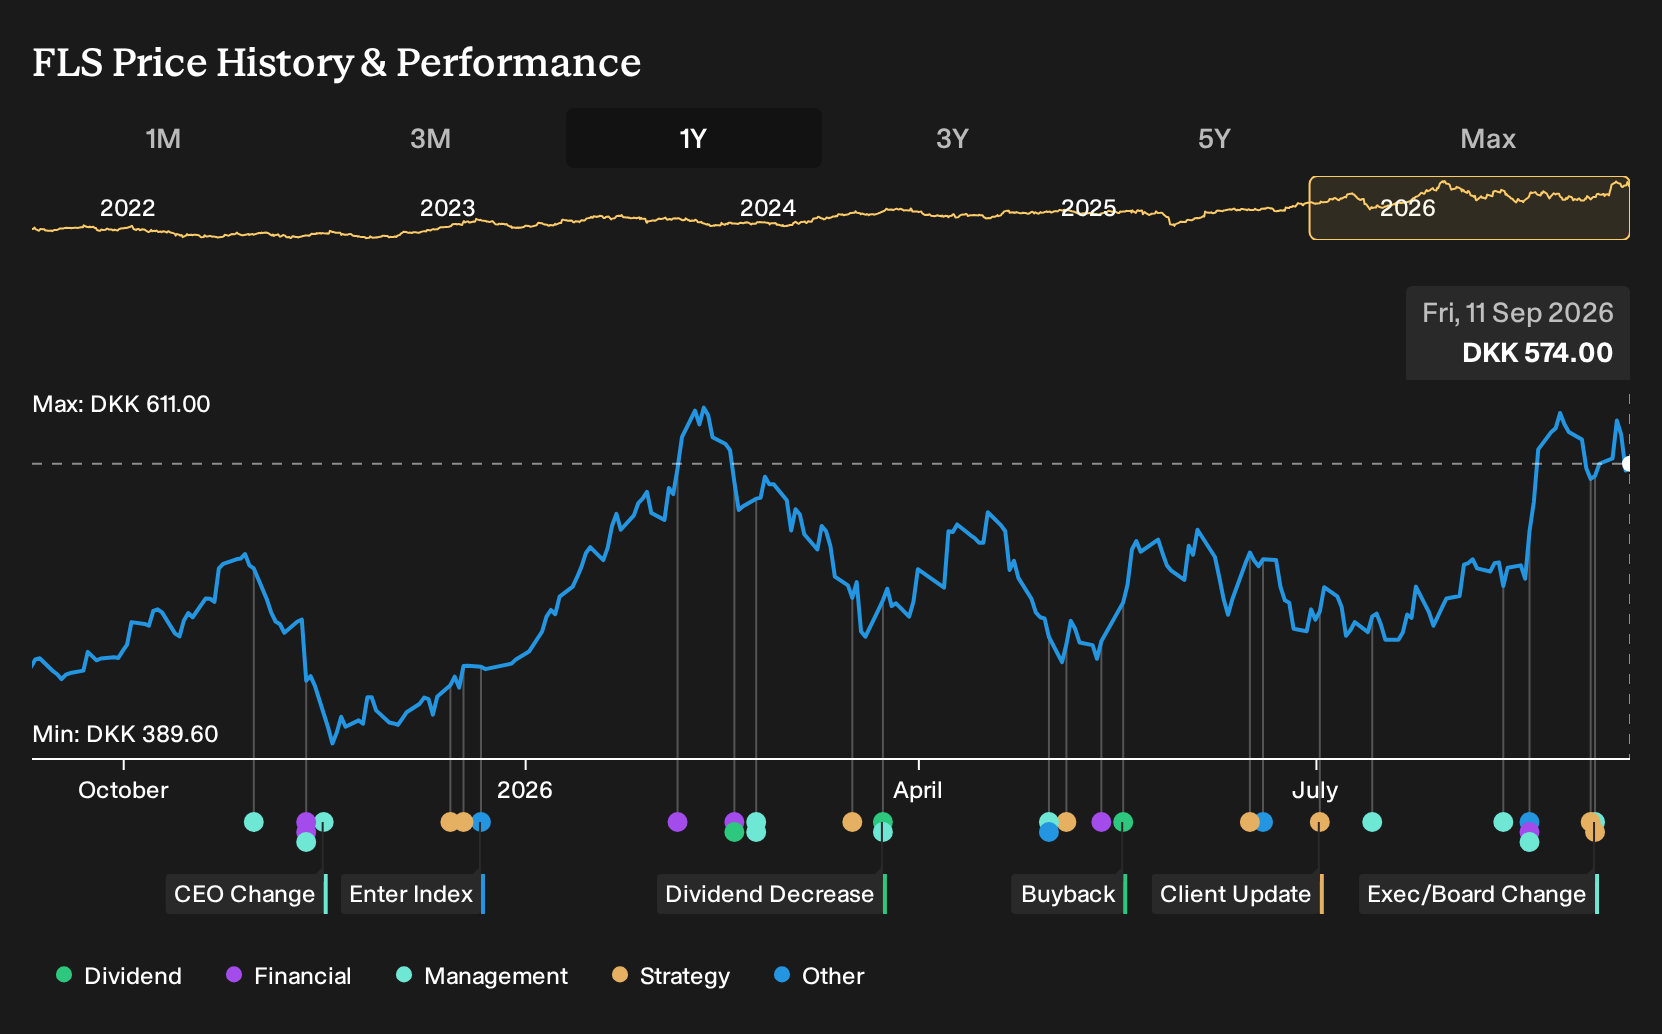
- FLSmidth has outlined a plan to reorganise into four business lines from January 2027 and has signed a lifecycle agreement covering the full equipment flowsheet for Lloyds Metals and Energy Limited’s expanding iron ore operations in India.
- The new Crushing, Sizing & Screening unit clusters higher volume, standardised offerings closer to mine sites, while the Lloyds Metals partnership adds a repair centre and embedded on site support, deepening FLSmidth’s presence in day to day production.
- We will now assess how FLSmidth’s dedicated Crushing, Sizing & Screening business line could reshape its investment narrative around services and aftermarket.
FLSmidth Investment Narrative Recap
To own FLSmidth, you need to believe the shift toward higher margin service and aftermarket work can steadily reduce reliance on lumpy capital equipment orders. The creation of a dedicated Crushing, Sizing & Screening unit and the Lloyds Metals lifecycle deal both lean into that story by tying the business closer to day to day mine operations.
The key near term swing factor still looks like execution on restructuring in Products and SG&A, while capital equipment demand remains cyclical and uneven. Reorganising into four lines adds complexity. The main risk is operational disruption or slower than planned cost alignment, rather than any immediate hit from the announced changes.
The Lloyds Metals lifecycle agreement is the most practical test case for FLSmidth’s service led ambition. A full flowsheet contract, on site team, repair centre and consumables management all speak directly to recurring aftermarket revenue, uptime focused relationships and deeper embedded positions at customer sites.
For catalysts, deals like this matter because they can support more stable cash generation even if large project sanctioning remains hesitant in some regions. The operational risk is that integrating bespoke maintenance programs and training across rapidly scaling mines stretches service capacity or exposes gaps in processes. That would dampen the benefit of the new Crushing, Sizing & Screening line.
FLSmidth’s analyst narrative points to DKK 17.8b in revenue and DKK 2.0b in earnings by 2029, based on assumed yearly revenue growth of 6.4% and an earnings increase of DKK 0.4b from DKK 1.6b today.
Uncover why FLSmidth's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into the aftermarket catalyst. The most optimistic analysts already pencilled in revenue rising to DKK 18.7b and earnings to DKK 2.2b by 2029, based on roughly 9.6% annual growth and richer margins. You might see FLSmidth’s new CSS line and the Lloyds Metals deal and wonder whether those forecasts start to look too cautious or still too bold. Investor opinions can differ widely, so it often helps to line up several narratives before you make up your mind.
Explore 2 other FLSmidth fair value estimates, including one that suggests there could be up to 28% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your FLSmidth research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FLSmidth. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FLSmidth's overall financial health at a glance.
Looking For More Ideas Beyond FLSmidth?
If the FLSmidth story has sharpened your focus on where cash flows and balance sheet strength really matter, it can help to line up a few other candidates on the same screen before committing fresh capital.
- For investors who want a mix of resilience and downside protection, start with companies that show robust finances through the 99 resilient stocks with low risk scores.
- If the priority is quality at a sensible entry point, sort for businesses that pair strong fundamentals with appealing valuations using the 619 high quality undiscovered gems.
- Income focused investors can narrow the field to firms targeting higher payout levels and sturdier cash coverage by scanning the 161 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com