
DocuSign (DOCU) Lifted Guidance And Added AI Updates, Is The Premium Already Priced In?
DocuSign (DOCU) just delivered a packed early September, with fresh quarterly results, higher full year revenue guidance, and a slate of AI focused product and customer announcements that all landed within days of each other.
Investors have reacted strongly to this early September news cluster from DocuSign, with the share price posting a 48.55% 90 day share price return and a 5.82% 30 day share price return. However, the 1 year total shareholder return is still down 18.13% and the 5 year total shareholder return has fallen 76.36%, which suggests that recent momentum has picked up after a difficult longer term stretch.
Capitalize on DocuSign’s AI and agreement momentum by scanning a hand picked set of contract driven and automation focused companies in the 89 AI infrastructure stocks.The swing in DocuSign has been sharp, which leaves you weighing a quick entry against waiting for the excitement to cool. How does the current valuation compare with the business you actually get today?
Most Popular Narrative: 7.6% Overvalued
On the widely followed narrative, DocuSign is pegged at a fair value of $60.99 against a last close of $65.65, which implies the market is paying a premium to that framework and puts pressure on the underlying assumptions to do a lot of heavy lifting.
On a market capitalisation basis, justifying roughly $11.0 billion at a 9% discount needs about $850 million of GAAP net income in 2031, which on 7% revenue growth implies a net margin near 19%.
The buyback lowers that materially, because the same earnings are spread across fewer shares. Once you run the inputs and I can solve the constant, I will pin the exact requirement. My provisional read is that at the current repurchase pace the requirement falls to roughly 15%, which is close to the base case, meaning DocuSign is priced near fair on these assumptions rather than obviously cheap or dear.
Want to see what has to go right for DocuSign to earn that price tag? The narrative leans on compounding revenue, rising GAAP margins and a future earnings multiple that assumes real staying power. Curious which specific growth, profitability and buyback inputs have to line up for this valuation to hold?
Result: Fair Value of $60.99 (OVERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the narrative cracks fast if IAM stalls below targets, or if share based compensation keeps running near 15% of revenue and blunts those margin ambitions.
Find out about the key risks to this DocuSign narrative.
Another View: SWS DCF Says Deeply Undervalued
The popular DocuSign narrative argues the stock trades about 7.6% above a $60.99 fair value. The SWS DCF model points in the opposite direction. It estimates DocuSign's future cash flows support a fair value near $157.65, which is roughly 58.4% above the current $65.65 share price. Which story do you trust more: the cash flow curve or the margin and multiple framework?
Look into how the SWS DCF model arrives at its fair value.
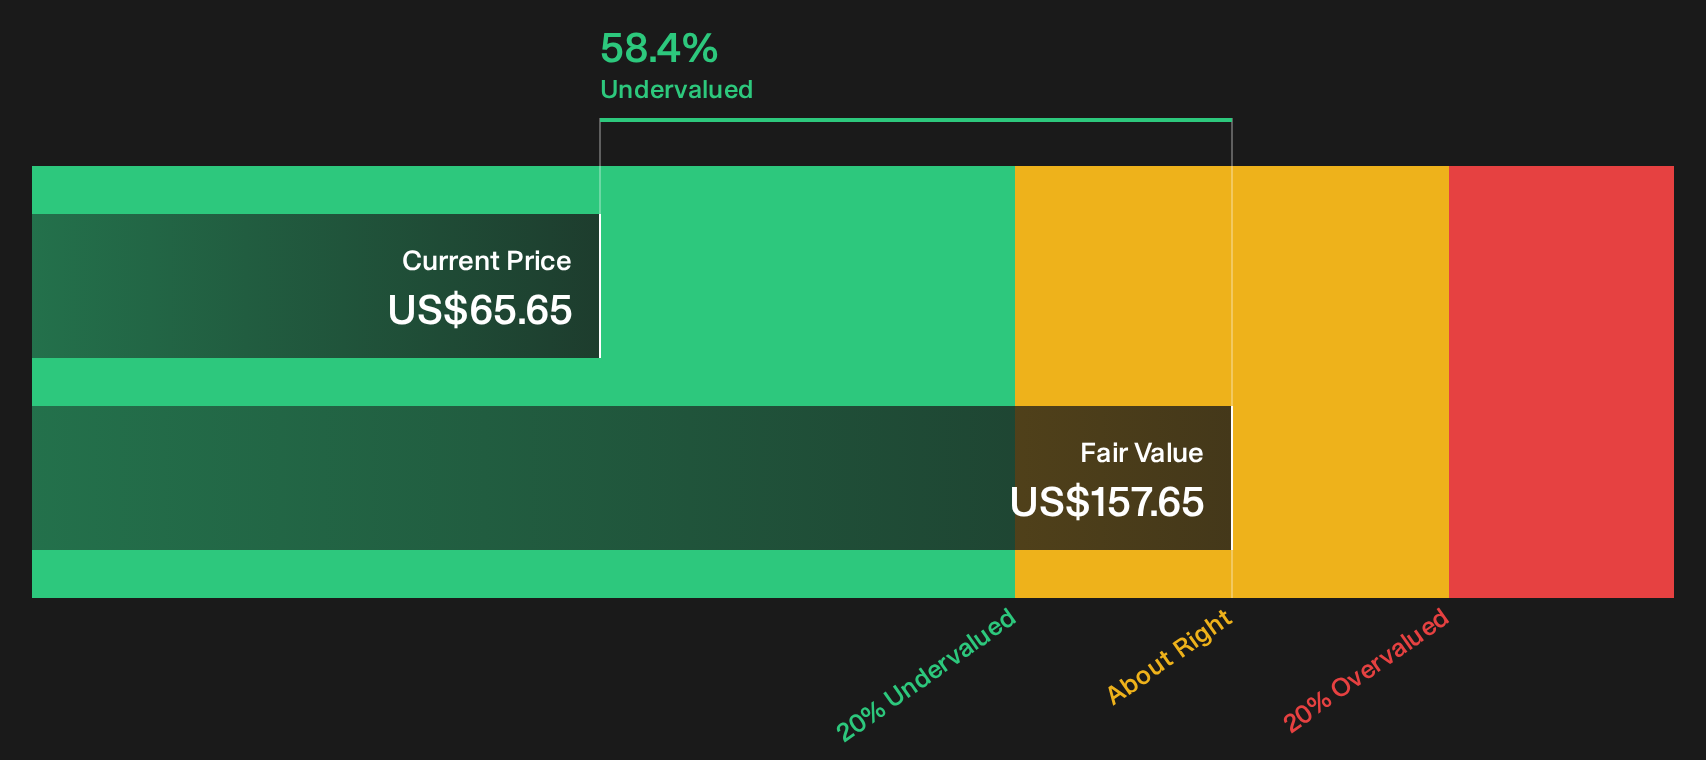
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DocuSign for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around DocuSign is split, so move quickly, stress test the assumptions and decide where you land on its risk reward trade off. To see the specific positives our work highlights, take a closer look at the 3 key rewards.
More DocuSign investment ideas beyond this stock
DocuSign's split opinions make this a perfect moment to widen your lens and use the Simply Wall Street Screener to compare fresh opportunities side by side.
- Target potential mispricings by lining up quality fundamentals against current market tags through the 32 high quality undervalued stocks.
- Prioritise resilience by filtering for companies with strong finances and lower perceived risk using the 11 resilient stocks with low risk scores.
- Hunt for future leaders early by scanning a focused pool of strong fundamental outliers in the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com