
Asian Undervalued Small Caps With Insider Buying For September 2026
As geopolitical tensions and rising oil prices continue to influence global markets, Asian small-cap stocks are navigating a complex landscape marked by inflation concerns and monetary policy shifts. In this environment, identifying potentially undervalued opportunities with insider buying can be crucial for investors seeking to capitalize on the resilience and growth potential of these smaller companies in Asia.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| BWP Trust | 6.8x | 13.3x | 22.42% | ★★★★★☆ |
| Universal Robina | 11.5x | 0.7x | 29.27% | ★★★★★☆ |
| Storage King Group | 9.3x | 5.8x | 8.77% | ★★★★★☆ |
| Australian Finance Group | 8.0x | 0.3x | 19.42% | ★★★★☆☆ |
| ReadyTech Holdings | NA | 1.5x | 47.05% | ★★★★☆☆ |
| Jumbo Group | 23.6x | 0.8x | 49.50% | ★★★☆☆☆ |
| China Yongda Automobiles Services Holdings | NA | 0.0x | -68.65% | ★★★☆☆☆ |
| Growthpoint Properties Australia | 16.7x | 4.5x | 19.39% | ★★★☆☆☆ |
| Hong Fok | 23.7x | 6.8x | 30.16% | ★★★☆☆☆ |
| Paragon Care | NA | 0.1x | -4.00% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
SKY Network Television (NZSE:SKT)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: SKY Network Television operates as a media and entertainment company offering services such as Sky Box subscriptions, streaming, broadband, and advertising with a market capitalization of NZ$0.57 billion.
Operations: SKT's primary revenue streams include Sky Box subscriptions generating NZ$445.22 million and streaming subscriptions contributing NZ$128.28 million, with additional income from advertising and broadband services. The company's net profit margin has shown variability, reaching 9.50% in December 2025 after a low of -76.49% in June 2019, indicating significant fluctuations over the analyzed periods.
PE: 8.1x
SKY Network Television, a smaller player in Asia's broadcasting sector, has been catching attention with recent insider confidence as they purchased shares between July and August 2026. Despite earnings forecasted to decline by an average of 10.9% annually over the next three years, SKY reported impressive growth in net income for fiscal year 2026 at NZ$59.38 million from NZ$20.23 million previously. The company anticipates revenue between NZ$825 million and NZ$840 million for fiscal year 2027, alongside a dividend increase to at least NZ$0.35 per share, demonstrating potential resilience despite financial challenges ahead.
- Click here to discover the nuances of SKY Network Television with our detailed analytical valuation report.
Explore historical data to track SKY Network Television's performance over time in our Past section.

D&L Industries (PSE:DNL)
Simply Wall St Value Rating: ★★★☆☆☆
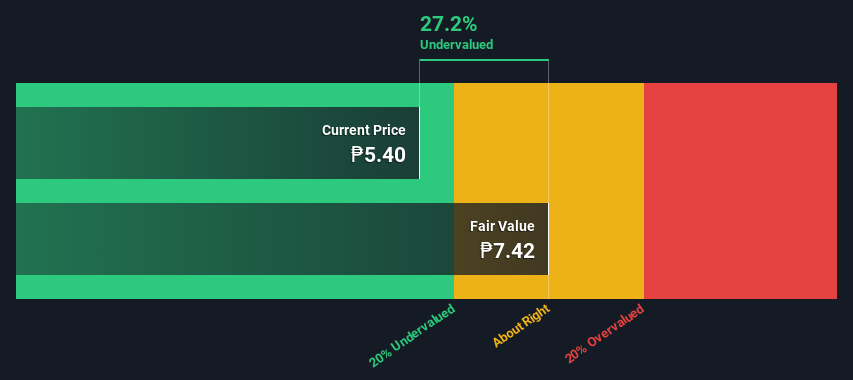
Overview: D&L Industries operates as a diversified manufacturer in the Philippines, focusing on food ingredients, colorants and plastic additives, oleochemicals, resins and powder coatings, and consumer products ODM, with a market capitalization of ₱65.71 billion.
Operations: D&L Industries generates revenue primarily from Food Ingredients, Oleochemicals, Resins and Powder Coatings, Colorants and Plastic Additives, Management and Administrative services, and Consumer Products ODM. The company experienced fluctuations in its net income margin over the years with a low of 4.67% in December 2025. The gross profit margin showed variability as well, peaking at 21.39% in June 2019 before declining to around 12.95% by September 2026.
PE: 9.3x
D&L Industries, a smaller player in Asia's market, shows potential despite its high debt levels and reliance on external borrowing. Recent insider confidence is evident as Alvin Lao acquired 1.2 million shares worth PHP 4.1 million, reflecting belief in the company's future. For the second quarter ending June 2026, sales and net income saw slight increases compared to last year. Earnings are expected to grow annually by 8.38%, suggesting positive momentum ahead for this company amidst its financial challenges.
- Dive into the specifics of D&L Industries here with our thorough valuation report.
Gain insights into D&L Industries' historical performance by reviewing our past performance report.
AEON Credit Service (Asia) (SEHK:900)
Simply Wall St Value Rating: ★★★★☆☆
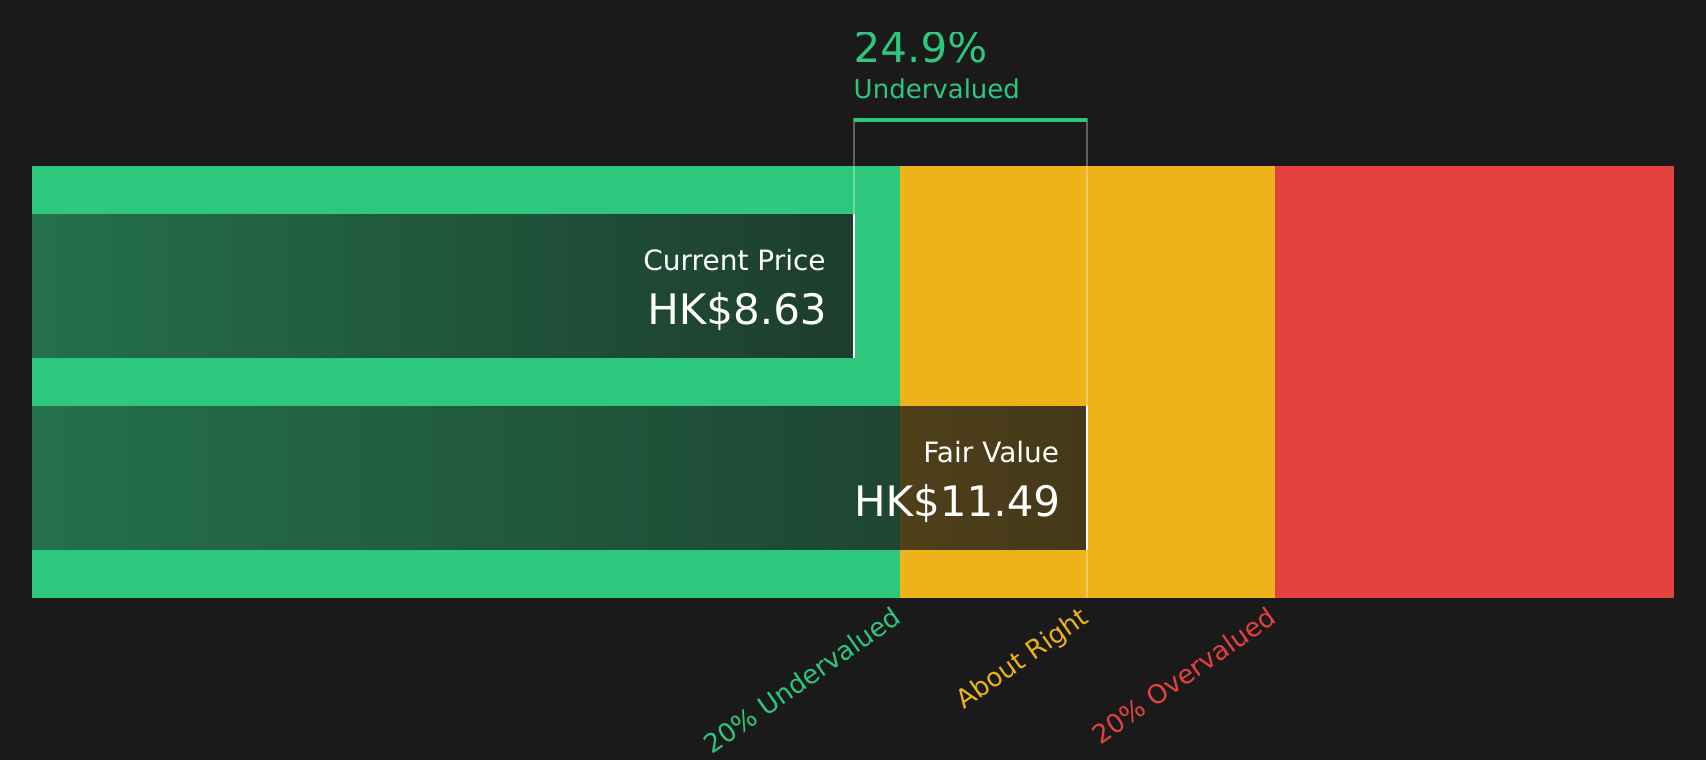
Overview: AEON Credit Service (Asia) operates in the financial services industry, providing insurance, credit card services, and personal loans, with a market capitalization of HK$3.52 billion.
Operations: The company's revenue primarily comes from credit cards and personal loans, with credit cards contributing the largest share. Over recent periods, the gross profit margin has consistently reached 100%, indicating that cost of goods sold is not impacting its profitability. Operating expenses are a significant part of its financial structure, including general and administrative expenses as well as sales and marketing costs. The net income margin has shown variability but remains robust at around 36% in recent data points.
PE: 7.7x
AEON Credit Service (Asia) showcases potential as an undervalued player in Asia's financial sector, with recent insider confidence demonstrated by Yuk Kwong Lai purchasing 10,000 shares for HK$86,800. Their net income climbed to HK$136 million for Q1 2026 from HK$109 million the previous year. Despite relying solely on external borrowing, the company is poised for growth with earnings projected to increase by 8.75% annually. Recent board changes may also influence strategic direction positively.
Where To Now?
- Reveal the 54 hidden gems among our Undervalued Asian Small Caps With Insider Buying screener with a single click here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com