
CECO Environmental (CECO) Could Be 28% Undervalued As Backlog Growth Supports Its Narrative
CECO Environmental (CECO) has drawn investor attention after recent trading left the stock around $78.34, with performance mixed across timeframes, as the price declined over the past month but remains higher year to date.
Recent moves suggest that momentum in CECO Environmental is pausing rather than breaking. The 1-day share price return of 3.91% and 7-day share price gain of 5.72% are offset by a 90-day share price decline of 17.55% and a stronger 1-year total shareholder return of 62.77%, which reflects earlier optimism now being reassessed.
Spot emerging momentum and under-the-radar peers to CECO Environmental by scanning our hand picked list of 15 high quality undiscovered gems.CECO Environmental now trades at a meaningful discount to both analyst targets and an estimated fair value, even after a strong 1 year run. Is that pricing in real risk, or caution that has gone too far?
Most Popular Narrative: 27.6% Undervalued
Against a last close of $78.34, the most followed narrative for CECO Environmental points to a fair value of $108.20, framing the current discount as a valuation gap that hinges on growth and margin assumptions playing out over time.
Record-high backlog and robust pipeline growth, especially in power generation, industrial water, and natural gas infrastructure, suggest that increasing global enforcement of environmental regulations is translating into sustained demand and forward visibility for CECO's solutions, supporting topline revenue growth over the next 18 to 24 months.
Want to see what kind of revenue ramp, profit margin lift, and future earnings multiple that fair value hinges on. The core of this CECO Environmental narrative is an ambitious growth runway, a step up in profitability, and a valuation framework that leans on those forecasts rather than today's loss making base. Curious which specific assumptions have to hold together for that $108.20 figure to make sense.
Result: Fair Value of $108.20 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the CECO Environmental story can wobble if Thermon integration stumbles or if higher leverage and growth spending weigh more heavily on earnings than analysts expect.
Find out about the key risks to this CECO Environmental narrative.
Another View: CECO Environmental Looks Expensive On Sales
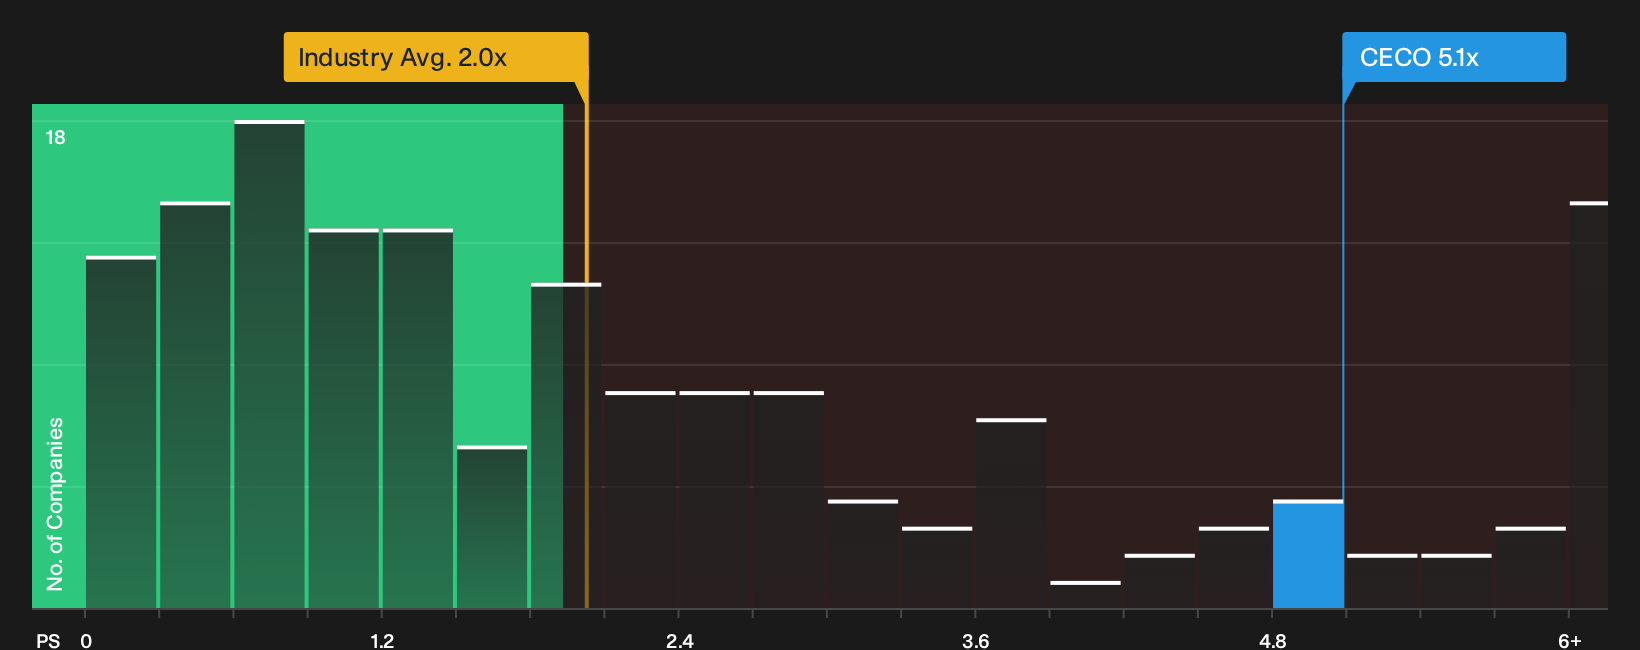
On the flip side of that fair value narrative, CECO Environmental screens as pricey when judged on its P/S ratio. The stock trades at 5.1x sales, compared with about 2x for the wider US Machinery group and 2.1x for peers, even though the fair ratio sits higher at 5.6x. That gap hints at less obvious upside on this metric and raises the question of how comfortable you are paying a premium today while waiting for the growth story to play through.
For a closer look at how this valuation stacks up against the wider market and what that could mean for future pricing power, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around CECO Environmental does not have to leave you on the fence. Take a closer look at both sides of the story with 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond CECO Environmental?
Do not stop your research with CECO Environmental. Broaden your watchlist with fresh opportunities that match different risk levels, income needs, and valuation profiles.
- Target potential bargains by focusing on quality businesses trading below what their fundamentals suggest using the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that aim to combine stability with meaningful payouts through the 6 dividend fortresses.
- Dial back risk while staying invested by screening for financially resilient businesses with the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com