
Saipem (BIT:SPM) Stock Trades At A Premium To Earnings After A 201% Return
Saipem stock has delivered a very strong 201.3% gain over the past three years, yet the broader valuation checks lean expensive and the recent share price drift over the past month and week suggests investors are starting to question how much optimism is already priced in.
- The 201.3% return over three years highlights how powerful the rebound in sentiment has been and raises the bar for future expectations to justify the current valuation.
- The new commissioning contract for the Osman Gazi floating production unit in Türkiye can support confidence in Saipem’s project pipeline, while execution risk on complex offshore work may weigh on how much investors are willing to pay for the shares.
- With a low value score of 2 out of 6 checks, the stock currently looks more like a rich proposition than a clear bargain on the usual valuation yardsticks.
The issue now is whether Saipem’s current price already reflects the recent contract wins and operational recovery, or if there is still room for further upside without stretching valuation metrics too far.
Broaden your watchlist beyond Saipem by scanning a curated set of infrastructure and energy enablers using 39 power grid technology and infrastructure stocks to see which projects the market may be rewarding more reasonably.
Does Saipem Look Pricey on Earnings?
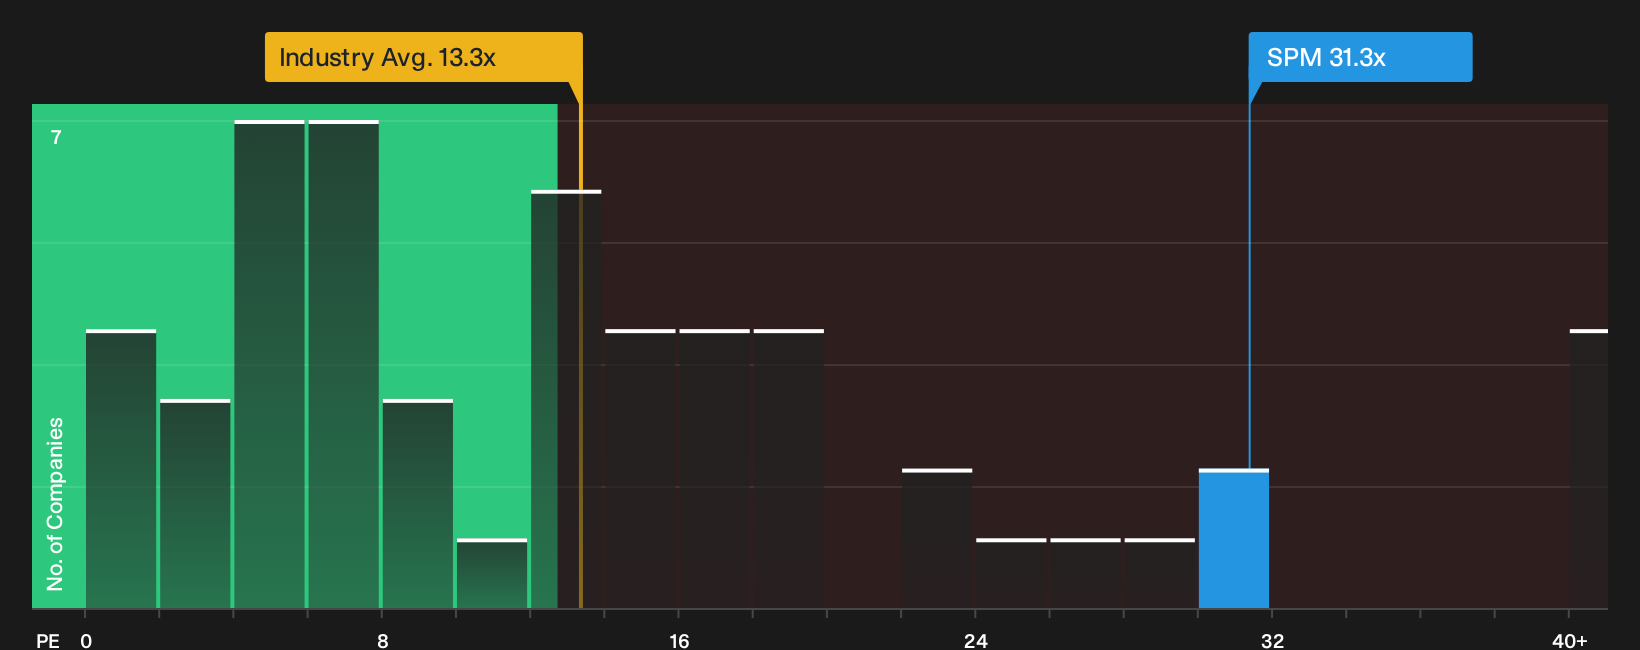
The P/E ratio is a useful yardstick for Saipem because it links the current share price directly to the earnings the engineering contractor is generating today. On this measure, the stock trades at about 31.3x earnings, which is almost double the Energy Services sector average of roughly 16.2x and well above the peer group average near 16.1x. That is a hefty premium for a business in a cyclical field where contract timing and project risk can both sway profitability.
The fair P/E multiple implied by the broader model is about 28.4x. Saipem therefore sits a few turns higher than what that framework suggests fits its size, margins and risk profile. Despite the fresh Osman Gazi commissioning work in Türkiye giving the story extra visibility, the current P/E still prices the shares at a relatively high level compared with typical industry and peer benchmarks.
On earnings multiples alone, Saipem stock currently appears expensive relative to these comparisons.
See what the numbers say about this price — find out in our valuation breakdown.
The Saipem Narrative: What Would Justify Today's Price?
Saipem’s valuation puzzle sets the stage for Simply Wall St Narratives. These narratives map out the specific paths on growth, profitability and earnings that would need to play out for the share price to look meaningfully higher or lower than it does today on the Community page.
Each narrative lays out its own set of assumptions about Saipem's fair value so you can compare those expectations with actual results as updates come through.
Saipem’s community view splits sharply, with one camp arguing the current price underestimates a stronger project mix while the other sees execution and transition risks crowding in.
Bull case: 28% undervalued
"Early leadership in CCUS, biorefining, and engineering services, along with landmark multi-billion euro wins, position Saipem for first-mover advantage and outsize margin expansion…"
Read the full Bull Case to see why Saipem could be undervalued
Bear case: 17% overvalued
"Saipem's legacy exposure to lump-sum turnkey contracts remains an overhang, having historically resulted in large cost overruns and portfolio-wide provisions…"
Read the full Bear Case to see why Saipem could be overvalued
Do you think there's more to the story for Saipem? Head over to our Community to see what others are saying!
The Bottom Line
Saipem now trades on earnings multiples that screen as overvalued compared with sector and peer benchmarks, so the valuation no longer looks obviously cheap. Without a supportive value score from broader checks, the burden of proof shifts to future project execution and contract quality rather than multiple expansion alone. The key debate from here is whether margins and risk control on complex workstreams can consistently match the optimism already implied by the current P/E.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com