
Humana (HUM) Declares Dividend, Is The Premium Already Priced In?
Humana (HUM) outlined new income terms after the Board of Directors declared a US$0.885 per share cash dividend, payable on November 27, 2026, to shareholders of record on October 30.
Humana shares have shown firm momentum recently, with a 1-month share price return of 5.33% and a year to date share price gain of 54.95%, while the 1-year total shareholder return is 50.38%, compared with a 3-year total shareholder return that declined 9.73%.
Scan how Humana's dividend news compares with other potential opportunities by reviewing a curated set of 6 dividend fortresses.
Bulls view Humana’s recent run and dividend as evidence that the business is on solid footing, while bears point to the weaker three-year record. Which side do the current valuation markers support?
Most Popular Narrative: 2.1% Undervalued
Humana's most followed valuation storyline pegs fair value at about $418.61, only modestly above the last close of $409.80. This keeps the focus on the assumptions behind that gap rather than a large pricing mismatch.
Growth in value-based models, particularly through the expansion of CenterWell and Medicaid services, is contributing to robust year-over-year patient and membership growth, indicating a potential increase in revenue.
Read the complete narrative. Read the complete narrative.
Want to understand why this relatively small discount still attracts attention? The narrative leans heavily on rising earnings, tighter cost control, and a richer profit mix from Medicare Advantage and CenterWell. It is worth examining which assumptions about future margins and member growth sit behind that fair value line and how they interact with a higher discount rate and valuation multiple.
Result: Fair Value of $418.61 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, Humana’s heavy reliance on Medicare Advantage Stars and its exposure to shifting reimbursement rules could quickly challenge that 2.1% undervalued narrative.
Find out about the key risks to this Humana narrative.
Another View: What Humana’s P/E Ratio Is Saying
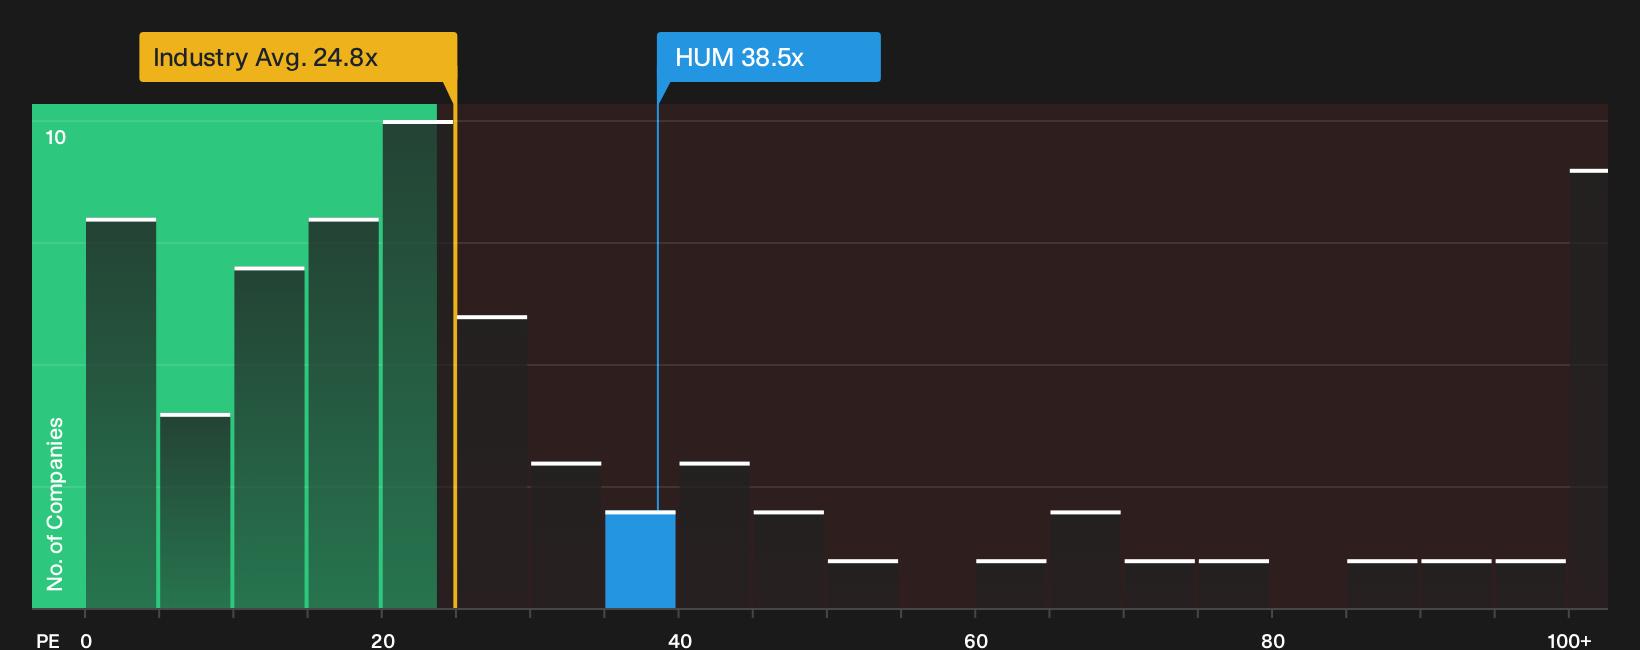
Humana might look modestly undervalued on that $418.61 fair value line, but the market is already pricing the stock at a P/E of 38.5x. That is richer than the US Healthcare sector on 24.8x and above peers at 25.7x, even if it still sits below a fair ratio of 46.6x.
Investors are therefore paying a premium multiple today. The fair ratio suggests there could be more room if earnings evolve as expected, which raises a simple question for anyone looking at HUM now: Is that premium a cushion or a risk if the story shifts?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Humana's premium and fair value can pull you in either direction, so consider acting while the data is fresh and stress test the story yourself by weighing its 2 key rewards and 2 important warning signs.
Looking for more Humana style investment ideas?
If Humana has you thinking about where to put fresh capital next, use this moment to widen your watchlist before the next wave of opportunities moves without you.
- Target resilient compounding potential by scanning a curated set of 32 high quality undervalued stocks that pair quality fundamentals with prices that still look reasonable.
- Prioritise strength and staying power by running through the list of solid balance sheet and fundamentals (23 results) so you are not caught off guard by weak finances.
- Spot off-the-radar potential by reviewing the 15 high quality undiscovered gems that many investors have not yet focused on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com