
Bandwidth (BAND) Stock Could Be Overvalued As AI Demand Builds
Bandwidth stock has delivered very strong multi year gains, yet the current market multiples and a low value score suggest the shares may already be pricing in a lot of optimism.
- A roughly 352.4% return over the past three years highlights how powerful the recent share price move has been for Bandwidth investors.
- Expectations for ongoing demand in communications APIs can support the current valuation. However, any setback in converting that revenue into sustainable cash flow may weigh heavily on the share price.
- The company screens as overvalued on broader checks, with a low value score that leans expensive rather than offering a clear bargain on fundamentals.
The issue now is whether Bandwidth's sharp rerating leaves enough upside to justify the current pricing on the stock.
Scan beyond Bandwidth's sharp rerating and compare it with 32 high quality undervalued stocks, which pairs stronger fundamentals with less stretch in its current pricing.
Does Bandwidth Look Pricey on Sales?
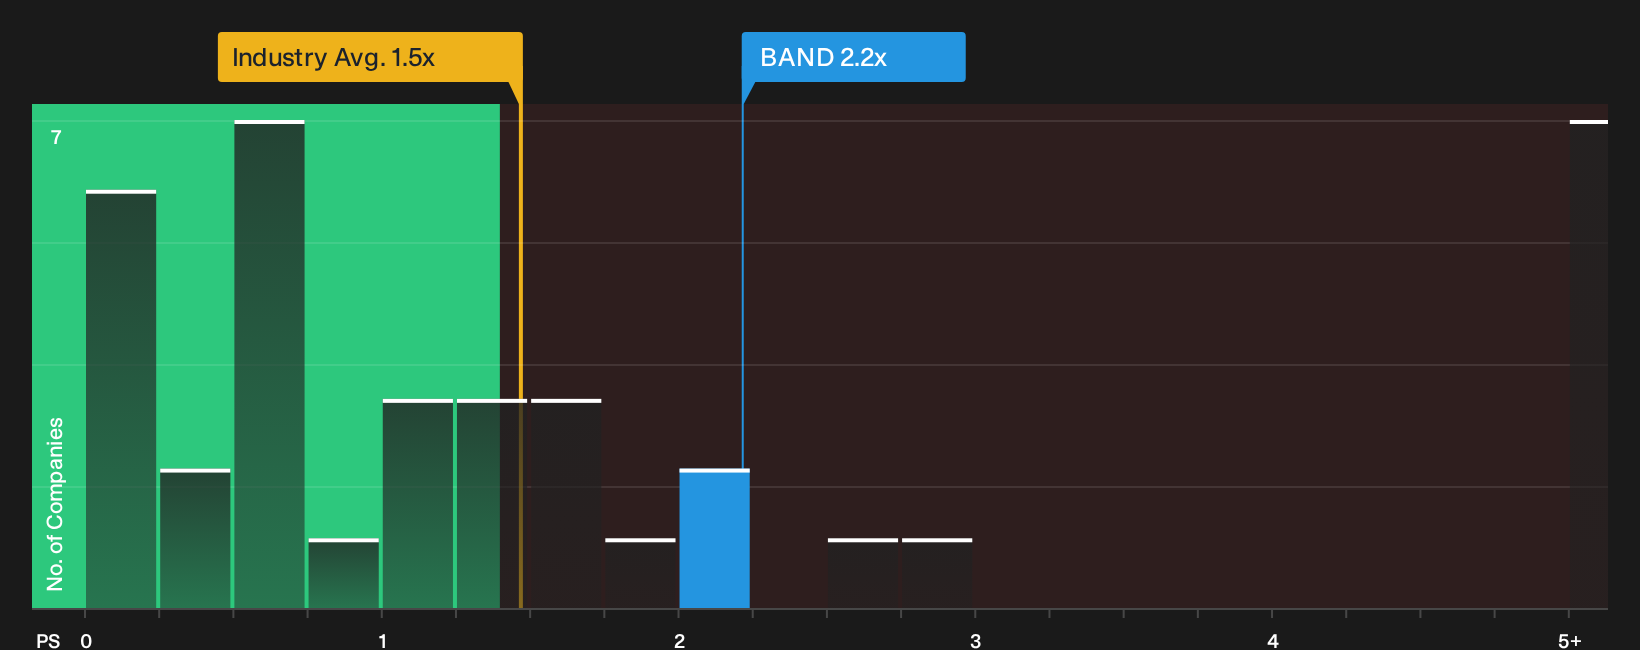
P/S tends to fit Bandwidth because the business is still heavily defined by top line scale rather than mature earnings. The stock trades at a P/S of 2.2x, almost exactly in line with the peer average of 2.2x and above the broader telecom industry at 1.5x. On simple comparisons, the market is already assigning Bandwidth a premium to the sector for each dollar of revenue.
The fair P/S ratio from the model comes in lower at 1.3x, which reflects the balance of Bandwidth’s risks, margins and growth profile. Against that yardstick, the current 2.2x multiple implies investors are paying a richer price for the same sales base than the model suggests is justified.
On this P/S framework, Bandwidth stock screens as overvalued, with the market paying a higher price for its revenue than the tailored benchmark implies.
See what the numbers say about this price — find out in our valuation breakdown.
The Bandwidth Narrative: What Would Justify Today's Price?
Bandwidth Narratives on Simply Wall St pick up where this valuation puzzle leaves off by spelling out which paths for revenue growth, profitability and earnings would make the stock look materially cheaper or more expensive than it does today. Each one links its number to a clear view on how Bandwidth's growth, margins and risk profile might evolve, which gives you something specific to revisit as fresh results and new information come through.
Community views on Bandwidth split sharply between AI driven upside and pressure from legacy products and heavier costs.
Bull case: 15% undervalued
"Accelerating enterprise adoption of AI-powered voice applications, driven by Bandwidth's Maestro platform and integrations, is already delivering a 3x-4x uplift in revenue per call for AI-enabled use cases..."
Read the full Bull Case to see why Bandwidth could be undervalued
Bear case: 9% overvalued
"Dependence on legacy communication APIs and large clients exposes Bandwidth to shrinking revenue and unpredictable recurring income as market shifts accelerate..."
Read the full Bear Case to see why Bandwidth could be overvalued
Do you think there's more to the story for Bandwidth? Head over to our Community to see what others are saying!
The Bottom Line
On the current multiples, Bandwidth looks overvalued, with the market already baking in a fairly optimistic set of outcomes for revenue quality and future margins. Broader valuation checks are weak, which means the burden of proof now sits with the business to translate its communications API position into steadier cash generation. The crux from here is whether Bandwidth can lift profitability enough to make today’s revenue based pricing feel conservative rather than exposed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com