
Cummins (CMI), Why Is The Story Around It Getting Harder To Ignore?
Cummins (CMI) has drawn fresh attention after its shares closed at US$556.75, with recent returns mixed across different time frames. Investors are weighing that price against value metrics such as revenue, profit and discount estimates.
Cummins has seen momentum cool in recent weeks, with the 30 day share price return down 11.8% and the 90 day share price return down 18.1%. At the same time, the year to date share price return is 6.7% and the 1 year total shareholder return is 37.7%, suggesting that recent weakness contrasts with stronger longer term gains that investors may now be reassessing against revenue, profit and discount metrics.
Scan beyond Cummins and compare this price reset with other value opportunities by reviewing the hand picked 32 high quality undervalued stocks that share strong cash flows and solid balance sheets.
Cummins looks like a solid industrial powerhouse on paper, while the recent pullback and sizable implied discount raise a sharper issue. Is this robust operation actually on sale or already fairly reflected in the current price?
Most Popular Narrative: 26% Undervalued
Cummins is priced at $556.75 while the most followed valuation storyline pegs fair value at about $748.81. The gap hinges on how durable its newer growth engines really are.
Cummins is experiencing strong and steadily growing demand for power generation equipment, especially from the data center sector, driven by increasing urbanization, digital infrastructure expansion, and the global shift toward cleaner, efficient energy solutions, this diversification is lifting revenue and supporting higher EBITDA margins, offsetting softness in the traditional truck markets.
See why 55 investors see Cummins as 26% undervalued.
Result: Fair Value of $748.81 (UNDERVALUED)
Still, Cummins depends heavily on cyclical truck demand. Any prolonged softness or regulatory delays could challenge the upbeat earnings and valuation narrative investors are leaning on.
Find out about the key risks to this Cummins narrative.
Another View on Cummins Valuation
The earlier story relies on analyst fair value and cash flow assumptions that present Cummins as roughly 23% below an estimated worth of $724.95 based on future cash flows. The market, though, is also sending a different signal through traditional earnings multiples.
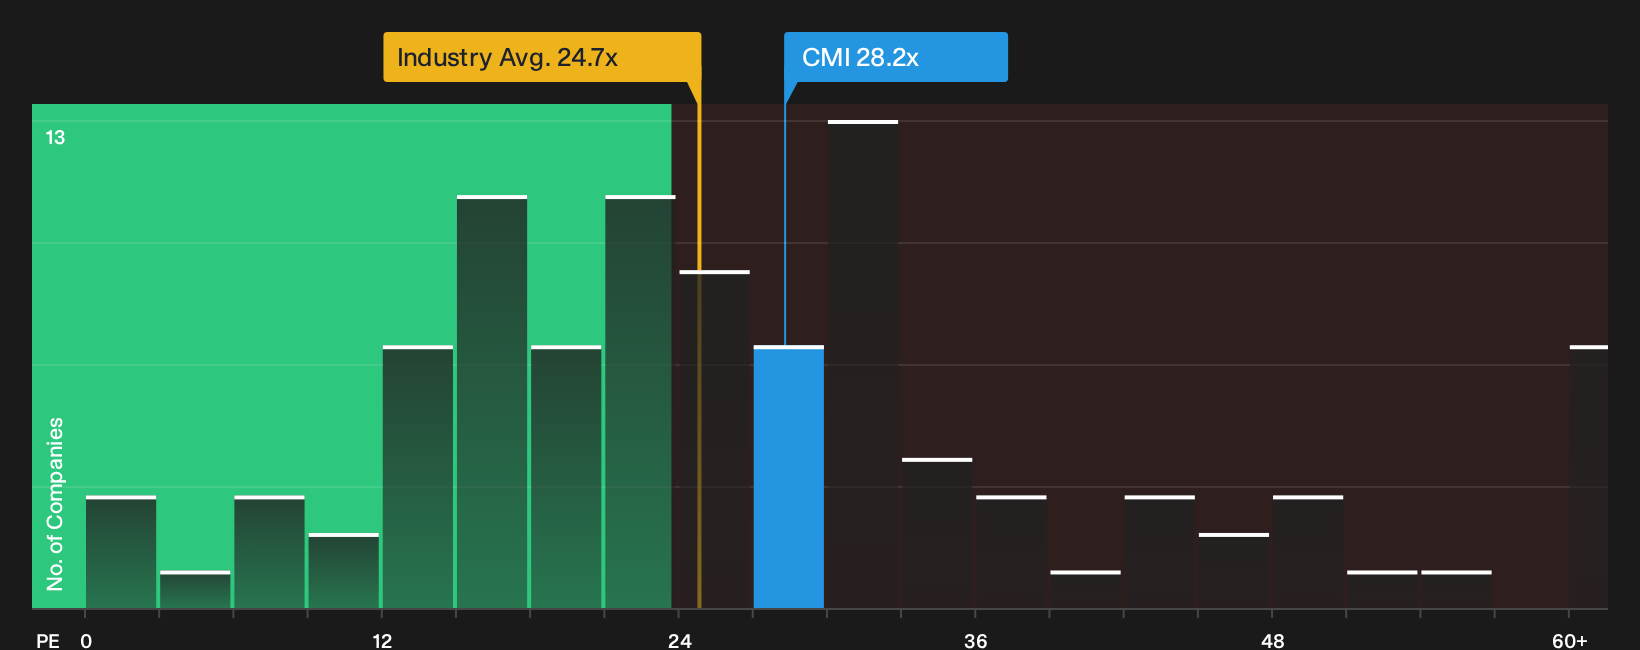
On a P/E of 28.2x, Cummins trades at a higher level than the broader US Machinery industry on 24.7x. Yet it still sits below an estimated fair ratio of 36.1x and slightly under a peer average of 29.5x. That mix of premium pricing and implied headroom leads to a simple question: is this a quality premium that remains in place, or a valuation that could compress if expectations ease?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this all sounds confident on Cummins, stress test it yourself before the crowd moves on, and weigh those potential upsides in the 4 key rewards.
Looking for more Cummins sized investment ideas?
You have dug into Cummins. Now widen the lens with a few focused stock lists that can surface fresh ideas before they move out of reach.
- Target resilient balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio core.
- Hunt for mispriced quality by reviewing a hand picked 15 high quality undiscovered gems that many investors have not fully priced in yet.
- Stack potential returns with ongoing income by checking a focused 6 dividend fortresses that highlights companies offering higher yields with support from their financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com