
Sabine Royalty Trust (SBR) Could Be 46% Below Fair Value Following Dividend Cut
Dividend cut and production drop put Sabine Royalty Trust in focus
Sabine Royalty Trust (SBR) moved into the spotlight after Argent Trust Company declared a lower cash distribution of $0.331680 per unit and reported weaker September oil and gas production.
For context, Sabine Royalty Trust units trade at $74.85, with a 30-day share price return of 2.67% and a 90-day gain of 4.31%, while longer term total shareholder return sits at 4.11% over one year and 184.18% over five years. This suggests near term momentum is steady, while the long term story has been materially positive, even as the latest dividend cut and production data prompt investors to reassess risk and income expectations.
Compare Sabine Royalty Trust’s latest setback with other income ideas by scanning hand picked 6 dividend fortresses that may better balance yield with recent payout and production trends.
After a softer payout and a sharp monthly production drop, Sabine Royalty Trust now asks a simple question of unitholders: Does the current price still offer enough upside potential to justify taking on this income risk?
Preferred P/E of 15.3x for Sabine Royalty Trust: Is it justified?
On valuation, Sabine Royalty Trust units closed at $74.85, which equates to a P/E of 15.3x that screens as more expensive than both its US Oil and Gas industry average of 13x and a peer group closer to 10x.
The P/E ratio compares the current unit price to trailing earnings per unit and helps you see how much investors are paying for each dollar of profit. For a royalty trust like Sabine Royalty Trust, where operations convert a large share of revenue into net income, that lens can be particularly useful because there is less reinvestment and more direct distribution of cash.
Here, the picture is mixed. On one side, Sabine Royalty Trust shows very high net profit margins of 94.7% and what is described as outstanding Return on Equity, which can help support a richer multiple if unitholders believe that earnings quality and capital efficiency offset recent dividend volatility and a weaker year of earnings. On the other side, the trust recorded a 3% decline in earnings over the past 12 months and an unstable dividend track record, while also underperforming both the broader US market and the Oil and Gas sector over the same period, which can make a premium valuation harder to justify for some income focused investors.
Compared with the sector, the 15.3x P/E for Sabine Royalty Trust sits well above the 13x industry average and clearly above the 10x peer group level described. This points to the units trading at a premium rather than a discount on this metric.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 15.3x (OVERVALUED)
Still, dividend instability and the recent earnings decline for Sabine Royalty Trust could pressure its premium P/E if income focused buyers reassess what they are willing to pay.
Find out about the key risks to this Sabine Royalty Trust narrative.
Another view on Sabine Royalty Trust’s value
The premium P/E suggests Sabine Royalty Trust is expensive, yet the SWS DCF model points in the opposite direction. At $74.85, units are described as trading about 45.8% below an estimate of future cash flow value of $138.05, which frames the same price as potentially discounted instead of rich.
Two methods, one price, very different messages. That kind of gap raises a simple question for anyone watching SBR. Which signal deserves more weight in your process, the earnings multiple or the cash flow model?
Look into how the SWS DCF model arrives at its fair value.
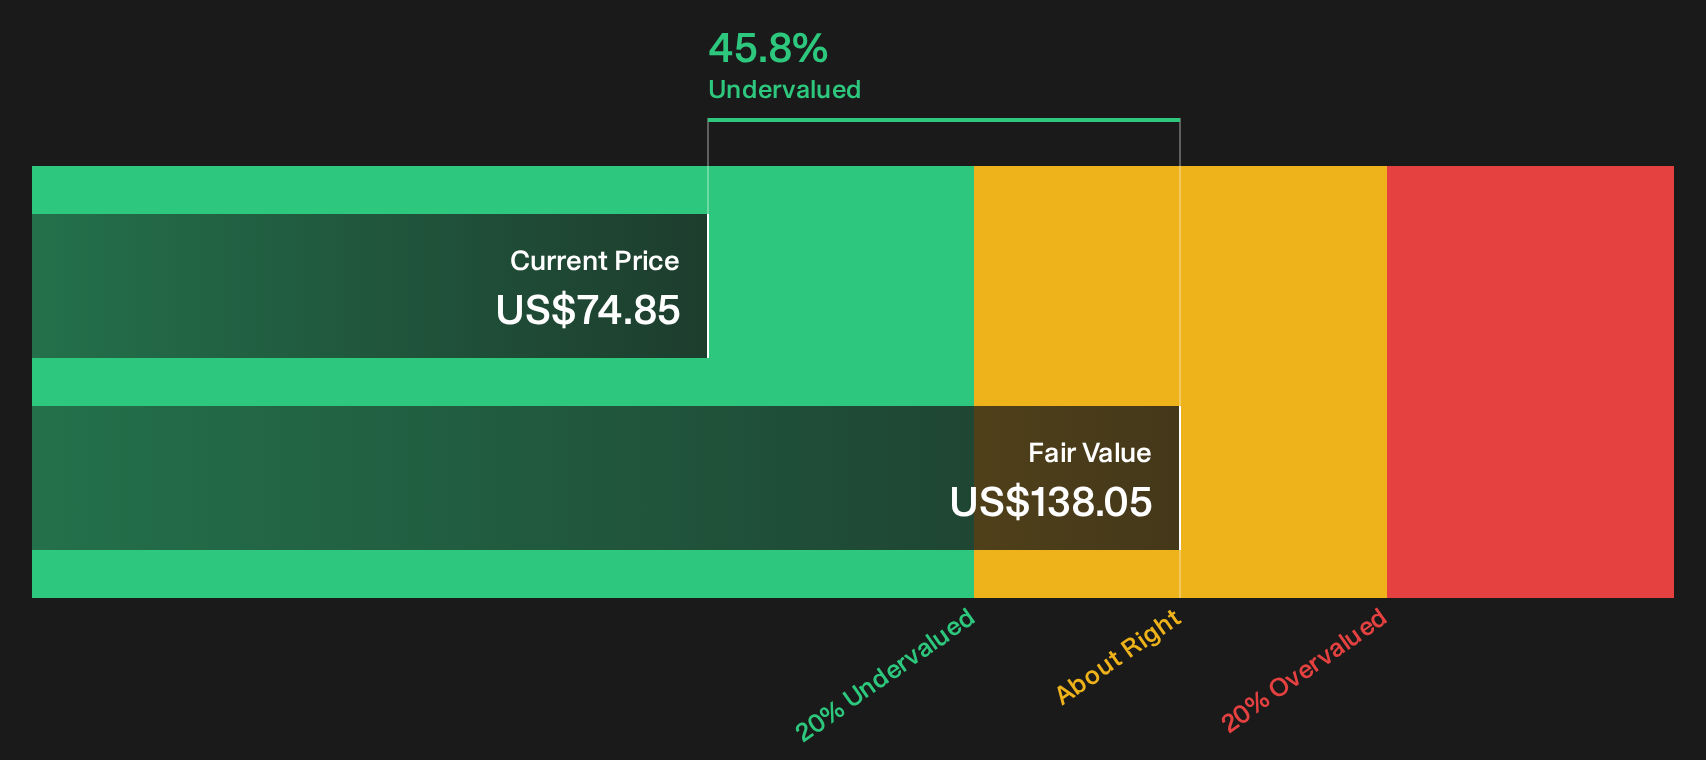
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sabine Royalty Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Sabine Royalty Trust’s income and valuation can feel uncomfortable, so treat this as a prompt to check the numbers yourself and decide where you land. To balance what could go right with what might go wrong, start by weighing the 1 key reward and 1 important warning sign.
Looking for more Sabine Royalty Trust sized investment ideas?
If Sabine Royalty Trust leaves you uncertain, use that as a signal to widen your opportunity set and pressure test your income and valuation checklist elsewhere.
- Target resilient balance sheets and steadier fundamentals by scanning a list of solid balance sheet and fundamentals (23 results) that can help you stress test your downside protection.
- Hunt for potential mispriced opportunities by reviewing a focused 32 high quality undervalued stocks that can sharpen your sense of what you are paying for each dollar of fundamentals.
- Strengthen your income watchlist by comparing Sabine Royalty Trust with a curated 15 high quality undiscovered gems that may reveal income and quality combinations you have not considered yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com