
Learn Why The Bull Case For Viking Holdings (VIK) Could Change Following Hydrogen Ship Float Out
- Viking Holdings reported that the Viking Astrea, its second hydrogen-powered cruise ship capable of zero-emissions operation, was floated out at Fincantieri’s Ancona Shipyard, moving into final construction before an expected May 2027 delivery for Mediterranean and Northern Europe itineraries.
- The combination of hydrogen and fuel cell propulsion on a 54,300-ton small ship, alongside a newly authorized US$1,000 million share repurchase program, highlights how Viking Holdings is pairing capital return with large, sustainability-focused fleet investment.
- This development raises questions about how Viking Holdings' push into hydrogen-powered cruising could influence its investment narrative around growth, risk, and capital allocation.
Scan beyond Viking Holdings and compare this hydrogen push with other travel and infrastructure plays on our curated list of list of solid balance sheet and fundamentals (23 results).
Viking Holdings Investment Narrative Recap
Viking Holdings appeals to investors who believe premium cruising can keep drawing affluent travelers and that the firm can keep filling a growing fleet at solid pricing. The hydrogen projects fit into that thesis as a long build cycle on cleaner vessels, but they do not reshape the near term demand story. That still hinges on sustaining current booking strength.
The biggest near term swing factor remains execution on capacity expansion without letting costs and debt pressure earnings. Hydrogen powered ships like Viking Astrea add long lived assets but also sizeable capital needs. The key risk is that higher capex and financing costs could outpace profitability if demand or pricing softens.
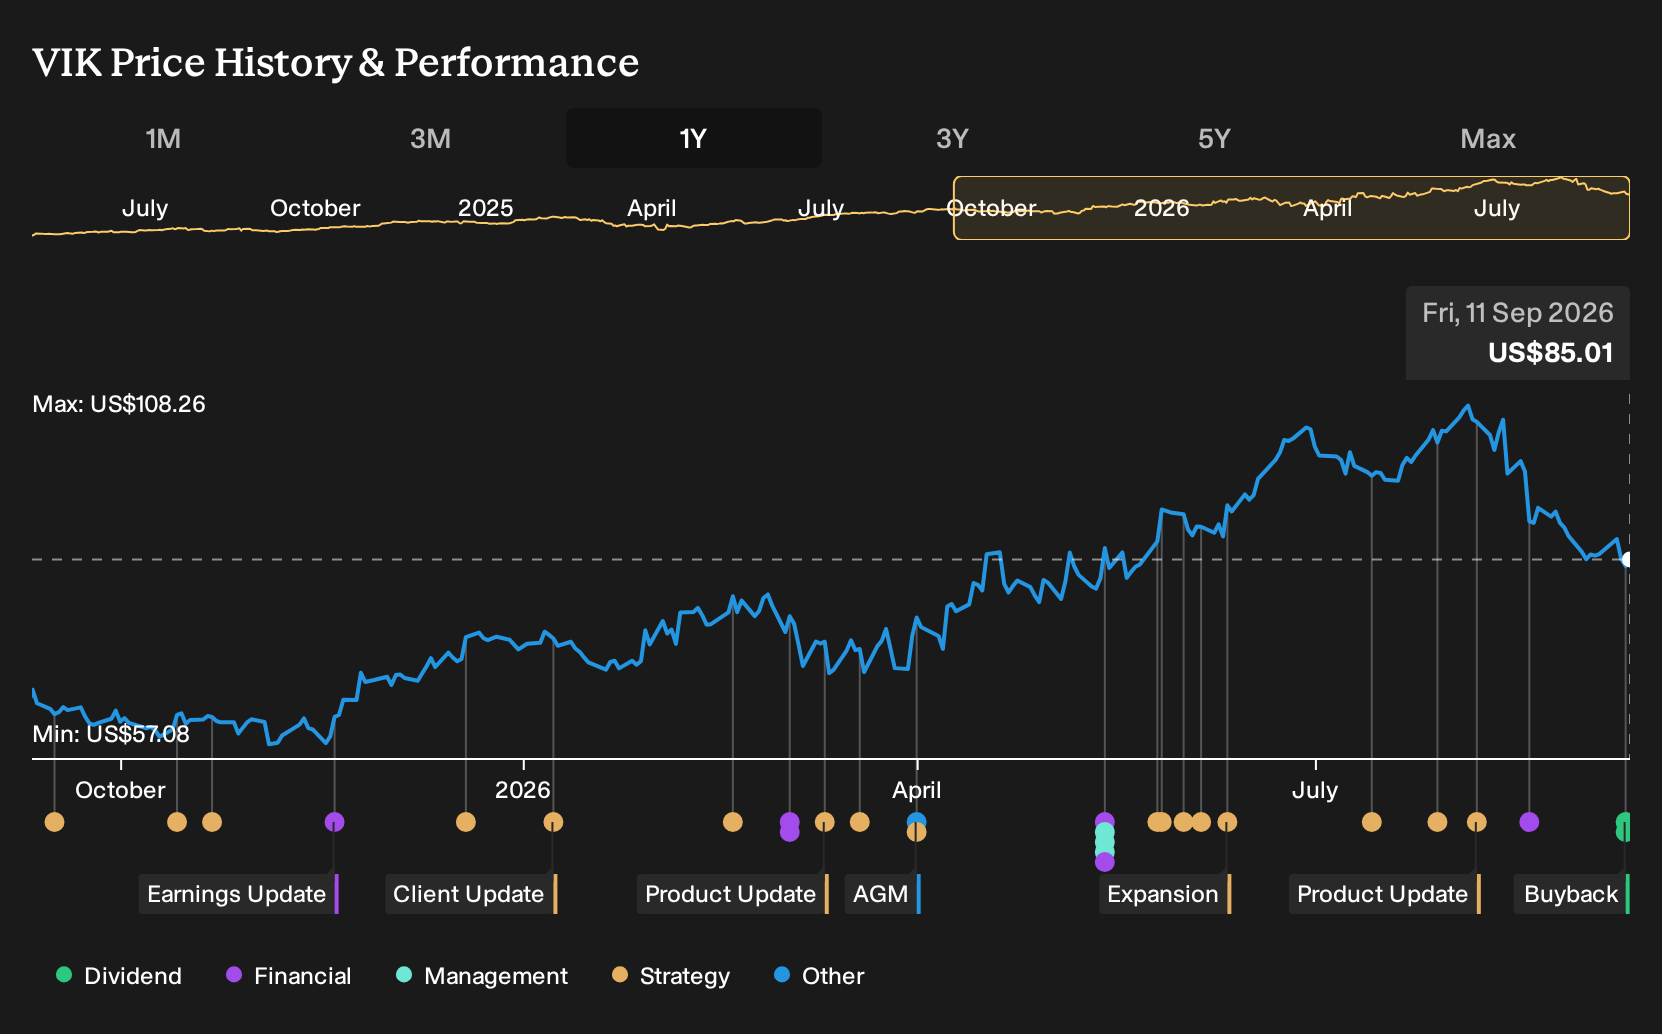
The US$1,000 million share repurchase authorization is the clearest complementary signal alongside the hydrogen fleet build. It links Viking Holdings’ capital return directly to an already heavy investment program, so investors are effectively judging whether cash flows can support both shipbuilding and buybacks without stretching the balance sheet.
For catalysts, that buyback can matter if it is paired with continued earnings growth and disciplined leverage, because it may offset dilution and support per share metrics. If operating trends or booking momentum were to weaken, an aggressive repurchase plan could instead magnify the impact of any existing debt and make funding future vessels more sensitive.
Viking Holdings' current narrative assumes revenue reaches US$10.4b and earnings climb to US$2.4b by 2029, based on 16.1% yearly top line growth and an earnings increase of about US$1.2b from US$1.2b today.
Uncover why Viking Holdings' fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean into Viking Holdings’ capacity expansion as the real catalyst, not the hydrogen news itself. Before this float out, the bullish camp was already penciling in about US$10.9b of revenue and US$2.8b of earnings by 2029. You can treat those numbers as one end of a wide opinion range that may shift as the zero emissions ships progress.
Explore 4 other Viking Holdings fair value estimates, including one that suggests there could be as much as 81% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Viking Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Viking Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Viking Holdings' overall financial health at a glance.
Looking For More Viking Holdings Style Investment Ideas?
Viking Holdings may already be on your radar, but you do not need to stop with a single cruise operator when there are entire groups of stocks that share similar financial qualities.
- Prefer strong finances and resilient balance sheets? Use the Simply Wall St screener to filter for a list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions without relying heavily on fresh capital.
- Interested in finding companies that trade below their assessed worth based on fundamentals? Scan through a focused list of 32 high quality undervalued stocks and compare how their risk and reward profiles stack up against Viking Holdings.
- Looking for potential early stage opportunities with room to mature? Review a curated pool of 21 elite penny stocks with strong financials where you can weigh smaller market capitalizations against their financial strength and business models.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com