
European Value Stocks Priced Below Estimated Worth In September 2026
European markets have recently experienced downward pressure, with the pan-European STOXX Europe 600 Index dropping by 1.66% amid rising inflation concerns driven by higher oil and natural gas prices. As the European Central Bank raises interest rates to combat persistent inflation risks, investors are increasingly looking for stocks that may be undervalued in this challenging economic environment. Identifying stocks priced below their estimated worth can be a strategic approach for investors seeking value opportunities amidst these market conditions.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Verkkokauppa.com Oyj (HLSE:VERK) | €3.495 | €5.76 | 39.3% |
| Sulzer (SWX:SUN) | CHF149.30 | CHF287.79 | 48.1% |
| Promotica (BIT:PMT) | €3.06 | €5.82 | 47.4% |
| Marimekko Oyj (HLSE:MEKKO) | €9.20 | €16.78 | 45.2% |
| KSB SE KGaA (XTRA:KSB) | €936.00 | €1757.85 | 46.8% |
| Kalmar Oyj (HLSE:KALMAR) | €39.84 | €65.62 | 39.3% |
| Frequentis (XTRA:FQT) | €66.60 | €114.47 | 41.8% |
| Embla Medical hf (CPSE:EMBLA) | DKK27.15 | DKK46.19 | 41.2% |
| Boliden (OM:BOL) | SEK550.00 | SEK1016.71 | 45.9% |
| Apator (WSE:APT) | PLN26.20 | PLN49.03 | 46.6% |
Let's review some notable picks from our screened stocks.
Embla Medical hf (CPSE:EMBLA)
Overview: Embla Medical hf, along with its subsidiaries, offers non-invasive orthopedic products across Europe, the Middle East, Africa, the Americas, and the Asia-Pacific regions, with a market capitalization of DKK11.55 billion.
Operations: The company's revenue is primarily derived from Prosthetics & Neuro Orthotics ($563.40 million), Patient Care ($311.15 million), and Bracing and Supports, including Compression Therapy (Phlebology) ($151.33 million).
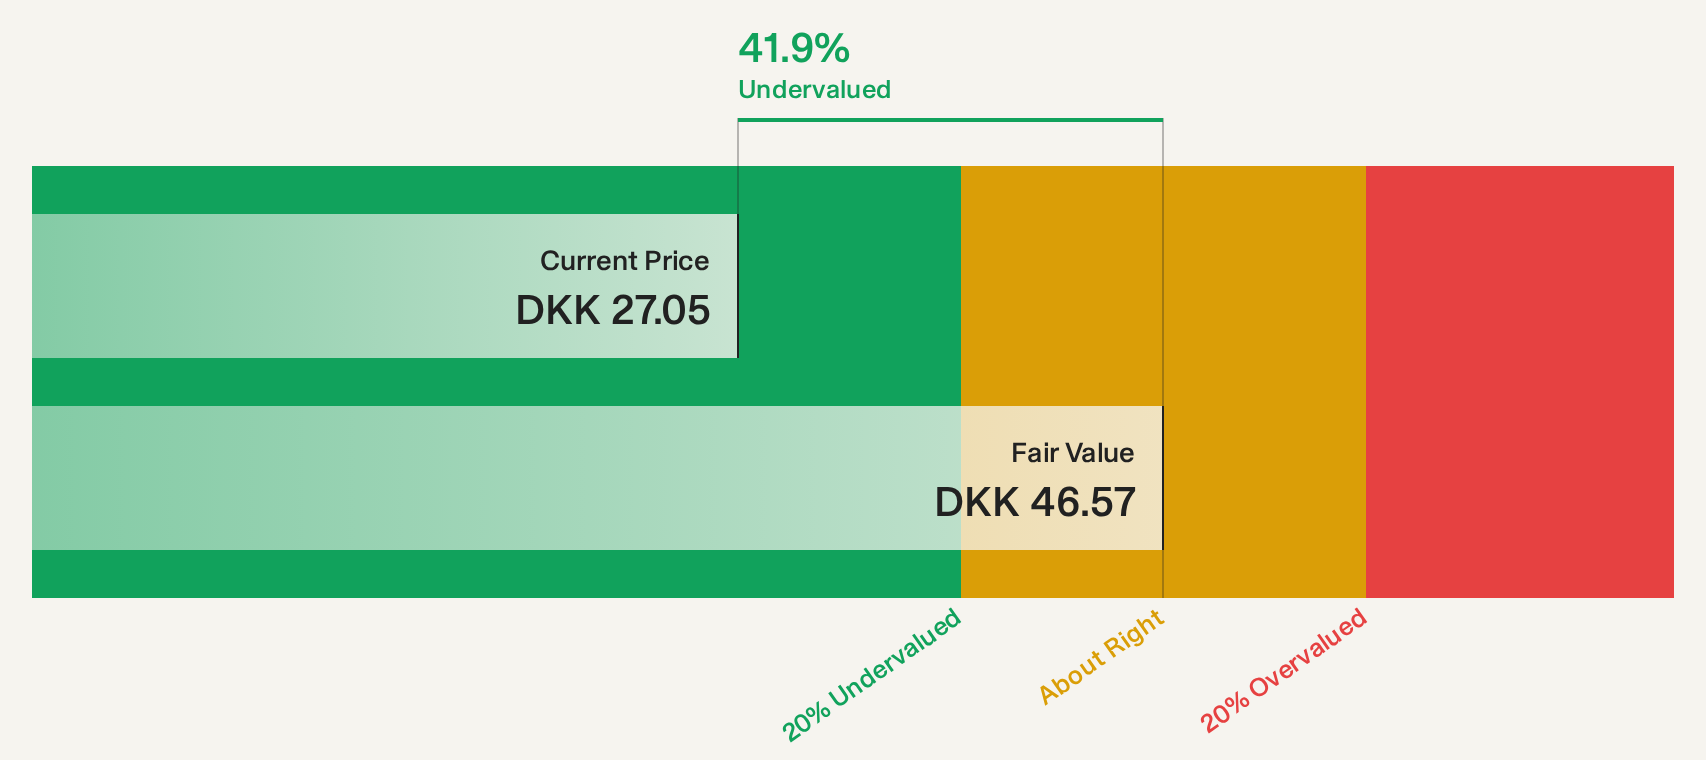
Estimated Discount To Fair Value: 41.2%
Embla Medical hf. is trading at DKK27.15, significantly below its estimated future cash flow value of DKK46.19, indicating it is undervalued based on cash flows by over 20%. Despite a forecasted low return on equity of 11%, earnings are projected to grow at 12.8% annually, outpacing the Danish market's growth rate. Recent share repurchase programs aim to optimize capital structure and enhance shareholder value, further supporting its undervaluation thesis amidst solid revenue growth projections.
- In light of our recent growth report, it seems possible that Embla Medical hf's financial performance will exceed current levels.
- Dive into the specifics of Embla Medical hf here with our thorough financial health report.
Vetoquinol (ENXTPA:VETO)
Overview: Vetoquinol SA is a veterinary pharmaceutical company that designs, develops, and sells veterinary drugs and non-medicinal products for cattle, pigs, dogs, and cats across Europe, the Americas, and the Asia Pacific region with a market cap of €899.55 million.
Operations: The company's revenue primarily comes from its Animal Health segment, which generated €527.39 million.
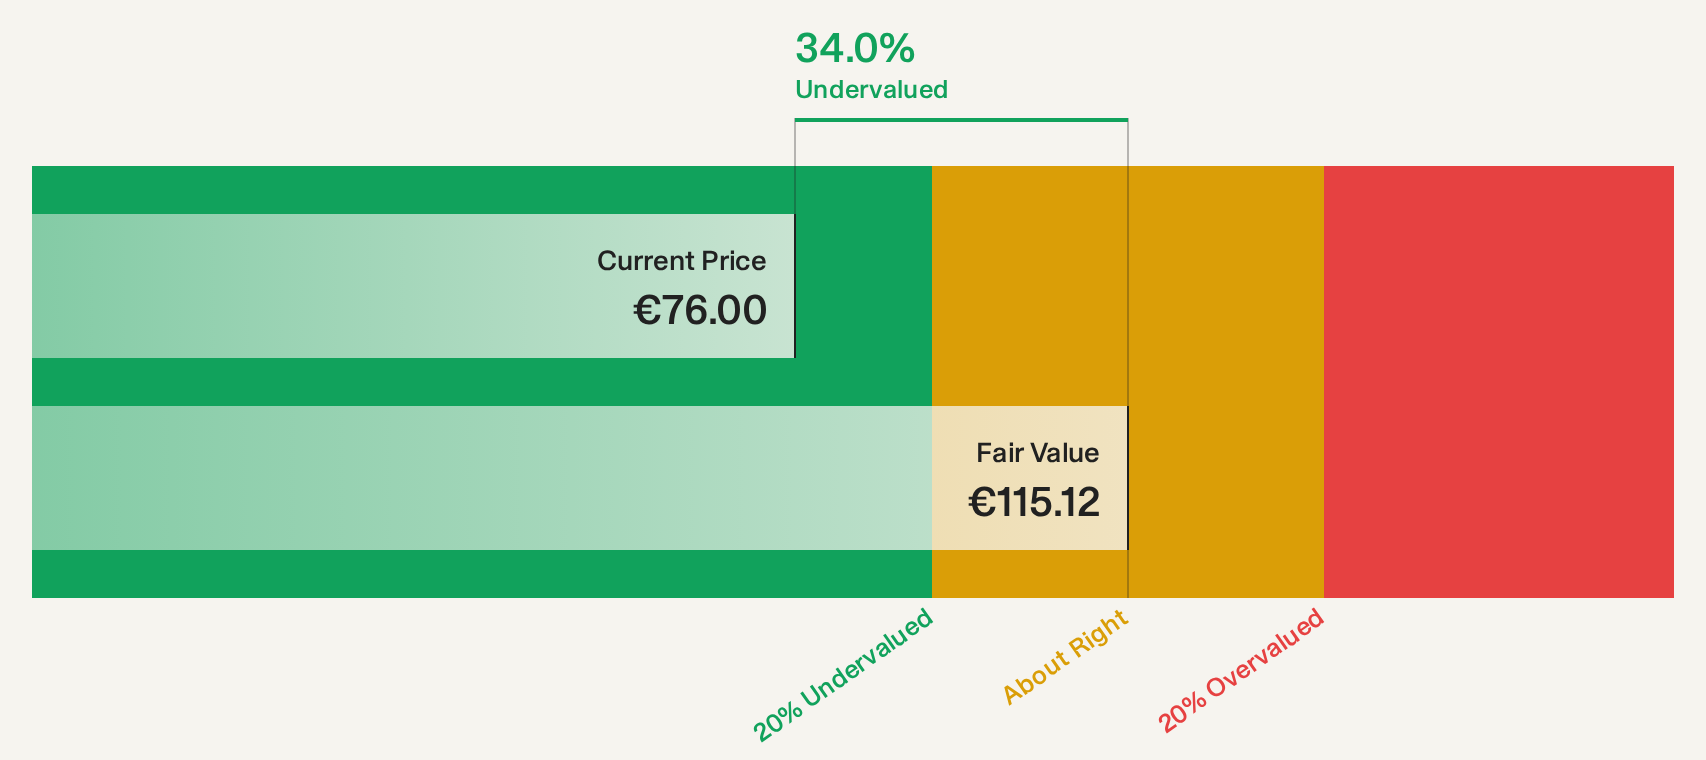
Estimated Discount To Fair Value: 33.2%
Vetoquinol is trading at €77.4, below its estimated future cash flow value of €115.8, highlighting its undervaluation based on cash flows by over 20%. Despite a low forecasted return on equity of 9.1% and slower revenue growth compared to the French market, recent earnings for the half-year ending June 2026 showed an increase in net income to €30.5 million from €25.1 million the previous year, underscoring potential value amidst modest growth prospects.
- Our earnings growth report unveils the potential for significant increases in Vetoquinol's future results.
- Click here and access our complete balance sheet health report to understand the dynamics of Vetoquinol.
Frequentis (XTRA:FQT)
Overview: Frequentis AG develops and markets communication and information systems for safety-critical control centers globally, with a market cap of €884.11 million.
Operations: The company's revenue is primarily derived from its Air Traffic Management segment, which accounts for €499.05 million, and the Public Safety & Transport segment, contributing €187.77 million.
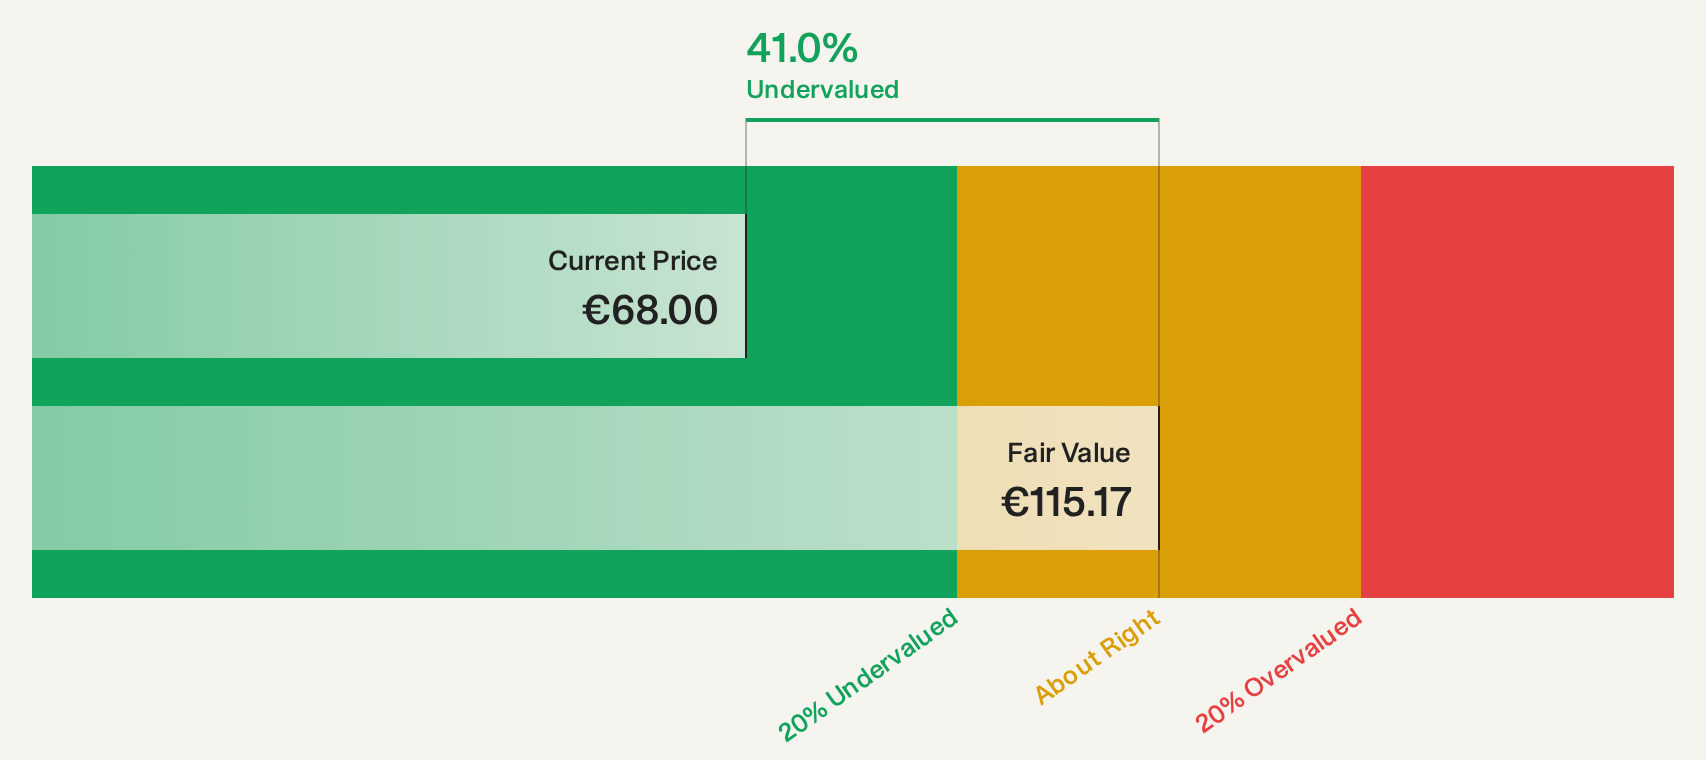
Estimated Discount To Fair Value: 41.8%
Frequentis is trading at €66.6, significantly below its estimated future cash flow value of €114.47, indicating substantial undervaluation based on cash flows by more than 20%. Despite a forecasted low return on equity of 14.4% in three years and slower earnings growth compared to the German market, recent half-year results showed a turnaround with net income reaching €11.27 million from a prior loss, reinforcing its potential amidst moderate growth expectations.
- Our comprehensive growth report raises the possibility that Frequentis is poised for substantial financial growth.
- Take a closer look at Frequentis' balance sheet health here in our report.
Summing It All Up
- Unlock our comprehensive list of 20 Undervalued European Stocks Based On Cash Flows by clicking here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com