
How Investors May Respond To PTC (PTC) Analyst Backing For Software Strength
- PTC was recently profiled as a favored software provider, with reports highlighting its efficient business model, strong operating margins, and relatively low servicing costs that support rapid customer onboarding.
- The coverage drew attention to how PTC's software functionality and fast payback periods on sales and marketing spend underpin its ability to add recurring customers at scale.
- We will look at how PTC's investment narrative around recurring software strength is affected by this focus on efficient customer onboarding.
Scan beyond PTC to compare its efficient recurring revenue profile with other software firms by reviewing the hand picked 15 high quality undiscovered gems list.
PTC Investment Narrative Recap
To own PTC, you need to believe its efficient recurring software model, with high margins and fast payback on sales spend, can stay resilient even as subscription and SaaS timing effects create bumps in reported earnings. The recent focus on its low servicing costs reinforces that thesis and supports the idea that operating leverage can still matter in the near term.
The key short-term swing factor is how cleanly PTC manages the shift in mix toward SaaS while keeping churn in areas like ServiceMax contained. The biggest risk remains that slower customer budgets or integration issues blunt ARR momentum. The latest news on onboarding efficiency does not materially change that risk profile.
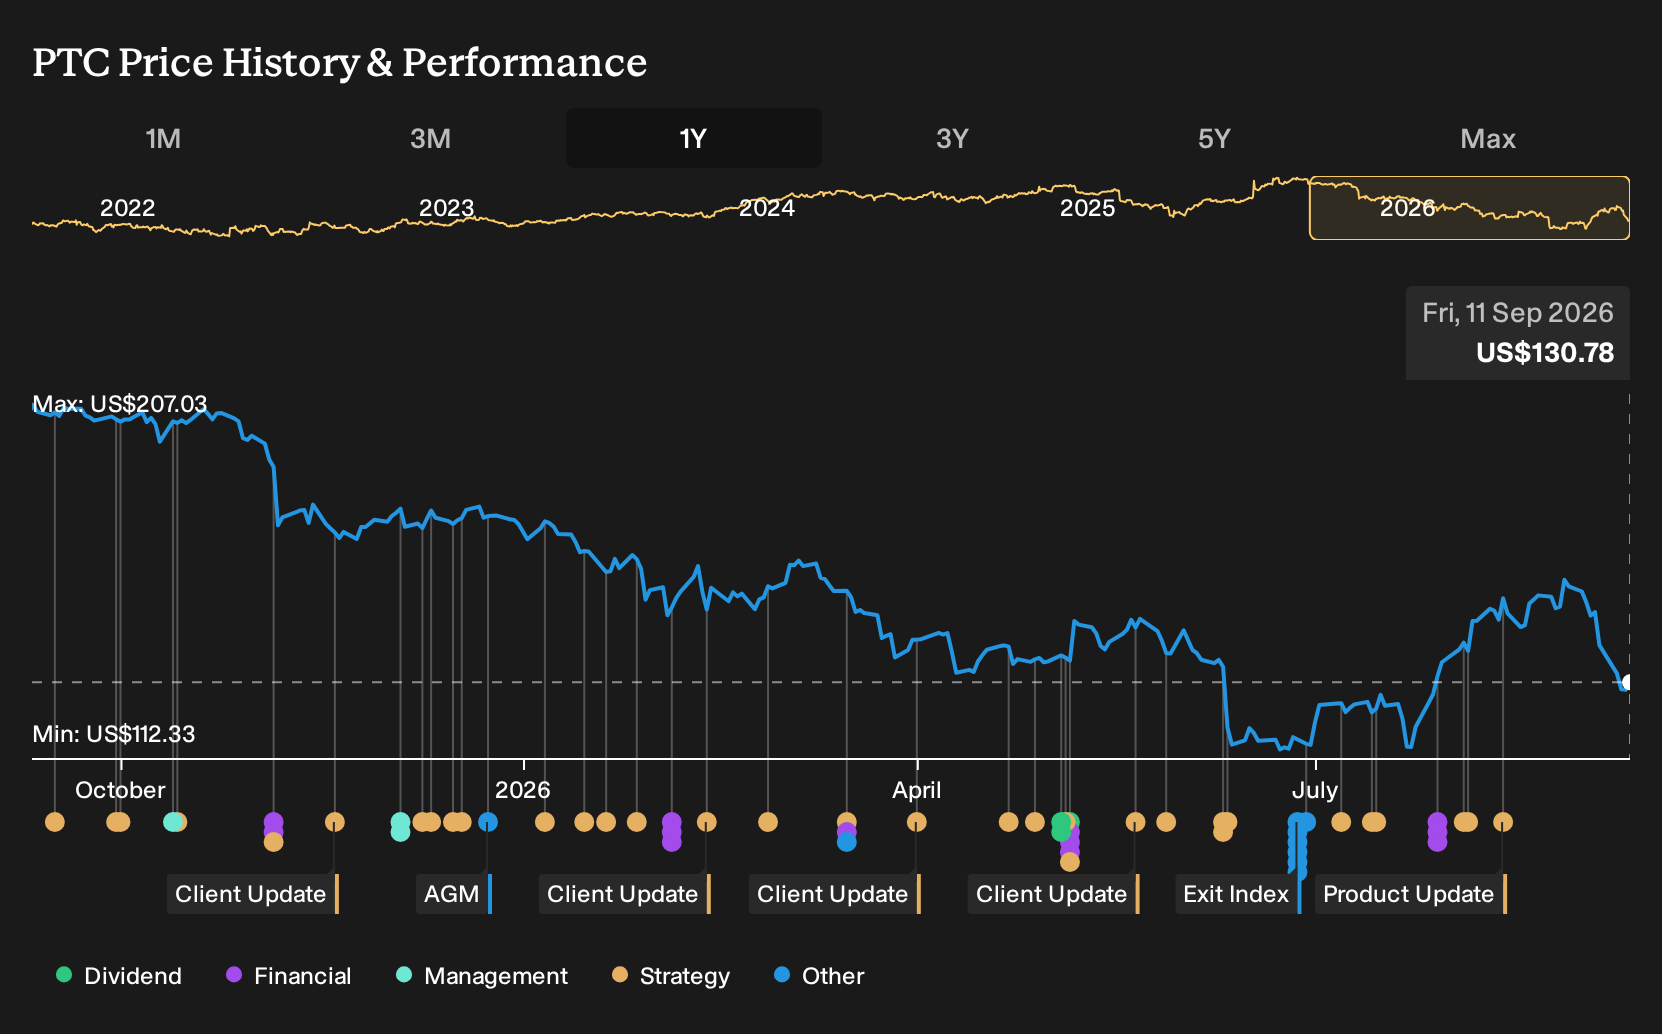
Recent commentary that PTC trades on a forward P/S multiple some investors view as reasonable, given its margin profile and software functionality, ties directly into this efficiency story. The market is being asked to pay for a business that converts sales and marketing spend into recurring users quickly, with a track record of high operating margins and strong net profit levels.
For shareholders, the operational question is whether that efficient engine can keep working as the firm leans further into AI-driven tools such as Creo 12 and Arena Supply Chain Intelligence, while managing foreign exchange exposure and competitive pressure from larger peers. Those product trends sit alongside the recurring revenue model as the main factors investors are watching in relation to the earnings decline forecasts that analysts have laid out.
PTC's current earnings are $1.2b, with analysts forecasting revenue growth of 4.1% per year and projecting 2029 revenues of $3.3b and earnings of $904.2m. This view implies an earnings decline of about $295.8m from today to the 2029 consensus, all tied to that same 2029 forecast horizon.
Uncover why PTC's fair value indicates a 33% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Some of the most optimistic analysts frame PTC’s AI tooling as the real swing factor, not just efficient onboarding. Before this news, that group was still pencilling in 2029 revenues of about $3.3b and earnings near $809.2m, while expecting a much higher 36.7x P/E. That gap shows how widely views can differ, so explore multiple narratives before deciding what this update might change.
Explore 6 other PTC fair value estimates, including one that suggests as much as 172% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PTC research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PTC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PTC's overall financial health at a glance.
Looking for more investment ideas beyond PTC?
Once the PTC story is clear in your mind, it can help to widen the lens and line it up against companies with very different risk and return profiles using the Simply Wall St Screener.
- If you want a starting point for potential mispriced opportunities with solid fundamentals, scan through the 32 high quality undervalued stocks that currently pass our filters.
- For readers who care most about balance sheet strength and financial resilience, work through the list of solid balance sheet and fundamentals (23 results) to see which businesses match that profile.
- Income focused investors can anchor their watchlist by reviewing the 6 dividend fortresses that combine higher yields with detailed payout data.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com