
New Data Center Tools Might Change The Case For Investing In Keysight Technologies (KEYS)
- In early September 2026, Keysight Technologies showcased new tools for high speed optical and AI infrastructure in next generation data centers, covering photonic design, 1.6T validation, AI workload testing, and AI enabled test automation aimed at shortening development and production cycles.
- The product suite directly targets real world bottlenecks in data center design and manufacturing by linking photonic simulation, automated chip testing, and AI driven analytics to reduce engineering uncertainty and test time.
- The following section examines how Keysight Technologies' investment narrative could be affected by its push into AI enabled high speed data center testing.
Keysight Technologies Investment Narrative Recap
To own Keysight Technologies, you need to believe in sustained demand for testing across AI infrastructure, high speed optical links, next generation wireless, and software centric tools. The recent data center announcement fits that story because it focuses squarely on AI workloads and 1.6T optical validation, which aligns with AI driven catalysts already in play.
In the near term, the swing factor still looks like how AI related orders and tariff driven cost pressure balance out in actual margins. The September product news does not change the biggest risk right now. Tariffs, supply chain changes, and any cooling in AI infrastructure spending could still pressure earnings and expose Keysight Technologies to more volatile demand.
The most relevant recent update for this story is the collaboration with the Centre for Assuring Autonomy at the University of York. Keysight Technologies is working on methods to validate AI in software defined vehicles and generate auditable safety evidence, which ties into its broader push into AI testing and software tools.
This research effort connects directly to the catalyst of growing software and recurring services. It feeds into products such as AI Software Integrity Builder and touches a slower end market such as automotive that management has flagged as challenging. Execution risk sits in turning this research into widely adopted tools that can help offset cyclicality in AI data center hardware demand.
Keysight Technologies' current earnings are about US$1.3b, with analysts forecasting revenues of US$10.4b and earnings of US$2.8b by 2029. That path implies 16.5% yearly revenue growth and about a 2.2x increase in earnings from today to the 2029 consensus estimate.
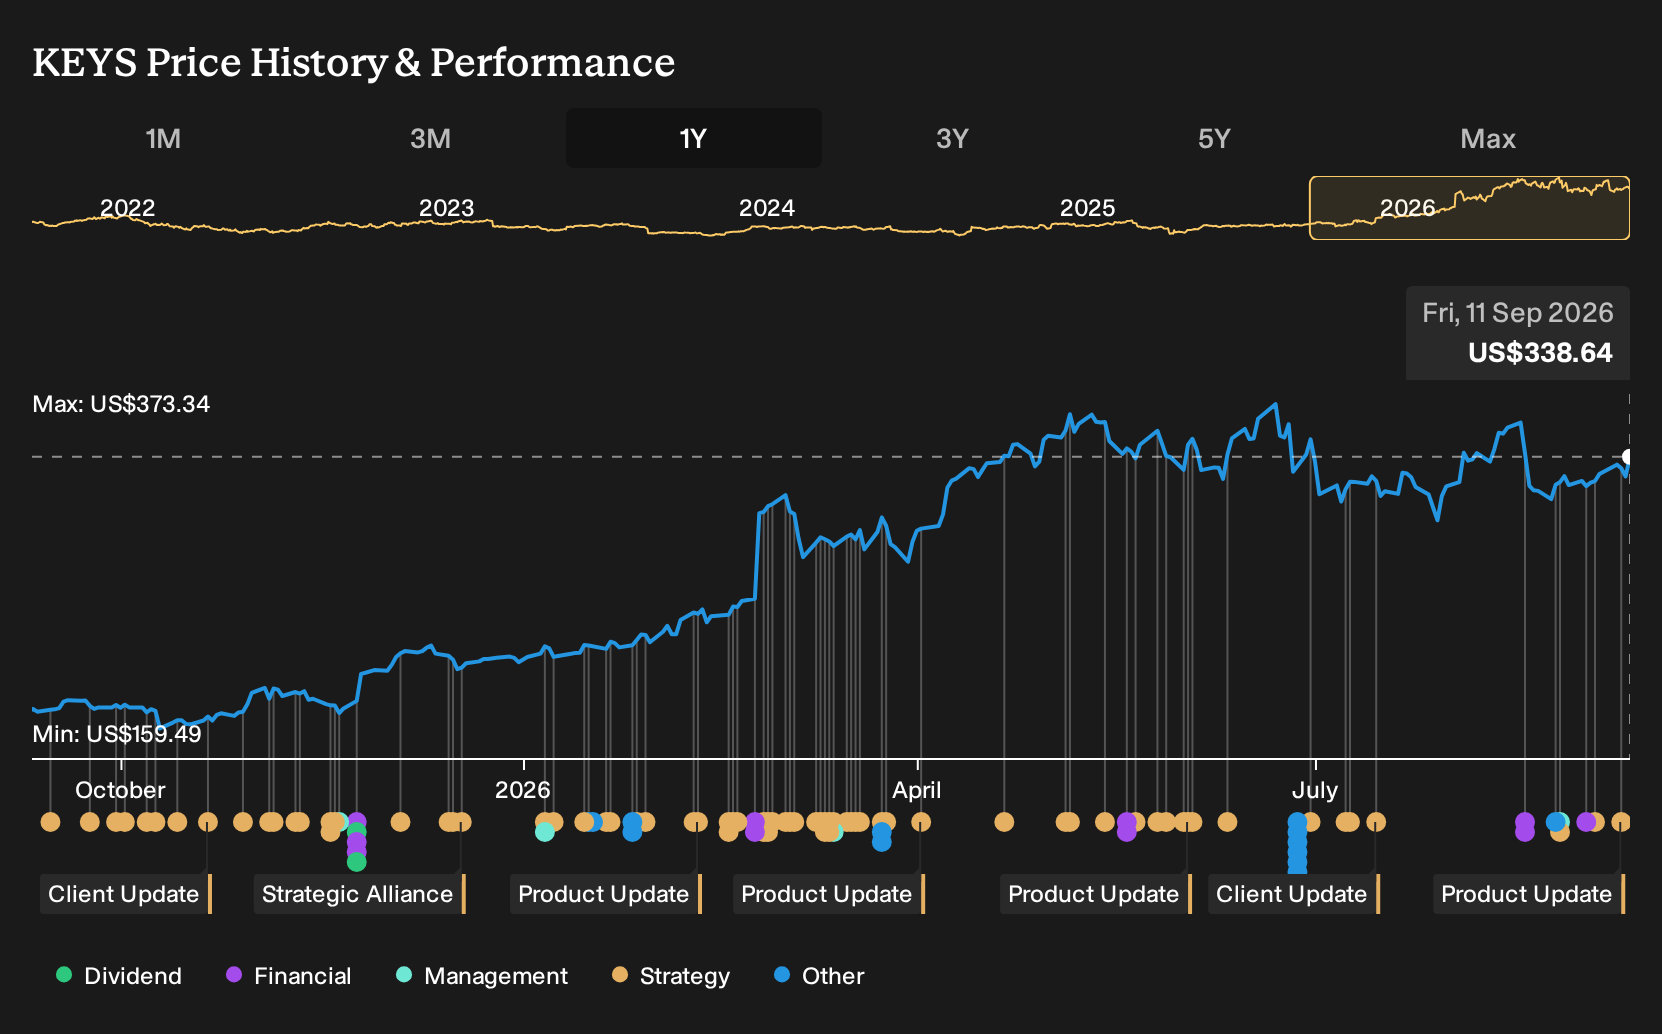
Uncover how Keysight Technologies' fair value indicates a 23% potential upside to its current price. This gap could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view on Keysight Technologies focuses on AI test demand concentration risk. The most cautious analysts already baked in slower growth, with revenues modeled at about US$9.2b and earnings at US$2.7b by 2029. That is more restrained than consensus. The new data center tools could eventually push those expectations higher or lower, so investors may want to explore both stories before deciding what feels reasonable.
Explore 2 other Keysight Technologies fair value estimates, including one that suggests it could be worth just $365.72.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Keysight Technologies research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Keysight Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Keysight Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Keysight Technologies?
If the Keysight Technologies story has sharpened your thinking about AI infrastructure and testing, it can help to compare it with other businesses that share some of the same qualities you care about. The Simply Wall St Screener lets you filter for exactly that, whether you care most about value, balance sheet strength, or downside risk.
- If you are hunting for opportunities where quality and value intersect, scan through a curated set of 32 high quality undervalued stocks that might warrant a closer look beside Keysight Technologies.
- For readers who care most about staying on the right side of risk, narrow the field to 11 resilient stocks with low risk scores and see which companies line up with your tolerance for volatility and financial stress.
- When balance sheet resilience is the priority, focus your research on a list of solid balance sheet and fundamentals (23 results) and compare their financial footing with what you see at Keysight Technologies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com