
Lattice Semiconductor (LSCC) Shares Moved, What Is Drawing Attention Now?
Lattice Semiconductor (LSCC) has drawn fresh attention after recent trading. The share price closed at $119.76, with short term moves contrasting with declines over the past month and past 3 months.
Viewed over a longer stretch, the stock’s momentum looks more mixed. The 1 day share price return of 4.92% and 7 day gain of 3.33% come after a 30 day decline of 8.20% and a 90 day drop of 19.61%. Lattice Semiconductor still shows a year to date share price return of 52.27% alongside an 85.93% total shareholder return over the past year, which indicates a more complex pattern of changing investor views on both its potential and its risks rather than a simple one way trend.
Scan beyond Lattice Semiconductor’s sharp swings and evaluate other chip makers with similar momentum and risk profiles using the curated 89 AI infrastructure stocks.
After Lattice Semiconductor’s sharp rebound yet weaker 1 and 3 month stretch, the real tension now is simple: does paying today’s price still make sense, or does patience for a cheaper entry look more reasonable once you test the valuation?
Most Popular Narrative: 27% Undervalued
Lattice Semiconductor’s most followed valuation narrative points to a fair value of $164.92 against the recent close at $119.76. The story now hinges on whether the growth assumptions that back this gap feel realistic to you.
Strong growth prospects in industrial automation, robotics, and IoT, fueled by rising adoption of connected devices and demand for energy-efficient edge computation, position Lattice to benefit from broad end-market exposure and application diversity, enhancing long-term revenue durability.
Product mix shift toward higher-value new products (Nexus, Avant, AI-optimized FPGAs) is raising overall gross margins, with management indicating new products will be the main revenue driver through 2026. The transition supports sustainable margin and earnings improvement.
See why 21 investors see Lattice Semiconductor as 27% undervalued.
The narrative framework uses an 11.21% discount rate, revenue growth assumptions of about 45% per year and an expected profit margin of roughly 26%, then discounts those future cash flows and earnings back to today to land on that $164.92 figure. Analysts in this storyline also work off a 2029 earnings outlook that implies a future P/E of about 68x, which keeps the valuation rich relative to the broader US Semiconductor industry while still lower than the current implied multiple.
These building blocks explain why the narrative tags Lattice Semiconductor as undervalued despite a high value score of just 1 on the Simply Wall St model and a current price that already embeds strong expectations. The gap between the $119.76 share price and the $164.92 fair value depends heavily on those high growth and margin assumptions holding up through the next cycle, particularly around AI data center demand, industrial automation and the AMI acquisition.
Result: Fair Value of $164.92 (UNDERVALUED)
Still, Lattice Semiconductor’s story can break if rising competition in low and midrange FPGAs squeezes margins, or if China related regulatory pressure disrupts demand.
Find out about the key risks to this Lattice Semiconductor narrative.
Another View On Lattice Semiconductor’s Valuation
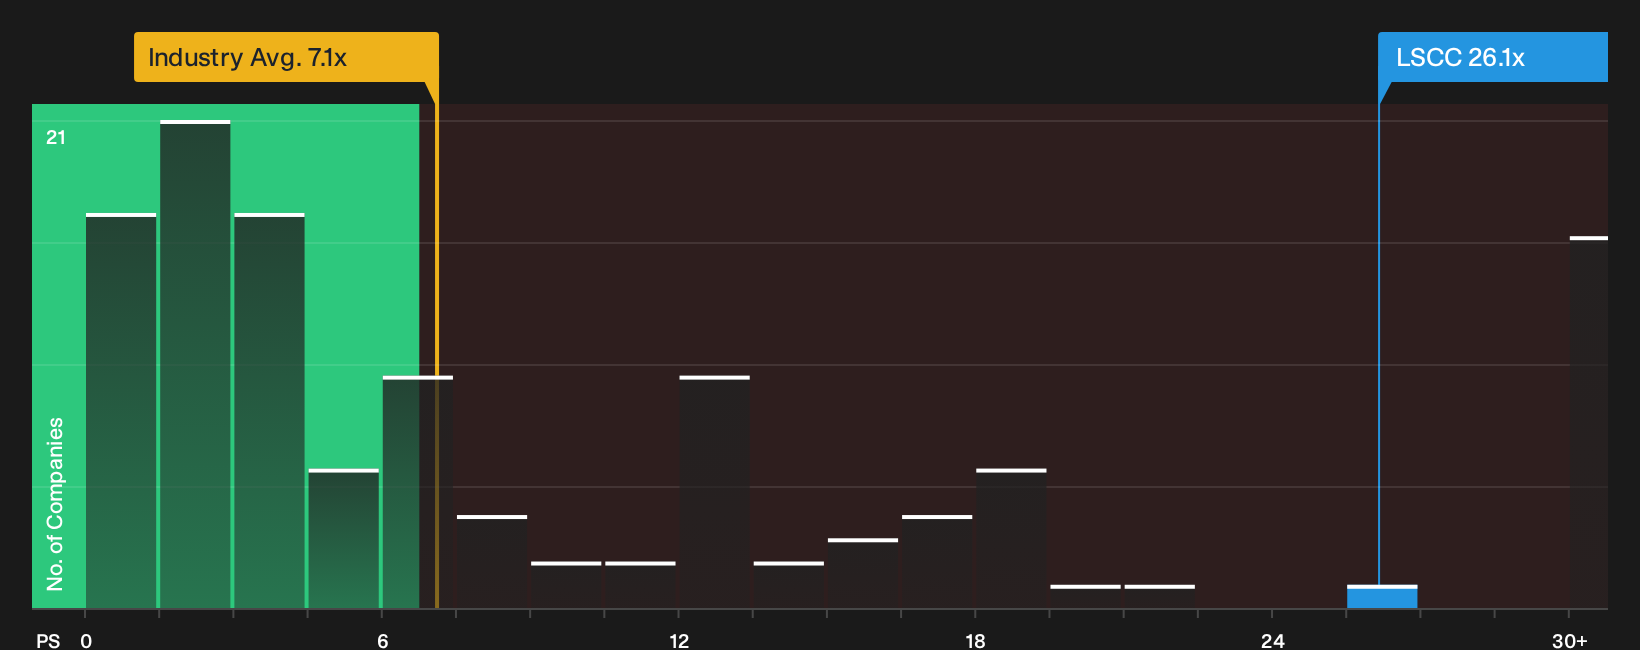
The story so far presents Lattice Semiconductor as undervalued if the bullish growth path occurs. A very different picture appears when looking at the current P/S ratio of 26.1x. That is far above the US Semiconductor group at 7.1x and above the fair ratio of 17.2x that the market could move toward over time.
This gap implies that even strong execution may already be heavily reflected in today’s price, while any disappointment could trigger a sharper reset than peers. The key question is which valuation lens you consider most relevant when you size your position.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Lattice Semiconductor’s recent move are clear, so move quickly to review the full data set and pressure test your own thesis. To help weigh both sides of the story in one place, start with our breakdown of 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Lattice Semiconductor?
If you stop with Lattice Semiconductor, you only see one angle. Broaden your watchlist with fresh ideas that line up better with your risk, income, and value goals.
- Target potential mispricing by scanning for high quality businesses trading below their estimated worth through the 32 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies with reliable payouts using the 6 dividend fortresses.
- Dial down portfolio stress by prioritizing sturdier balance sheets and steadier fundamentals via the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com