
Japan Post Holdings (TSE:6178) As A 15.6x P E Raises Fresh Valuation Questions
Japan Post Holdings (TSE:6178) has drawn fresh attention after its shares last closed at ¥2,469. That price level, combined with recent return figures, is prompting investors to reassess expectations.
Over the past year, momentum around Japan Post Holdings has been building, with a 42.7% year to date share price return and a 64.4% total shareholder return. The recent 7 day share price pullback contrasts with stronger 30 day and 90 day gains that hint at shifting expectations around both growth potential and risk.
Scan how Japan Post Holdings compares with other large, cash-generative financials by reviewing the hand-picked list of solid balance sheet and fundamentals (19 results) in this market segment.
Japan Post Holdings now trades close to analyst targets despite a solid year on the scoreboard. Is that tight discount caution well placed, or has the latest pullback left some value on the table?
Price-to-Earnings of 15.6x: Is it justified?
Japan Post Holdings trades on a P/E of 15.6x, compared with a peer average of 12.1x and an Asian insurance sector average of 11.3x. That richer tag sits alongside a last close of ¥2,469 and a discount to the Simply Wall St fair P/E of 17.4x.
The P/E ratio compares the current share price with earnings per share. For a diversified financial group like Japan Post Holdings, it reflects what the market is willing to pay for each unit of current earnings across postal operations, banking services, and life insurance.
The current multiple indicates investors are paying more per unit of profit than for sector peers, even though the company is assessed as good value against an estimated fair P/E of 17.4x. That gap suggests the valuation could still shift if earnings, which analysts expect to grow 14.9% per year, play out differently to current assumptions.
Against the broader Asian insurance industry, the premium is even clearer. A 15.6x P/E versus 11.3x signals the market is assigning Japan Post Holdings a meaningfully higher earnings tag than many regional insurers, while the fair ratio points to a level the valuation could move toward if sentiment and fundamentals line up.
Explore the SWS fair ratio for Japan Post Holdings.
Result: Preferred multiple of Price-to-Earnings of 15.6x (OVERVALUED)
Still, the tight discount to analyst targets and the wide mix of postal, banking, and insurance operations means sentiment could turn quickly if any segment underperforms.
Find out about the key risks to this Japan Post Holdings narrative.
Another view on Japan Post Holdings valuation
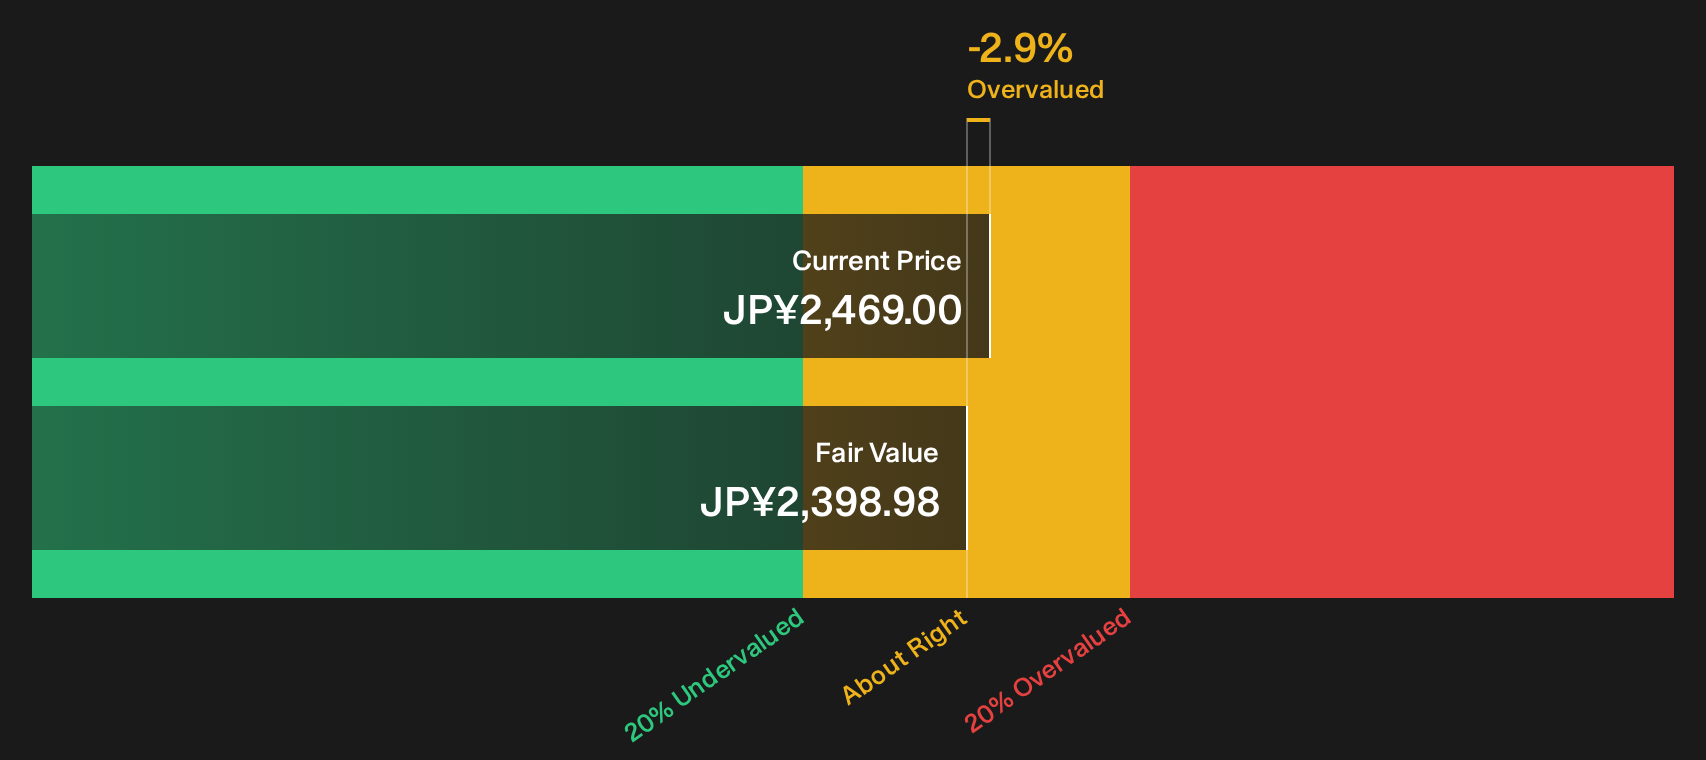
While the 15.6x P/E points to a richer tag for Japan Post Holdings, the SWS DCF model paints a different picture. On that framework, the shares at ¥2,469 sit above an estimated future cash flow value of ¥2,398.98, which leans toward an overvalued reading on this metric.
This gap between earnings based pricing and cash flow value raises a simple question for you: Which risk matters more right now, paying up for current profits or paying above an internal estimate of long term cash generation?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Japan Post Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Japan Post Holdings can tempt investors to lean on headlines instead of the numbers. Act promptly, stress test the data for yourself, and weigh both sides of the story by reviewing the 1 key reward and 1 important warning sign
Looking for more investment ideas beyond Japan Post Holdings?
If Japan Post Holdings has you thinking harder about value and risk, use that momentum and widen your watchlist with a few focused screeners.
- Target stronger value potential by scanning a curated set of quality businesses that appear mispriced on fundamentals through the 16 high quality undervalued stocks.
- Reinforce income in your portfolio by reviewing companies in the 19 dividend fortresses that couple higher yields with resilient profiles.
- Pressure test your downside protection by filtering for companies in the 10 resilient stocks with low risk scores that carry lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com