
Is Ito En (TSE:2593) Fully Valued After First Quarter Sales And Net Income Growth?
Ito En (TSE:2593) kicked off its new fiscal year with first quarter results that caught investor attention, as both sales and net income were higher than a year earlier.
Against that backdrop, Ito En’s 1 month share price return of 5.04% and 3 month share price return of 12.02% suggest momentum has picked up recently, even though the 1 year total shareholder return declined 8.30%. This hints that sentiment has only started to improve after a weaker stretch.
Spot fresh momentum stories like Ito En’s earnings-driven move by scanning our hand picked list of 73 high quality undiscovered gems, which also pair improving results with under-the-radar share prices.Ito En appears to be a solid beverage business with fresh earnings momentum already reflected in its outlook. The open question is whether that renewed optimism is fully captured in the current share price or whether there is still value to be found.
Price-to-Earnings of 84.6x: Is it justified?
On current numbers, Ito En trades on a P/E of 84.6x, while the last close sits at ¥3,165. This points to a rich valuation compared with peers.
The P/E ratio compares what investors are paying for each unit of earnings, so a higher figure usually reflects strong confidence in future profit growth or a very clean earnings profile. For a mature beverage group like Ito En, such a premium P/E depends on the belief that earnings forecasts will materialise and that recent one off items do not reflect the ongoing earnings power of the business.
The comparison is stark. The P/E of 84.6x is far above the peer average of 19.3x and also well ahead of the wider Asian beverage sector at 16.7x. It is even expensive against an estimated fair P/E of 32.4x. This suggests the current multiple is far above the level the market could feasibly move toward if expectations reset.
Explore the SWS fair ratio for Ito En.
Result: Price-to-Earnings of 84.6x (OVERVALUED)
Still, Ito En’s high 84.6x P/E and a 1 year shareholder return that declined 8.30% leave little room if earnings or sentiment soften again.
Find out about the key risks to this Ito En narrative.
Another View on Ito En’s Valuation
Price tells one story, cash flows tell another. Our DCF model points to a future cash flow value of ¥263.01 per share, far below Ito En’s current ¥3,165 price. That gap implies the stock screens as overvalued on this framework.
Look into how the SWS DCF model arrives at its fair value.
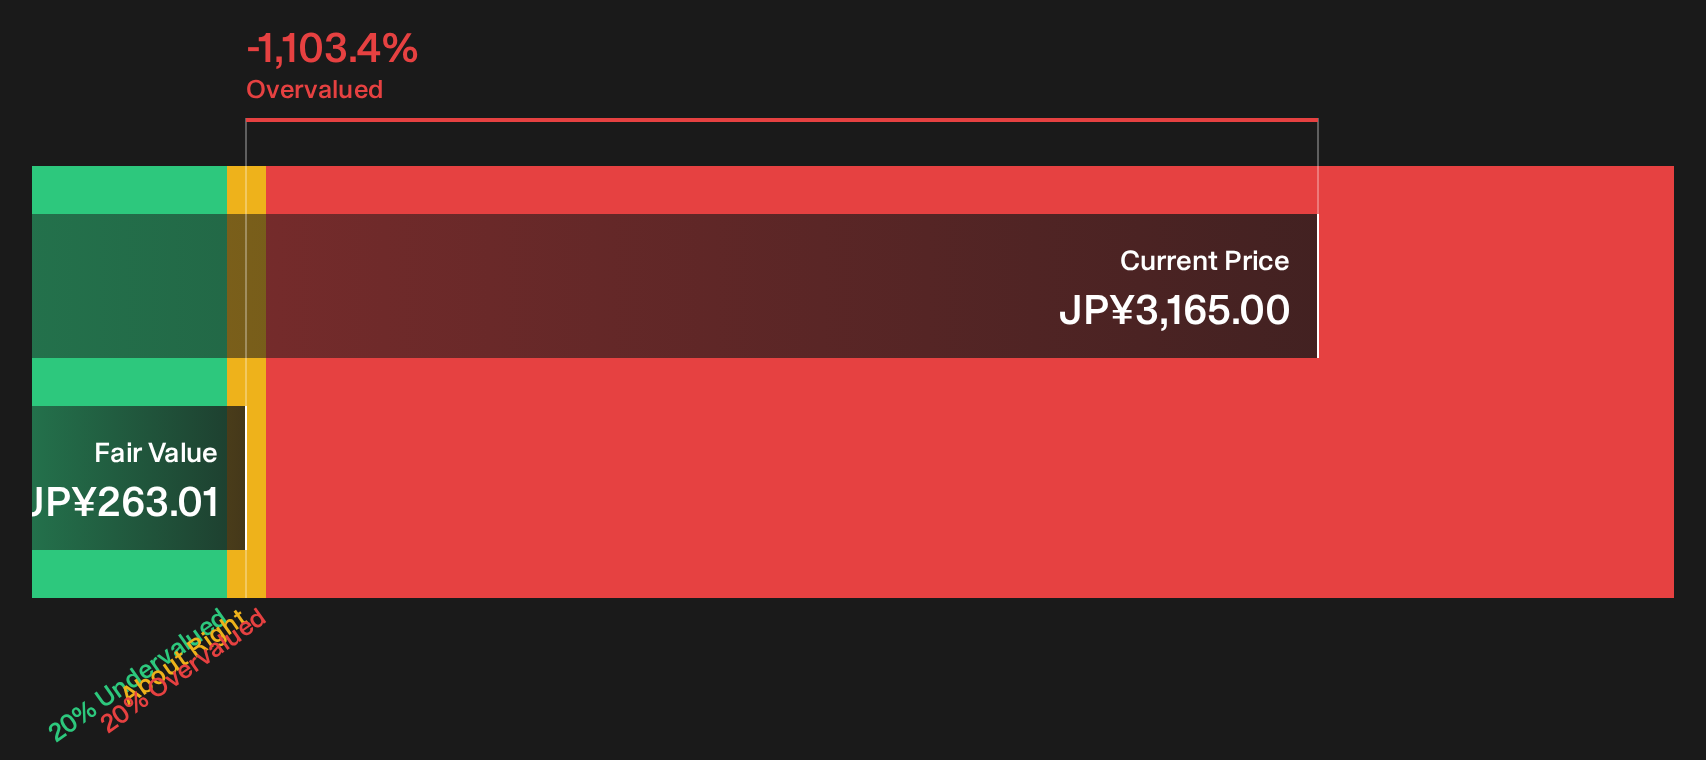
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ito En for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this combination of optimism and concern around Ito En leaves you unsure, it may be useful to review the details yourself and stress test the thesis. A balanced starting point is to consider our breakdown of the 1 key reward and 2 important warning signs.
Looking for more Ito En style investment ideas?
If Ito En has you thinking more carefully about price, quality and momentum, do not stop here. The next strong idea might be hiding in plain sight.
- Spot potential value opportunities early by scanning a fresh set of companies that screen as attractively priced using the 16 high quality undervalued stocks.
- Strengthen your defence by searching for businesses with sturdy finances through the list of solid balance sheet and fundamentals (19 results).
- Build a watchlist of future contenders by hunting for under-the-radar opportunities using the 1 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com