
Is Kamigumi (TSE:9364) A Bargain Or Already Fully Priced?
With no specific news event driving headlines, interest in Kamigumi (TSE:9364) is being shaped instead by its recent share performance and fundamentals, as investors reassess the logistics specialist’s longer term return profile.
Recent trading has softened, with a 30-day share price return showing a 2.91% decline and a year-to-date share price return down 6.51%. However, Kamigumi still shows positive momentum in the background, with a 1-year total shareholder return of 9.33% and a 5-year total shareholder return of 131.65%.
Compare Kamigumi’s mixed recent returns with those of other logistics and infrastructure players by scanning our hand picked list of solid balance sheet and fundamentals (19 results) that may better match your risk and quality preferences.
Kamigumi’s recent pullback sits against strong multi year returns and steady business performance. Does the current valuation still leave enough upside to justify taking on the risk from here?
Preferred P/E of 15.6x for Kamigumi: Is it justified?
Kamigumi currently trades on a P/E of 15.6x, which puts a premium on its ¥4,809 share price compared with several benchmarks and peers.
The P/E ratio compares the price investors pay for each unit of earnings. For a logistics and infrastructure player like Kamigumi, it reflects what the market is willing to pay for a relatively steady earnings profile, modest forecast growth and exposure to trade and industrial activity.
Recent assessments indicate Kamigumi is expensive against multiple reference points. Its 15.6x P/E is higher than the estimated fair P/E of 14.2x, above the peer average of 12x and above the wider Asian infrastructure group on 13.1x. That gap signals investors are currently paying more for each yen of profit than both the modelled fair ratio suggests and what comparable stocks command. The market could move closer to those levels if sentiment or expectations change.
Explore the SWS fair ratio for Kamigumi.
Result: Price-to-earnings of 15.6x (OVERVALUED)
Still, the Kamigumi story can change quickly if trade volumes weaken, or if its diversified side businesses face pressure on profitability or capital needs.
Find out about the key risks to this Kamigumi narrative.
Another view on Kamigumi’s value
The P/E workup paints Kamigumi as expensive, yet the SWS DCF model points the other way. With the share price at ¥4,809 and an estimated future cash flow value of ¥5,402.49, the stock screens about 11% below that fair value. Which lens should carry more weight for you?
Before leaning on either yardstick too heavily, it is worth understanding how this cash flow based estimate is built and what would need to change for that gap to close or widen in future. Look into how the SWS DCF model arrives at its fair value.
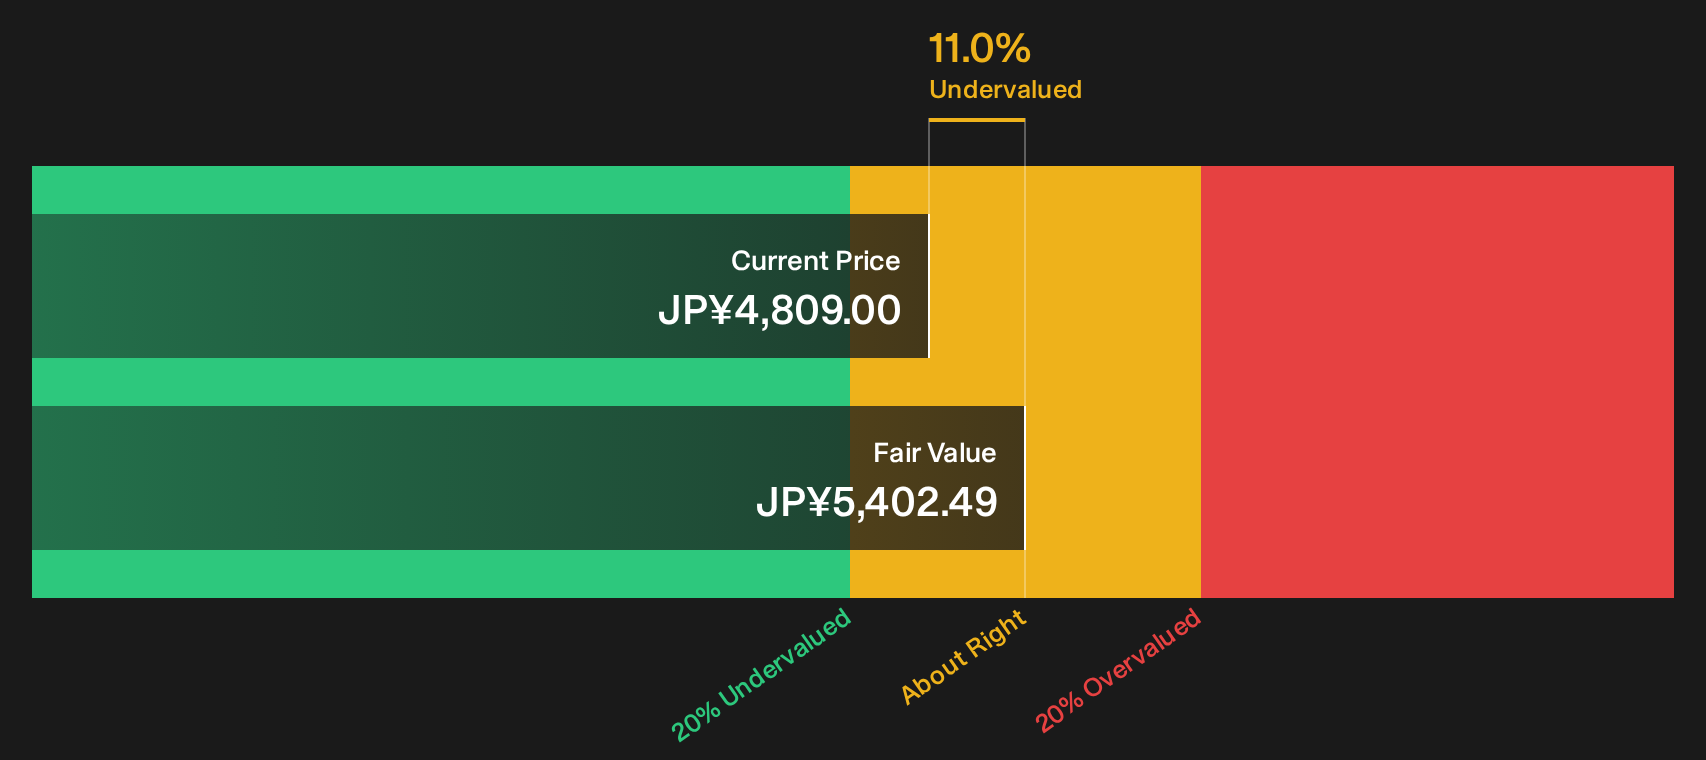
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kamigumi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Kamigumi’s valuation often lead to strong opinions, so act promptly, review the data yourself, and weigh both sides of the story by checking the 2 key rewards and 1 important warning sign.
Looking for more Kamigumi style investment ideas?
Do not stop with Kamigumi alone. Use the Simply Wall Street Screener to uncover fresh ideas that match your goals before the next opportunity slips by.
- Target reliable cash generators by scanning a 16 high quality undervalued stocks that couples stronger fundamentals with prices that still look reasonable.
- Build a steadier income stream by focusing on a 19 dividend fortresses where yields sit at 5% or above.
- Protect your downside first by starting with a 10 resilient stocks with low risk scores that screens for resilient balance sheets and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com