
How Investors Are Reacting To Cheesecake Factory Stock Updated 2026 Guidance
- The Cheesecake Factory updated its 2026 outlook, now guiding to about $4 billion in total revenue and an expected net income margin near 5.4%.
- This guidance gives investors a clearer view of how Cheesecake Factory currently balances guest demand, pricing, and cost control within its restaurant portfolio.
- We will now look at how Cheesecake Factory's guidance for roughly a 5.4% net income margin reshapes the broader investment narrative.
Cheesecake Factory Investment Narrative Recap
To own Cheesecake Factory, you need to be comfortable with a dine-in focused concept that depends on guests paying for an experience, not just a quick meal. The updated 2026 outlook for about US$4b of revenue and roughly 5.4% net income margin mainly reinforces the current operating playbook rather than resetting it.
The near term swing factor still looks like traffic at core Cheesecake Factory locations and sister concepts like North Italia and Flower Child. Rising labor and occupancy costs remain the key threat to that 5.4% profitability target. This guidance does not remove those pressures; instead, it helps frame what management currently sees as achievable.
The most relevant update is this fresh 2026 guidance, since it ties revenue ambitions directly to an explicit net income margin for Cheesecake Factory. With current net margin at 4.6%, investors can now compare that stated 5.4% goal to past execution on cost control, pricing and menu mix across the portfolio.
This matters for your catalyst checklist. The path from 4.6% to about 5.4% depends on maintaining guest demand while handling labor inflation, mall exposure and competition from fast casual and digital first rivals. Any sustained traffic softness at Cheesecake Factory or North Italia would make that margin ambition harder to support.
Cheesecake Factory's current analyst narrative points to about US$4.8b in revenue and US$334.2m in earnings by 2029, based on an assumed 7.4% yearly increase in sales and an earnings rise of roughly US$155.6m from US$178.6m today.
Uncover why Cheesecake Factory's fair value indicates a 12% potential downside to its current price, a premium that may not be sustained.
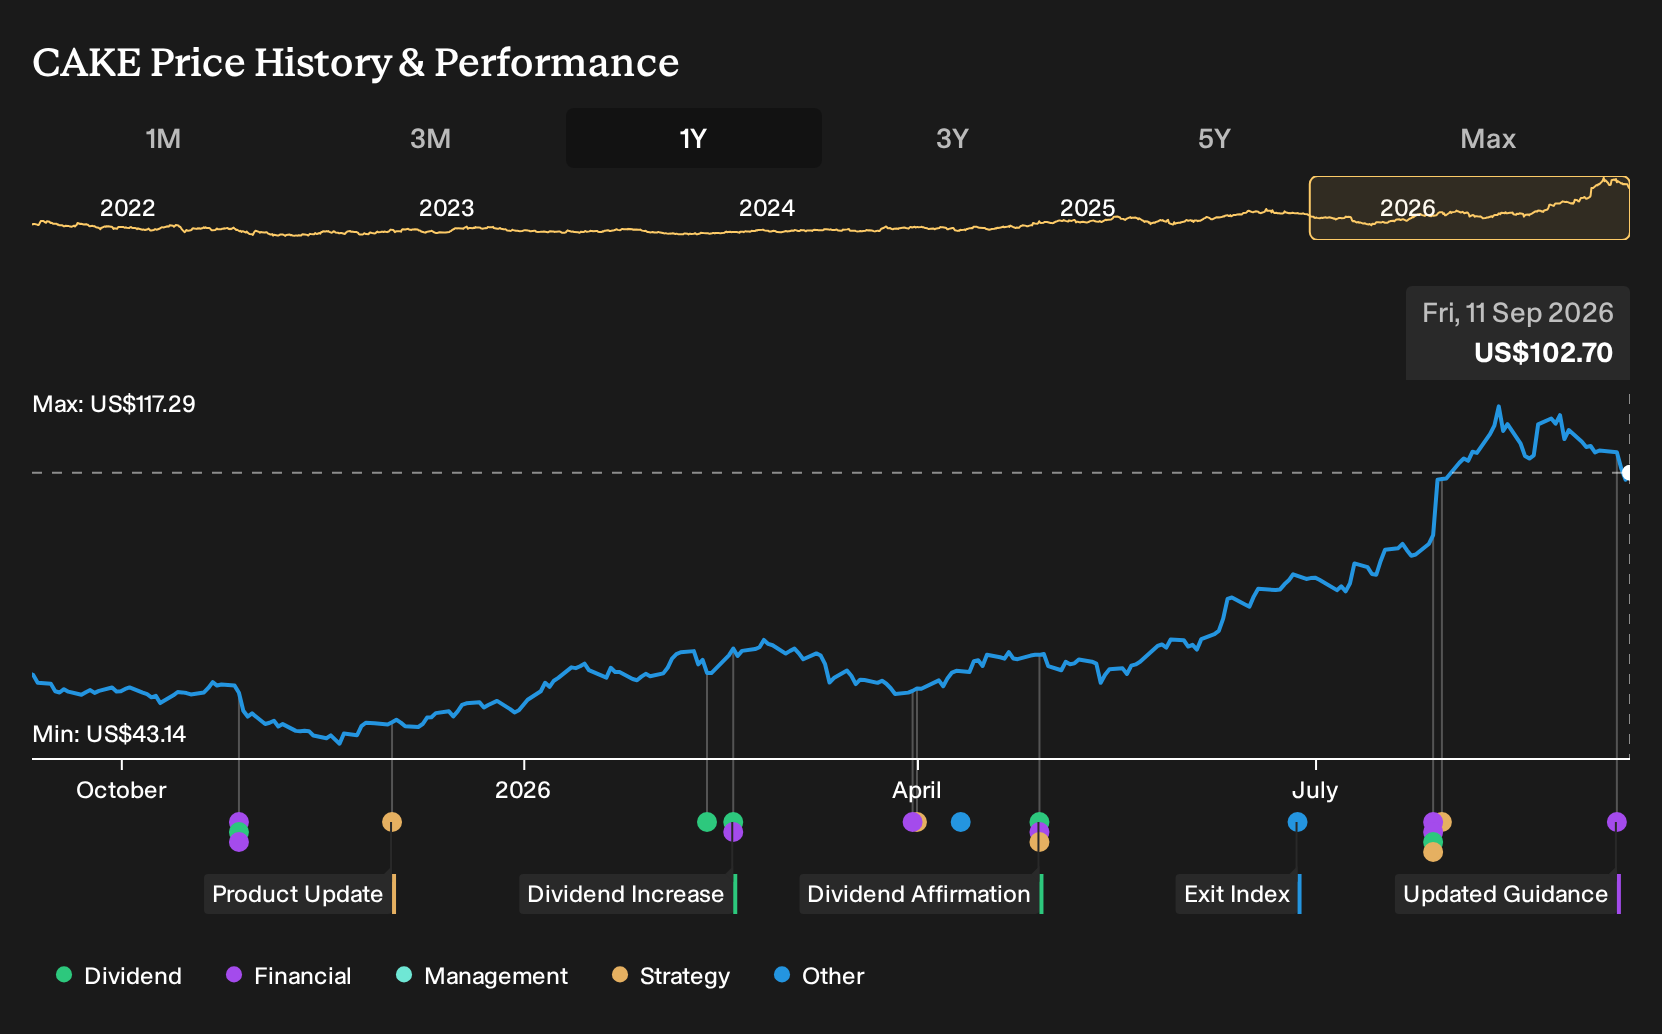
Exploring Other Perspectives
You can read the same 2026 guidance and still land in a very different place. The most pessimistic Cheesecake Factory analysts were working off roughly US$4.7b of 2029 revenue and about US$322.1m of earnings, yet still saw value closer to US$71.16. Those views were formed before this new outlook, so some narratives may shift.
Explore 3 other Cheesecake Factory fair value estimates, including one that suggests as much as 31% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cheesecake Factory research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cheesecake Factory. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cheesecake Factory's overall financial health at a glance.
Looking for more Cheesecake Factory style investment ideas?
If Cheesecake Factory's updated outlook has you thinking about how to balance quality, resilience and price across a wider watchlist, the Simply Wall St Screener can help you filter for other businesses that fit your approach while still keeping the process quick and disciplined.
- If capital protection comes first for you, start with a group of companies that pair sturdier finances with milder risk profiles by checking out 11 resilient stocks with low risk scores.
- If you want income on top of potential capital gains, scan for businesses that currently offer stronger cash returns to shareholders through the 6 dividend fortresses.
- If you are hunting for quality that is not yet widely followed, widen your research funnel with the 15 high quality undiscovered gems and see what else deserves a place on your radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com