
Open Up Group And 2 Other Undiscovered Gems In Global Markets
In recent weeks, global markets have faced heightened volatility due to escalating geopolitical tensions in the Middle East, which pushed oil prices higher and fueled inflation concerns. This environment has particularly impacted small-cap indices like the Russell 2000 and S&P MidCap 400, which saw notable declines as investors grapple with rising Treasury yields and shifting monetary policy expectations. In such a climate, identifying stocks that exhibit resilience through strong fundamentals or unique market positions can be crucial for navigating uncertainty.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| GROUPE SFPI | 18.02% | 4.25% | -29.76% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Aqualis | 33.30% | 22.28% | -18.13% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
Open Up Group (TSE:2154)
Simply Wall St Value Rating: ★★★★★☆
Overview: Open Up Group Inc. operates by dispatching engineers to manufacturers, construction contractors, and IT companies across Japan, the United Kingdom, and internationally; it has a market capitalization of ¥163.38 billion.
Operations: Open Up Group Inc. generates revenue primarily from its Machinery and Electronics Segment (¥66.74 billion) and Construction Segment (¥57.60 billion), with additional contributions from the IT Segment (¥40.92 billion) and Overseas Segment (¥768 million).
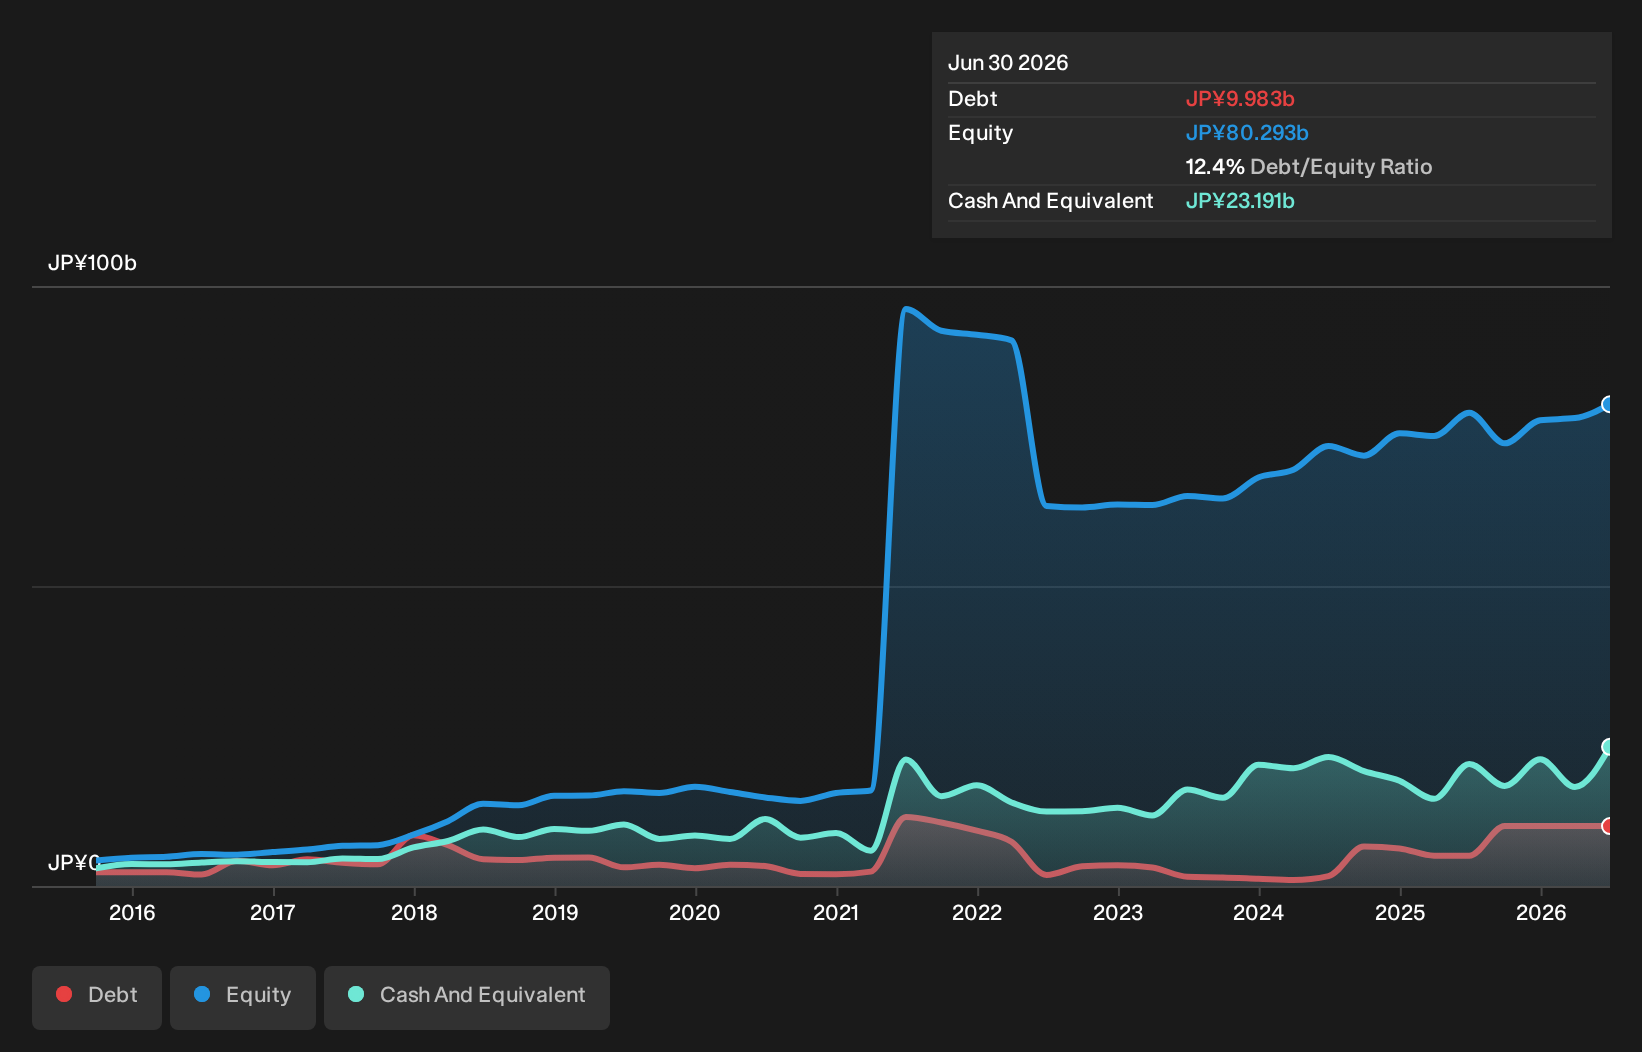
Open Up Group, a smaller player in its industry, recently reported a decrease in sales to JPY 167.48 billion from JPY 187.95 billion last year, with net income slightly down to JPY 11.83 billion from JPY 12.56 billion. Despite these dips, the company trades at an attractive valuation—46.6% below its estimated fair value—and maintains robust financial health with more cash than total debt and strong interest coverage of 283 times by EBIT. Additionally, Open Up's earnings per share dropped marginally but it still announced increased dividends for the fiscal year ending June 2027, reflecting confidence in future prospects.
- Take a closer look at Open Up Group's potential here in our health report.
Review our historical performance report to gain insights into Open Up Group's's past performance.
Sony Financial Group (TSE:8729)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Sony Financial Group Inc., with a market cap of ¥1.08 trillion, operates in Japan offering a range of financial services through its subsidiaries.
Operations: The group generates significant revenue primarily from its Life Insurance Business, amounting to ¥2.55 trillion, followed by the Banking Business at ¥137.14 billion and Non-Life Insurance Business contributing ¥197.80 billion.
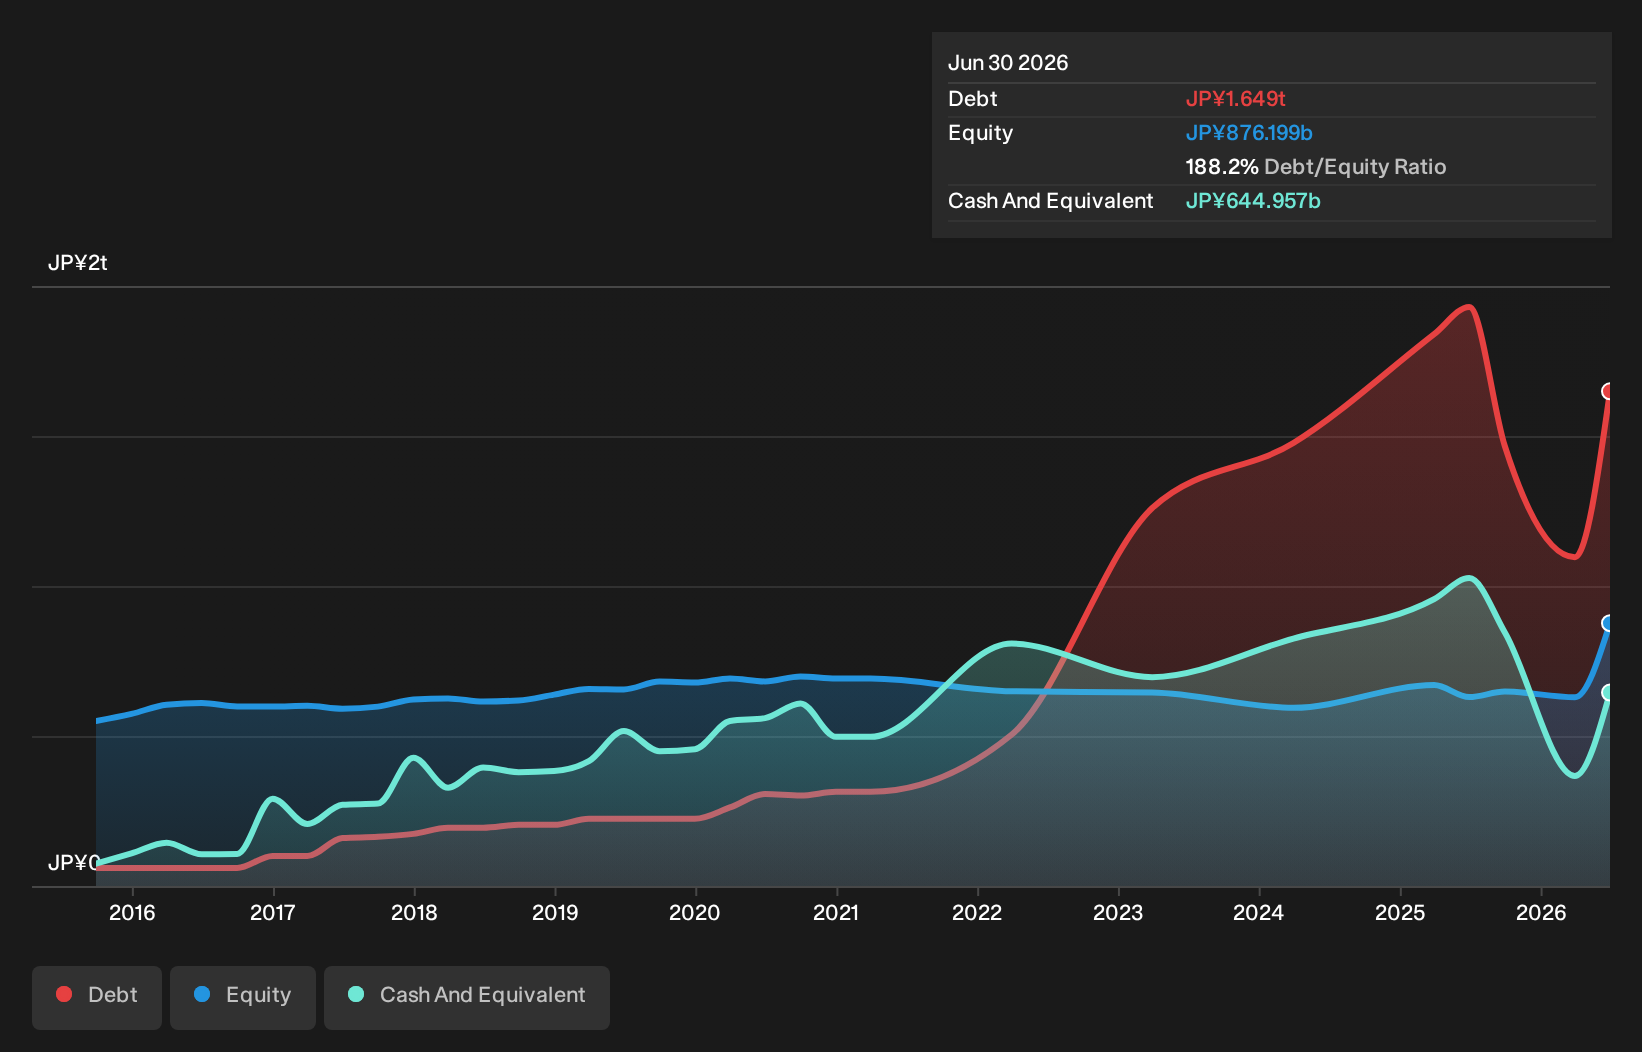
Sony Financial Group's recent performance highlights its potential as a promising investment. Over the past year, earnings surged by 87.9%, significantly outpacing the Diversified Financial industry average of 17.6%. Despite this impressive growth, the company faces challenges with a high net debt to equity ratio of 114.6% and a notable one-off loss of ¥222.7 billion impacting its financial results for the year ending June 2026. Trading at approximately 23.5% below estimated fair value, Sony Financial appears undervalued relative to peers, offering an intriguing opportunity for investors seeking value in smaller-cap financial entities.
- Navigate through the intricacies of Sony Financial Group with our comprehensive health report here.
Evaluate Sony Financial Group's historical performance by accessing our past performance report.
Marketech International (TWSE:6196)
Simply Wall St Value Rating: ★★★★★★
Overview: Marketech International Corp. operates in the manufacturing, sales, importation, and trading of integrated circuits, semiconductors, electrical and computer equipment and materials across Taiwan, China, the United States, and internationally with a market cap of NT$112.59 billion.
Operations: The primary revenue streams for Marketech International Corp. include the Factory System and Electromechanical System Service Business Segment, generating NT$41.70 billion, followed by the Equipment Materials Agent Sales Business Segment with NT$12.39 billion. The Customized Equipment Manufacturing Segment contributes NT$10.19 billion to the overall revenue mix.
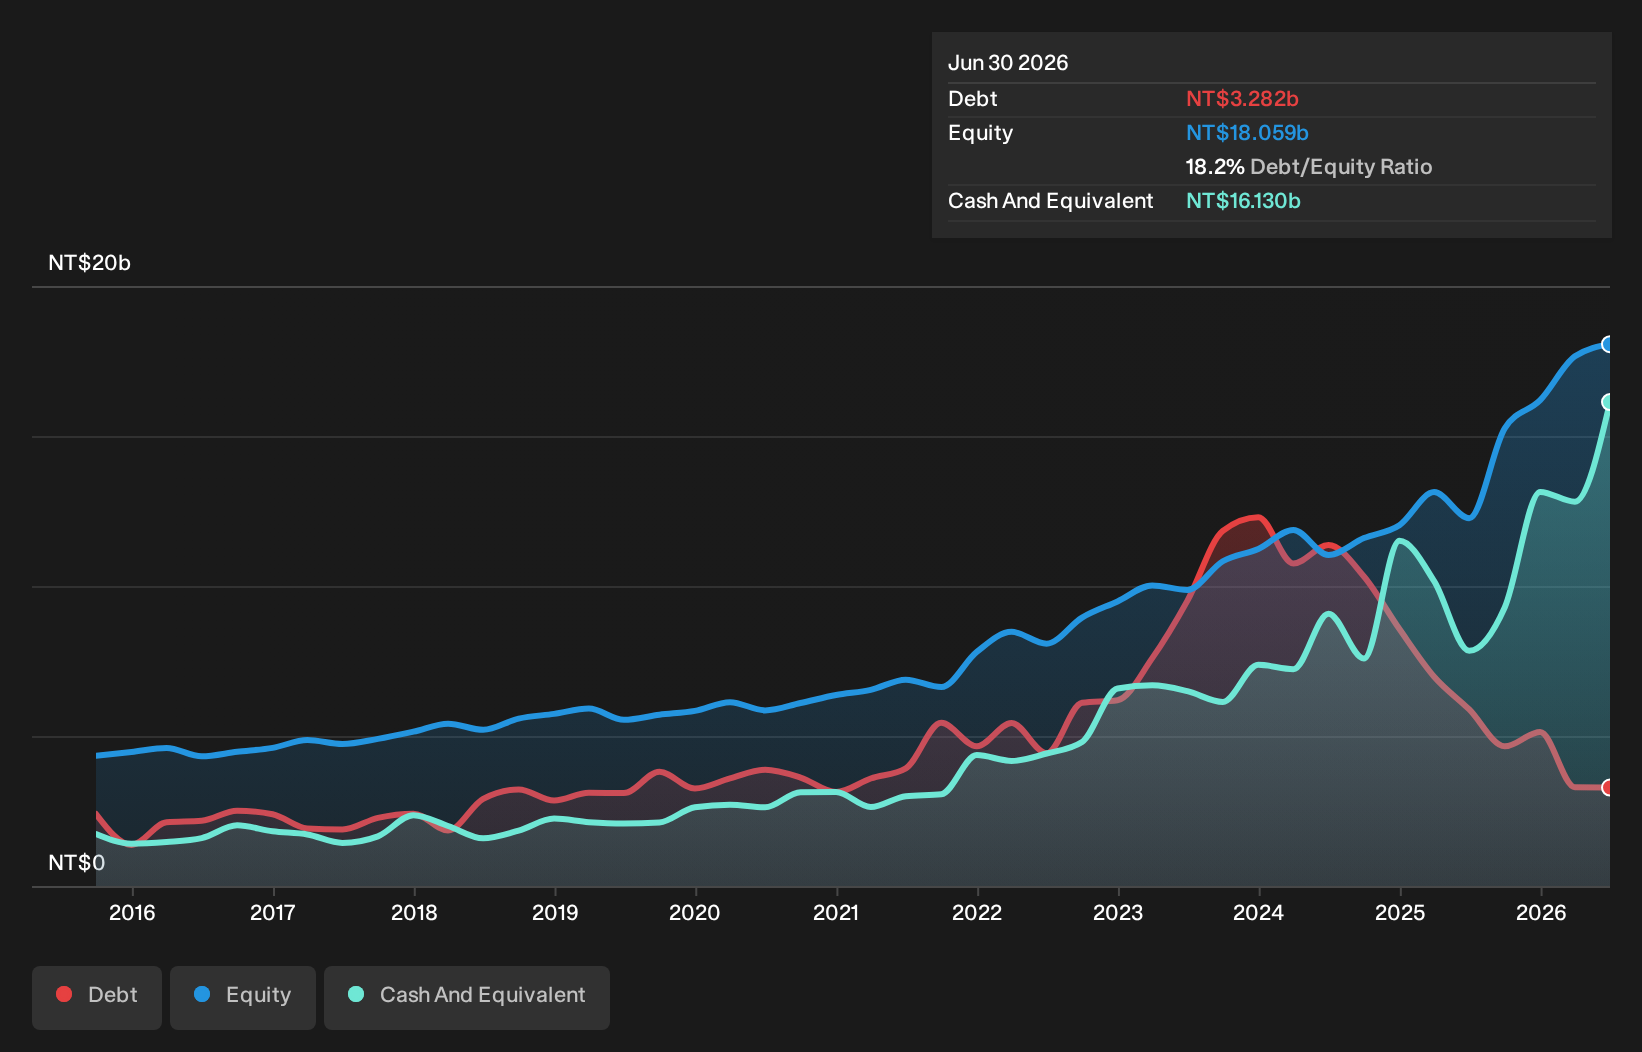
Marketech International, a nimble player in the semiconductor industry, has seen its earnings grow by 118% over the past year, outpacing the industry's 43.5%. Trading at 31.7% below estimated fair value suggests it's undervalued relative to peers. The debt-to-equity ratio has impressively dropped from 57% to 18.2% over five years, indicating strong financial management. Recent earnings reports show a robust performance with second-quarter sales at TWD 21 billion compared to TWD 12 billion last year and net income climbing from TWD 396 million to TWD 1,800 million. Earnings per share also jumped significantly from TWD 1.95 to TWD 8.17 this quarter.
- Click here and access our complete health analysis report to understand the dynamics of Marketech International.
Learn about Marketech International's historical performance.
Taking Advantage
- Investigate our full lineup of 166 Global Undiscovered Gems With Strong Fundamentals right here.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com