
How Leadership Changes Will Impact DXC Stock Investors
- DXC Technology recently appointed Arun Melkote as Global Head of Delivery for Consulting & Engineering Services and assigned Kartik Iyer to lead Customer Value Centers, Workforce Transformation, and Strategic Programs, reshaping leadership across its consulting, engineering, and delivery operations.
- The reshuffle concentrates accountability for AI native software engineering, application modernization, and global delivery in a small group of senior leaders. This may influence how effectively DXC Technology aligns its cost structure, talent pool, and service quality with enterprise demand for digital transformation.
- We will now look at how DXC Technology's investment narrative could be affected by Melkote's expanded role over global CES delivery.
Compare DXC Technology's leadership driven AI and modernization push with hand picked peers by scanning 89 AI infrastructure stocks that are building the backbone of enterprise computing.
DXC Technology Investment Narrative Recap
To own DXC Technology, you need to believe its shift toward Consulting & Engineering Services and AI native work can eventually offset pressure in the shrinking Global Infrastructure Services segment. The near term swing factor remains whether strong bookings and a book to bill above 1.0 can slow the current organic revenue declines that management has guided for fiscal 2026.
The biggest risk is that execution falls short and GIS erosion, high debt and thinner 1% net margins keep dragging on earnings, even as new contracts are signed. The Melkote and Iyer appointments matter only if they translate into tighter delivery, fewer deal deferrals and better conversion of backlog into cash.
The leadership change around Consulting & Engineering Services ties directly into the existing AI and modernization catalyst. Melkote now oversees CES delivery, including Global Capability Centers and custom applications, and works alongside DXC Technology partner and AI teams such as LabX. That structure sits at the operational choke point, where large digital transformation deals either run smoothly or disappoint clients.
With bookings already strong and 92% of technical staff described as AI ready, the critical question is whether this delivery setup improves margins, stabilizes revenue and mitigates customer hesitancy on large contracts. If execution inside CES stumbles, the risk narrative around ongoing revenue decline, low return on equity and pressured profitability remains firmly in place.
DXC Technology's narrative projects US$12.1b revenue and US$217.1m earnings by 2029. This assumes revenue declines at 1.4% per year and requires an earnings increase of about US$199.1m from US$18.0m today.
Uncover why DXC Technology's fair value indicates DXC Technology is currently fairly valued.
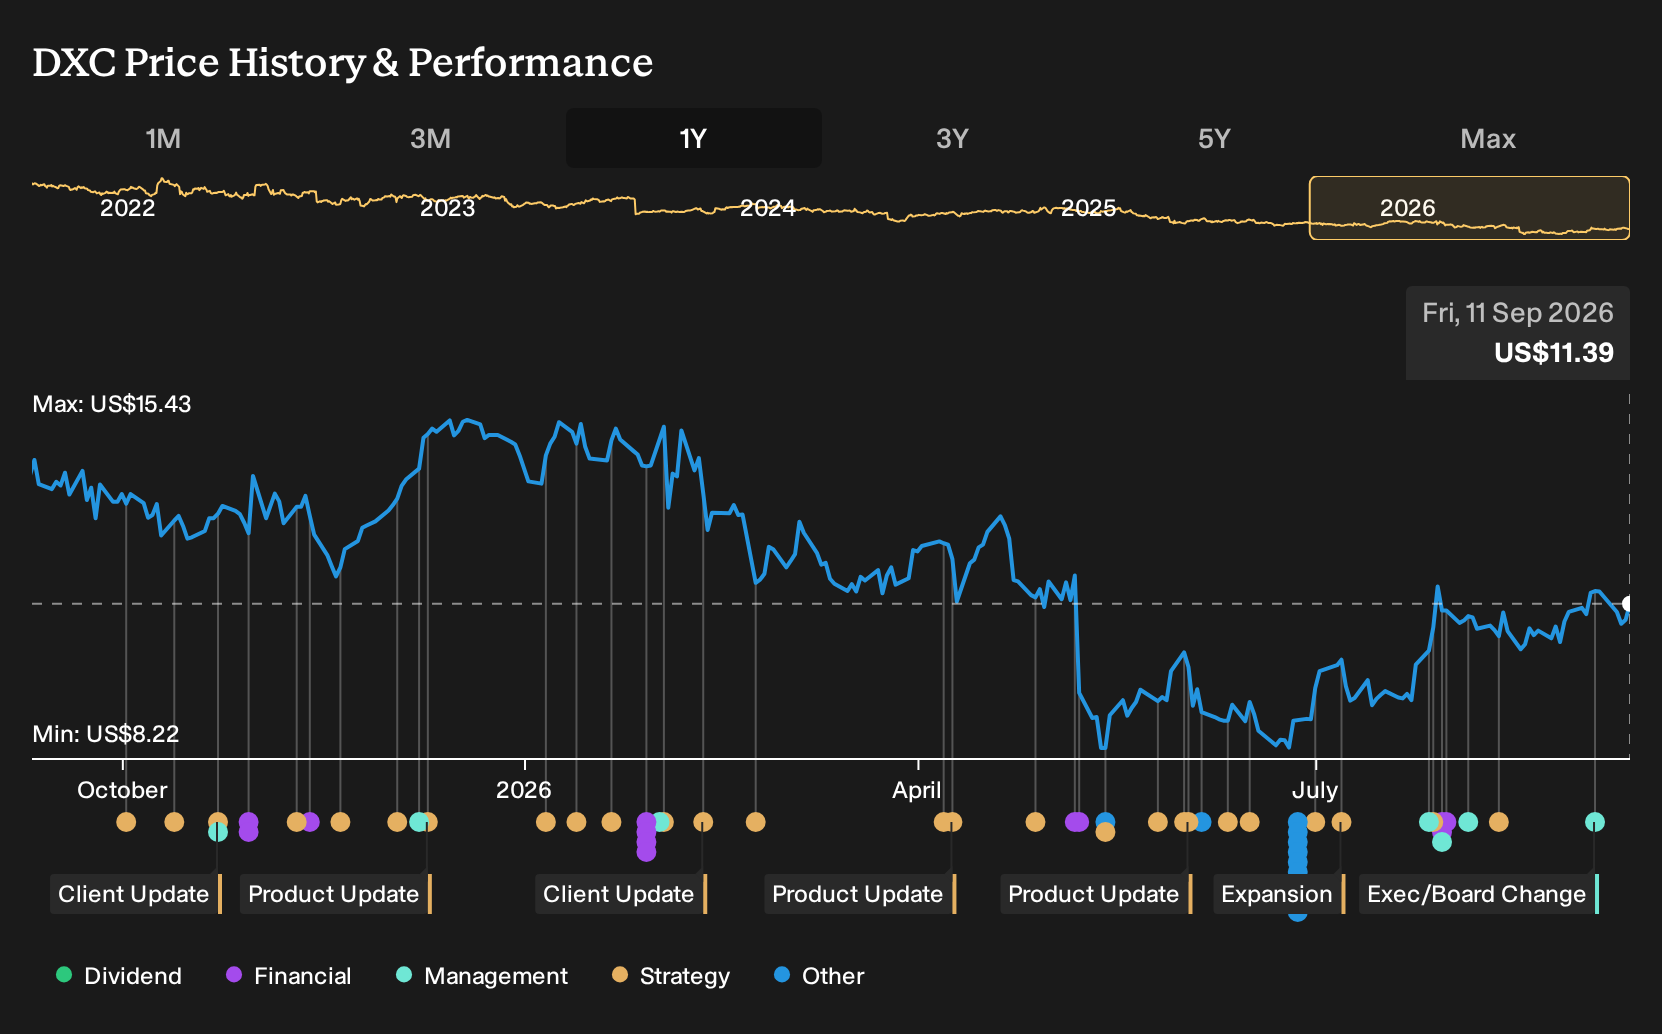
Exploring Other Perspectives
One alternate view focuses on contracting revenue rather than AI opportunity. The most bearish analysts were assuming DXC Technology’s revenue would decline about 2.8% a year and earnings would reach roughly US$155.7m by 2029. That is far below the US$217.1m consensus, so this leadership news could prompt some to rethink those projections.
Explore 3 other DXC Technology fair value estimates, including one that suggests as much as 21% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DXC Technology research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for DXC Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DXC Technology's overall financial health at a glance.
Looking For More DXC Technology Style Investment Ideas?
If the DXC Technology story has you thinking about where else disciplined execution, balance sheet strength and income potential might show up, it can help to broaden your watchlist using focused stock screens on Simply Wall St.
- For investors who care most about capital preservation and lower volatility, consider starting with a 11 resilient stocks with low risk scores that tend to maintain steadier fundamentals through different market conditions.
- If durable financial footing is your priority, filter for companies with strong liquidity and manageable leverage using the list of solid balance sheet and fundamentals (23 results) to spot businesses that can better absorb operational shocks.
- Those aiming to pair income with fundamental strength can scan a 6 dividend fortresses that currently offer higher yields while still clearing key quality hurdles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com