
Mitsubishi Estate (TSE:8802) Looks Fully Valued On Mixed Signals At ¥3,644
Mitsubishi Estate (TSE:8802) has drawn investor attention after recent trading left the share price at ¥3,644. The move comes against mixed shorter term returns, alongside a stronger 3 year and 5 year record.
Over the past year, Mitsubishi Estate has shown mixed short term share price moves, with the 90 day share price return down 12.93%. However, the 1 year total shareholder return of 9.40% and the 5 year total shareholder return of 126.07% point to momentum that has built over longer horizons.
Scan how Mitsubishi Estate compares with other real estate and infrastructure plays by checking a hand picked set of list of solid balance sheet and fundamentals (19 results).
Short term weakness now collides with Mitsubishi Estate’s strong multi year record and a sizeable real estate platform. Investors may wish to consider how this mix affects the balance of risks and potential rewards when evaluating the shares at ¥3,644.
Preferred P/E of 15.3x: Is it justified?
Mitsubishi Estate trades on a P/E of 15.3x, which puts a clear price tag on each ¥ of current earnings at the ¥3,644 share price.
The P/E ratio compares what investors pay today with what the business earns per share over the last year. For a diversified real estate operator like Mitsubishi Estate, this measure is commonly used because earnings tend to reflect both rental income and development profits that matter for long term owners.
Relative to the estimated fair P/E of 16.1x, the stock changes hands at a lower multiple than that fair value level suggests, while still carrying a richer tag than both the JP Real Estate industry average of 9.8x and the peer average of 12.5x. That mix points to a market that prices Mitsubishi Estate above local rivals, yet still below where a fair ratio model indicates valuations could settle if sentiment narrowed the gap.
The premium over sector and peer P/E benchmarks is strong. The discount compared with the fair P/E of 16.1x is equally strong and signals a level the market could move towards if current assumptions hold.
Explore the SWS fair ratio for Mitsubishi Estate.
Result: Price-to-earnings of 15.3x (ABOUT RIGHT)
Still, the recent 12.9% 90 day share price decline, combined with Mitsubishi Estate’s wide exposure across offices, housing, and logistics, could quickly challenge the current valuation story.
Find out about the key risks to this Mitsubishi Estate narrative.
Another View on Mitsubishi Estate’s Value
The preferred P/E picture looks friendly, yet the SWS DCF model tells a slightly tighter story. At ¥3,644, Mitsubishi Estate sits above an estimated future cash flow value of ¥3,505.81, which points to the shares being mildly overvalued rather than cheap. So which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
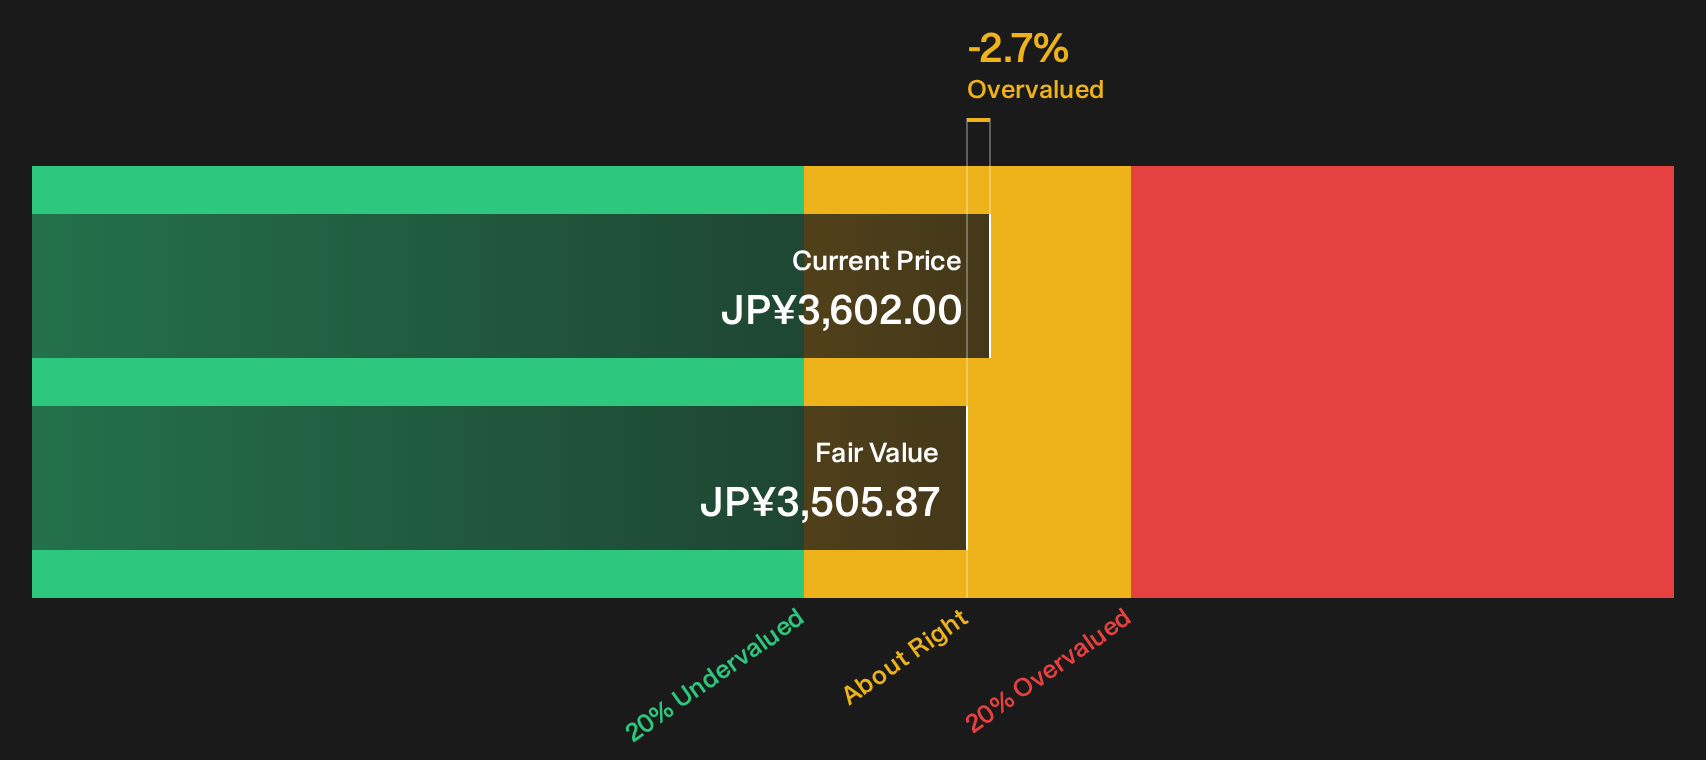
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsubishi Estate for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Mitsubishi Estate leave you on the fence, move quickly from reading to testing the numbers yourself and challenge every assumption. To weigh both the upside and the concerns in one place, start with 3 key rewards and 2 important warning signs.
Looking for more Mitsubishi Estate sized ideas?
Do not stop with Mitsubishi Estate. The same tools can quickly surface other opportunities that fit your risk profile and return goals.
- Target resilient performers by reviewing a curated 10 resilient stocks with low risk scores that focuses on businesses with steadier characteristics.
- Hunt for potential bargains by scanning a focused 17 high quality undervalued stocks that highlights financially strong companies trading on lower valuations.
- Spot resilient cash generators by checking a 18 dividend fortresses that concentrates on higher yielding payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com