
Top 3 Undervalued Small Caps With Insider Action In September 2026
Over the last 7 days, the United States market has remained flat, yet it is up 14% over the past year with earnings forecast to grow by 17% annually. In this context, identifying small-cap stocks that are undervalued and have recent insider action can be a compelling strategy for investors seeking opportunities in a steady market environment.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Cardinal Infrastructure Group | NA | 1.1x | 26.89% | ★★★★★★ |
| Regional Management | 6.5x | 0.5x | 34.96% | ★★★★★★ |
| Financial Institutions | 9.9x | 3.3x | 21.18% | ★★★★★☆ |
| Enovis | NA | 0.5x | 42.88% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.4x | 29.34% | ★★★★☆☆ |
| Bank of the James Financial Group | 10.9x | 2.4x | 26.71% | ★★★★☆☆ |
| Shore Bancshares | 11.8x | 3.4x | 35.69% | ★★★★☆☆ |
| Five Star Bancorp | 15.8x | 6.8x | 42.71% | ★★★☆☆☆ |
| German American Bancorp | 13.2x | 4.9x | 26.07% | ★★★☆☆☆ |
| Orion Group Holdings | 105.2x | 0.4x | 44.09% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
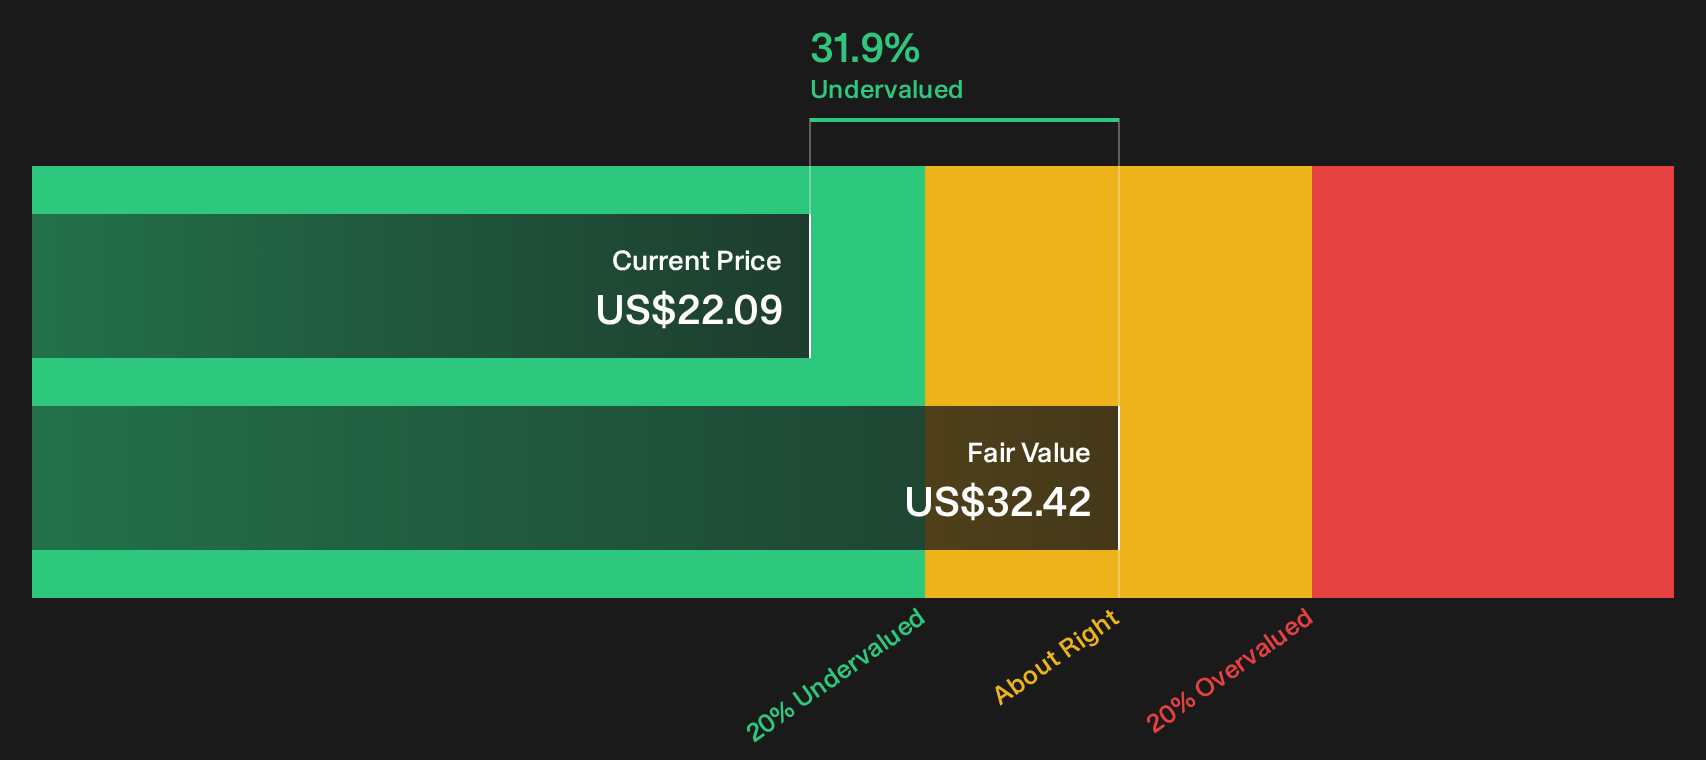
California BanCorp (BCAL)
Simply Wall St Value Rating: ★★★★☆☆
Overview: California BanCorp operates as a commercial banking institution, primarily focusing on providing financial services to businesses and individuals, with a market capitalization of approximately $0.22 billion.
Operations: Commercial banking generates all revenue, with operating expenses primarily driven by general and administrative costs. The net income margin has varied, reaching 33.77% as of September 2025.
PE: 11.6x
California BanCorp, a smaller financial institution, recently reported a slight increase in net interest income to US$43.35 million for Q2 2026. Despite consistent earnings per share of US$0.44, the company faces challenges with expected earnings declines over the next three years. Insider confidence is evident with recent share repurchases totaling 724,437 shares for US$12.78 million since June 2023. The bank's exit from several Russell indexes highlights its undervalued status and potential growth opportunities amidst market repositioning.
- Take a closer look at California BanCorp's potential here in our valuation report.
Examine California BanCorp's past performance report to understand how it has performed in the past.
Alphatec Holdings (ATEC)
Simply Wall St Value Rating: ★★★★★☆
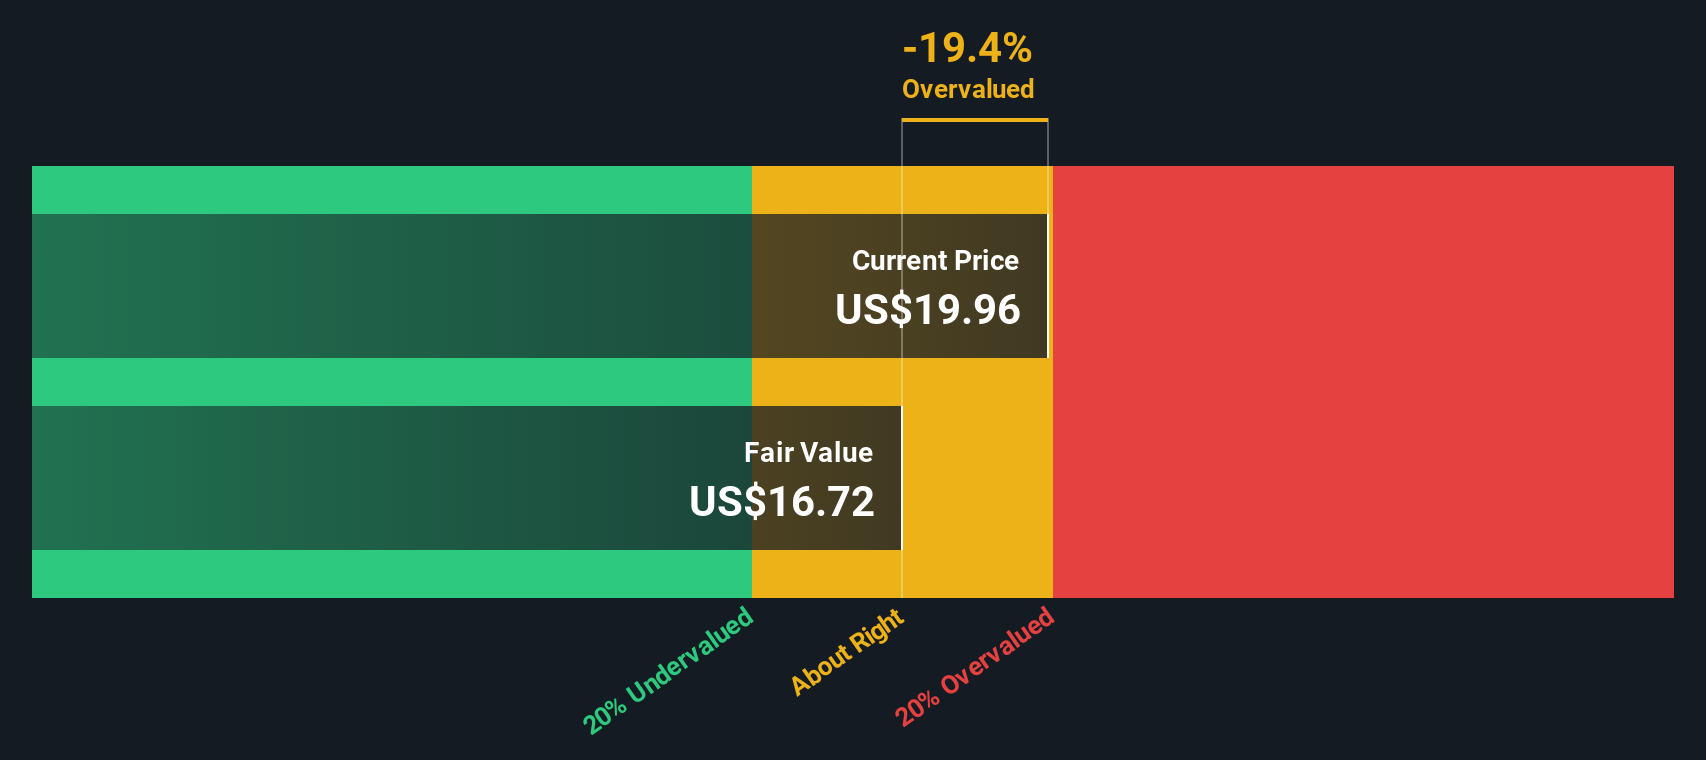
Overview: Alphatec Holdings is a medical technology company focused on the design, development, and advancement of spinal surgery solutions with a market cap of $1.54 billion.
Operations: The primary revenue stream is from medical products, with recent quarterly revenue reaching $815.05 million. The gross profit margin has shown an upward trend, recently recorded at 70.84%. Operating expenses are significant, primarily driven by general and administrative costs and research and development expenditures.
PE: -14.9x
Alphatec Holdings, a player in the healthcare sector, is navigating its way through financial challenges while showing potential for growth. Despite reporting a net loss of US$25.78 million for Q2 2026, this marks an improvement from the previous year's US$41.14 million loss. Insider confidence is evident with recent stock purchases, reflecting belief in future prospects. With earnings forecasted to grow by 62% annually and reaffirmed revenue guidance of approximately US$882 million for 2026, Alphatec demonstrates resilience amidst higher-risk external funding reliance.
Colony Bankcorp (CBAN)
Simply Wall St Value Rating: ★★★☆☆☆
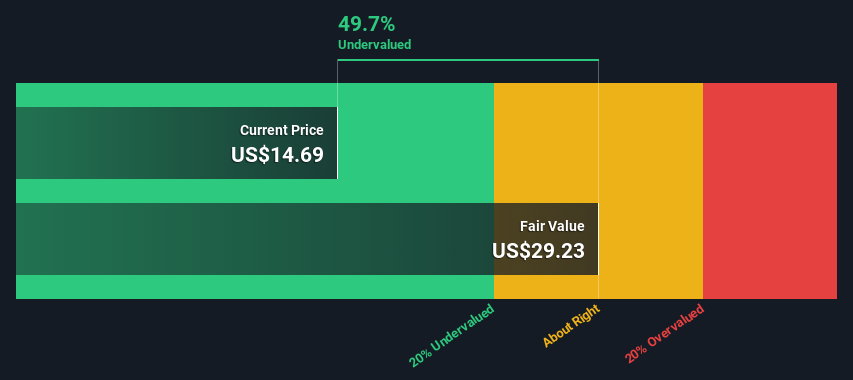
Overview: Colony Bankcorp operates as a financial holding company providing banking, mortgage, and small business lending services, with a market capitalization of approximately $0.14 billion.
Operations: Colony Bankcorp's revenue primarily stems from its Banking Division, with additional contributions from the Mortgage Banking and Small Business Specialty Lending Divisions. The company has consistently achieved a gross profit margin of 100%, indicating that all reported revenues are effectively converted into gross profit. Operating expenses, including significant general and administrative costs, influence net income margins which have shown variability over time, reaching up to 23.33% in recent periods.
PE: 13.9x
Colony Bankcorp's recent financial performance highlights its potential as an undervalued investment. Net interest income rose to US$29.87 million in Q2 2026, up from US$22.39 million a year earlier, while net income increased to US$10.86 million from US$7.98 million. The company's earnings are forecasted to grow by 34% annually, indicating strong future prospects despite past shareholder dilution concerns. Insider confidence is reflected in Edward Canup's purchase of 4,000 shares for approximately US$86,500 between July and September 2026, suggesting optimism about the company's trajectory amidst industry challenges and opportunities discussed at recent conferences and earnings calls.
Summing It All Up
- Dive into all 57 of the Undervalued US Small Caps With Insider Buying we have identified here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com