
TSX Growth Companies With High Insider Ownership September 2026
As the Canadian market navigates through rising oil prices and inflationary pressures, investors are closely watching central banks' responses to these economic challenges. In this environment, growth companies with high insider ownership can offer a unique appeal, as they often demonstrate strong alignment between management and shareholder interests, potentially providing resilience amid market volatility.
Top 10 Growth Companies With High Insider Ownership In Canada
| Name | Insider Ownership | Earnings Growth |
| ROK Resources (TSXV:ROK) | 17.6% | 130% |
| Propel Holdings (TSX:PRL) | 25.7% | 39.7% |
| Hammond Power Solutions (TSX:HPS.A) | 27.1% | 32% |
| Firan Technology Group (TSX:FTG) | 12.6% | 22% |
| Electrovaya (TSX:ELVA) | 34.9% | 47.9% |
| Cizzle Brands (NEOE:CZZL) | 13.2% | 90.4% |
| CEMATRIX (TSX:CEMX) | 10.7% | 28.9% |
| Cambria Gold Mines (TSXV:CAMB) | 12% | 85.6% |
| Aritzia (TSX:ATZ) | 16.2% | 20.3% |
| Allied Gold (TSX:AAUC) | 15.4% | 41.7% |
We're going to check out a few of the best picks from our screener tool.
Aritzia (TSX:ATZ)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Aritzia Inc., along with its subsidiaries, designs, develops, and sells apparel and accessories for women in the United States and Canada, with a market cap of CA$14.07 billion.
Operations: The company's revenue primarily comes from its apparel segment, which generated CA$3.99 billion.
Insider Ownership: 16.2%
Earnings Growth Forecast: 20.3% p.a.
Aritzia demonstrates strong growth potential with forecasted earnings growth of 20.3% annually, outpacing the Canadian market's 11.4%. Despite revenue growth expectations of 15.7% per year, which are below the 20% threshold, they still surpass the market average. Recent earnings showed significant improvement with Q1 sales at C$951 million and net income at C$117.26 million, up from C$663.32 million and C$42.39 million respectively a year ago, reflecting robust operational performance amidst moderate insider trading activity and strategic retail expansion plans in North America.
- Navigate through the intricacies of Aritzia with our comprehensive analyst estimates report here.
- Our expertly prepared valuation report Aritzia implies its share price may be lower than expected.
Cascades (TSX:CAS)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Cascades Inc., along with its subsidiaries, operates in the production, conversion, and marketing of packaging and tissue products across Canada and the United States, with a market cap of CA$1.73 billion.
Operations: The company's revenue segments consist of CA$1.61 billion from Tissue Papers and CA$3.04 billion from Packaging Products.
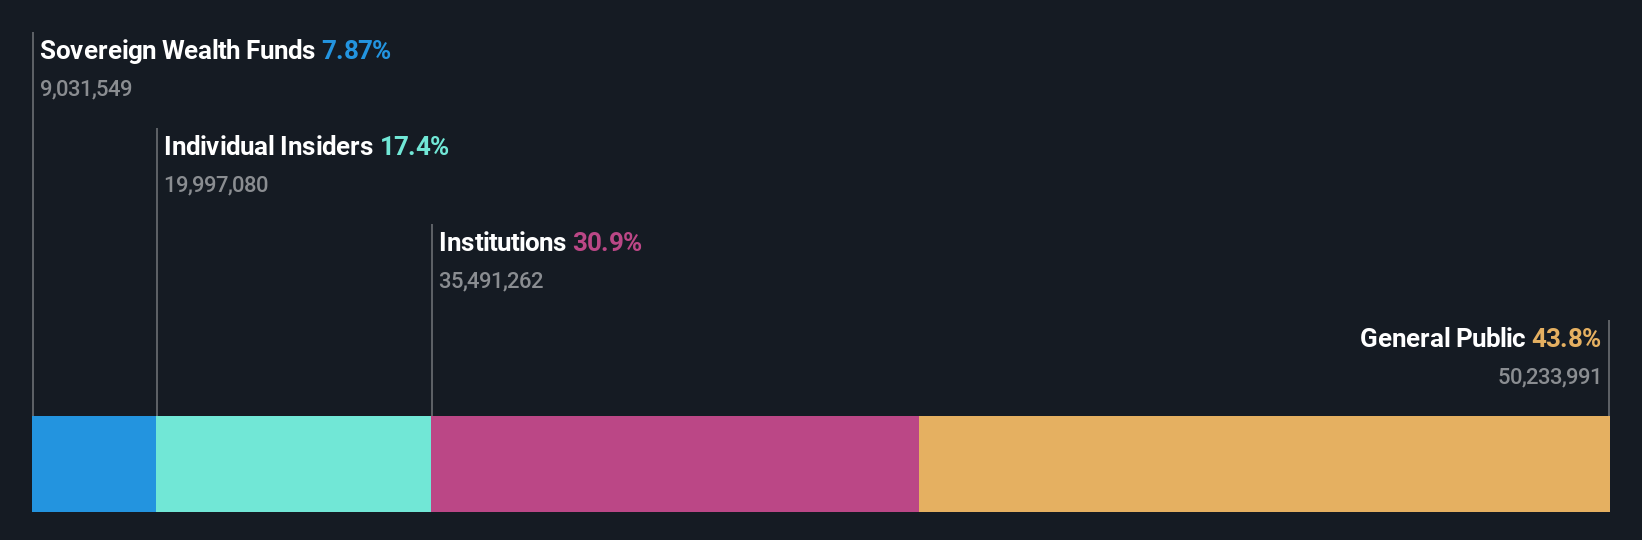
Insider Ownership: 23.7%
Earnings Growth Forecast: 34.7% p.a.
Cascades is poised for substantial earnings growth, with forecasts indicating a 34.7% annual increase, significantly outpacing the Canadian market's average. Despite revenue growth expectations of 4.9% per year being modest, they still exceed the market average. Recent financial results highlight a turnaround with Q2 sales reaching C$1.22 billion and net income at C$21 million from a loss previously. Strategic investments in production capacity underscore its commitment to long-term expansion and community engagement without significant recent insider trading activity.
- Take a closer look at Cascades' potential here in our earnings growth report.
- Our comprehensive valuation report raises the possibility that Cascades is priced lower than what may be justified by its financials.
ADF Group (TSX:DRX)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: ADF Group Inc. operates in the design and engineering of connections, including industrial coatings, across Canada and the United States with a market cap of CA$375.47 million.
Operations: The company generates CA$344.50 million in revenue from the non-residential construction industry.
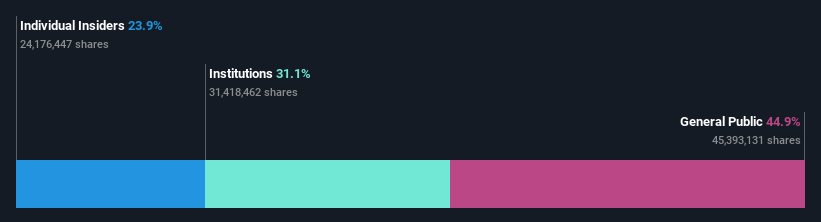
Insider Ownership: 28.3%
Earnings Growth Forecast: 50.4% p.a.
ADF Group's recent earnings report highlights robust growth, with Q2 sales reaching C$95.03 million, a significant increase from last year. Their strategic expansion projects in Quebec and the US, supported by substantial government financing and new contracts worth over C$280 million, aim to bolster production capacity. Despite a lower profit margin compared to last year, insider ownership remains high, aligning management interests with shareholders amid expected strong earnings growth of 50.4% annually over the next three years.
- Delve into the full analysis future growth report here for a deeper understanding of ADF Group.
- Our valuation report here indicates ADF Group may be undervalued.

Seize The Opportunity
- Get an in-depth perspective on all 49 Fast Growing TSX Companies With High Insider Ownership by using our screener here.
- Ready For A Different Approach? The end of cancer? These 34 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com