
Monolithic Power Systems Stock In Focus After Singapore Manufacturing Deal
- GlobalFoundries announced a long term manufacturing agreement with Monolithic Power Systems to deploy MPS process technology at its 300mm Singapore fab, targeting power management products for automotive, industrial automation, AI, and cloud infrastructure from early 2027.
- The agreement deepens Monolithic Power Systems' access to geographically diversified capacity, which matters for customers that want supply assurance in complex, high power electronics.
- We will now look at how Monolithic Power Systems' investment narrative may be reshaped by this expanded manufacturing capacity in Singapore.
Scan beyond Monolithic Power Systems and this GlobalFoundries deal by lining up other chip and power management players through our curated 89 AI infrastructure stocks.
Monolithic Power Systems Investment Narrative Recap
To own Monolithic Power Systems, you need to believe its exposure to AI data centers, automotive electrification, and broader power electronics continues to support healthy demand across multiple end markets. The latest GlobalFoundries Singapore expansion mainly reinforces that story by adding geographic diversity and future capacity, not by changing the near term operating picture in a big way.
In the short term, the key swing factor still appears to be execution on high power AI and data center design wins, given current expectations for revenue and earnings growth above 20% a year. The main risk remains margin pressure, with net profit margins currently below last year, particularly if costs tied to capacity, compliance, and product development keep rising.
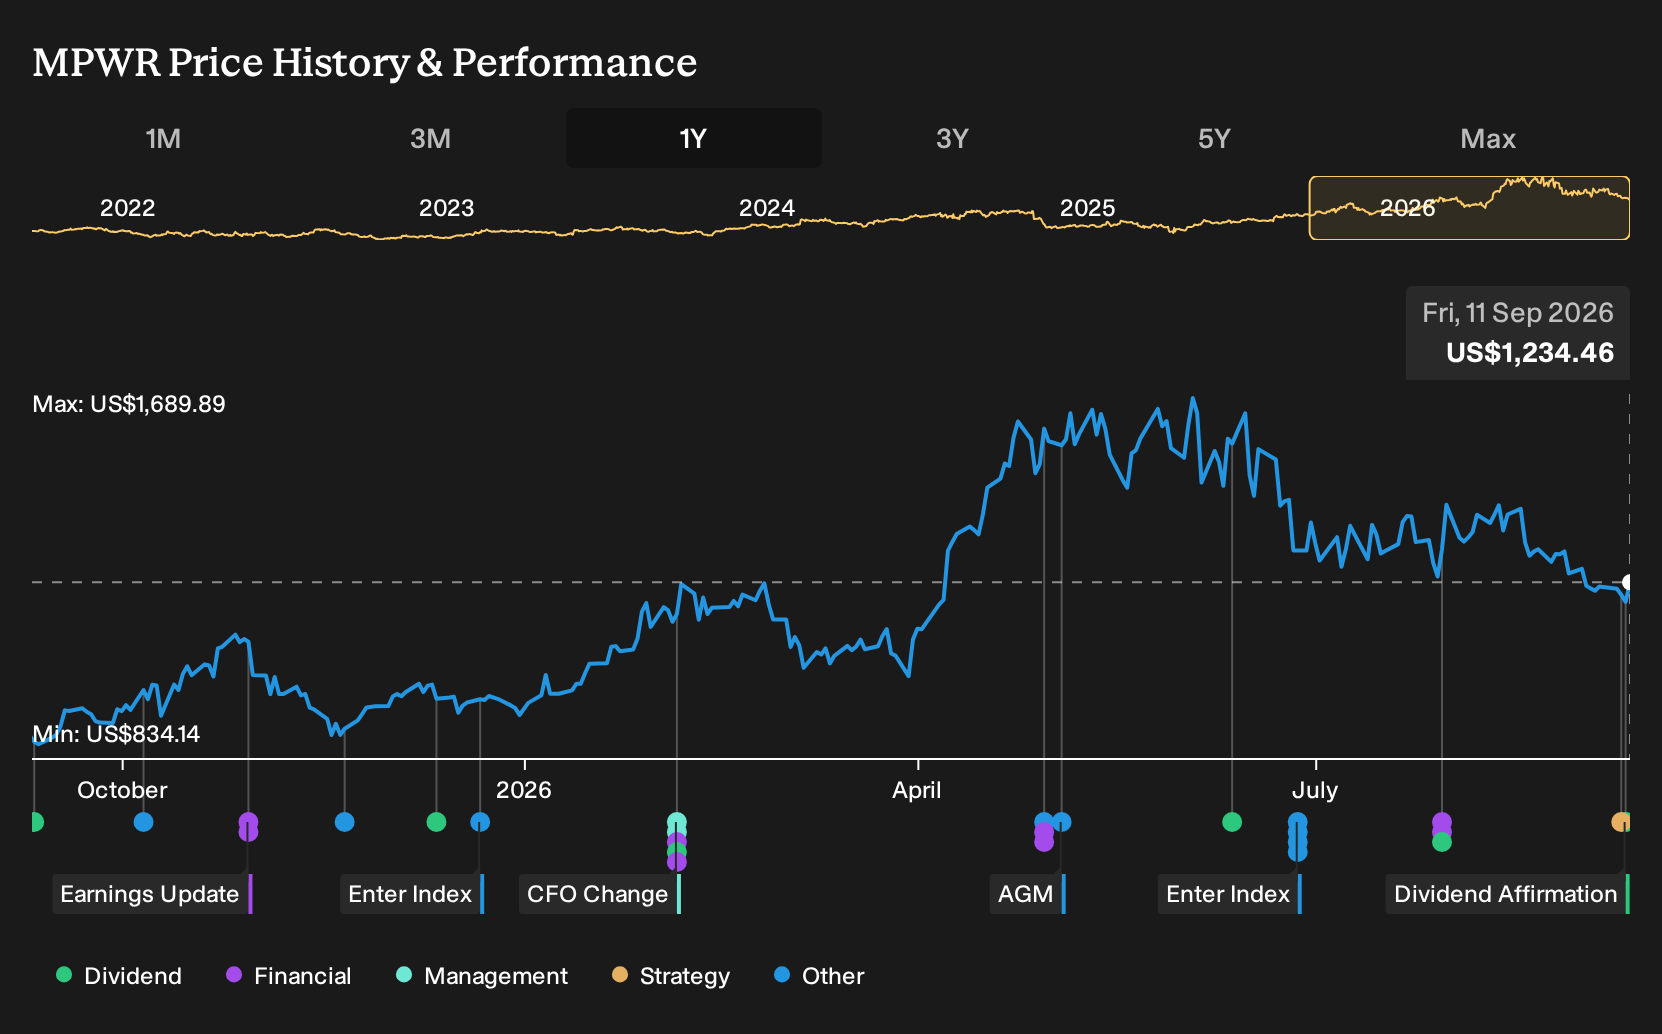
The fresh quarterly dividend of US$2.00 per share is the announcement that most directly matters for investors watching near term capital allocation. It indicates that Monolithic Power Systems is comfortable returning some cash while funding capacity agreements such as the GlobalFoundries deal and ongoing R&D for AI, auto, and industrial power products.
For potential catalysts, that payout sits alongside expectations of strong earnings and revenue growth. The risk is that richer dividends and high valuation multiples coincide with margin compression or softer ordering from AI, auto, or industrial customers. In that scenario, there would likely be more scrutiny on how consistently the business converts top line opportunities into durable free cash flow.
What The GlobalFoundries Deal Means For Monolithic Power Systems Forecasts
Analysts frame the Monolithic Power Systems story around aggressive top line expansion and heavier profitability, with the GlobalFoundries Singapore agreement viewed as one more way to support that pipeline. Forecasts point to revenue growth assumptions of 28.2% a year over the next three years, tied to AI data centers, automotive power, and industrial demand that need high efficiency power management at scale. Those same models bake in a move in net margins from 24.5% today to 29.8% in three years, which implies that future manufacturing and R&D spending is expected to be more than offset by mix and operating leverage.
On earnings, the consensus view lines up around US$801.9 million today and US$2.1b by 2029, with a spread from US$1.7b to US$2.4b that highlights how sensitive forecasts are to AI server buildouts and electric vehicle platforms. That path from roughly US$802 million to US$2.1b implies earnings would need to roughly 2.6x over the period, even before considering the projected 2.58% annual increase in shares outstanding. Investors weighing the expanded Singapore capacity will likely ask whether the incremental resilience and design win potential are enough to support that kind of step up in profit power without eroding the higher margin profile currently embedded in expectations.
Valuation work in the consensus report ties these operating targets to a 2029 revenue figure of US$6.9b and the same US$2.1b earnings number, assuming the stock trades on a P/E of 65.4x that year versus 74.7x today. That multiple is above the cited 45.9x for the wider US semiconductor group, which suggests the market is paying up for Monolithic Power Systems exposure to AI power delivery, auto content, and a differentiated product portfolio, not just for the extra wafer capacity in Singapore. The link back to GlobalFoundries is that geographic diversification and long term wafer access need to protect those earnings and revenue paths that are already priced in, rather than materially resetting the narrative on their own.
Monolithic Power Systems' narrative projects US$6.9b revenue and US$2.1b earnings by 2029, which assumes revenue growth of 28.2% a year and an earnings increase to roughly 2.6x the current US$801.9 million level.
Discover why Monolithic Power Systems' fair value points to a 49% potential upside compared with its current price, and why this gap could close quickly.
Exploring Other Perspectives
One alternate view says the real swing factor for Monolithic Power Systems is delayed silicon carbide and automotive ramps, not new fabs. Those more cautious analysts were penciling in 22.2% annual revenue growth and about US$1.7b in earnings by 2029 before this news. That is far below consensus. Use that spread as a prompt to explore multiple narratives, especially now that the GlobalFoundries deal and the reaffirmed US$2.00 dividend might eventually shift expectations.
Explore 4 other Monolithic Power Systems fair value estimates, including one that suggests as much as 30% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Monolithic Power Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Monolithic Power Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Monolithic Power Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Monolithic Power Systems?
If the GlobalFoundries agreement has you rethinking how you build exposure to power, chips, and cash generative businesses, use this as a chance to widen the aperture. The Simply Wall St Screener lets you scan for other stocks that fit your risk tolerance, income needs, and return goals in a more structured way than ad hoc ticker hunting.
- If you want quality and value to work together, start by reviewing a curated set of 32 high quality undervalued stocks that combine strong fundamentals with discounted pricing on key metrics.
- For readers who care most about resilience and capital protection, narrow the field to 11 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- Income focused investors can tilt toward cash returns by scanning a hand picked group of 6 dividend fortresses that offer higher yields while still being screened for financial health.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com