
What Just Happened With Builders FirstSource (BLDR)?
Builders FirstSource (BLDR) moved back into focus after Jim Cramer voiced caution on the stock following second quarter results that showed an 8.8% net sales decline and compressed profitability.
That caution has landed on a stock already under pressure, with Builders FirstSource trading at US$60.37 after a 1-day share price return of 2.37%. This only partially offsets a 30-day share price decline of 16.74% and a year-to-date share price fall of 42.30%.
Scan the construction space beyond Builders FirstSource by weighing it against a curated 32 high quality undervalued stocks that have been hit hard yet still pair solid cash generation with balance sheet strength.After a sharp reset in Builders FirstSource following softer sales and margins, the share price slump has already done some of the repricing work. Does the current valuation still compensate you for those risks, or not?
Most Popular Narrative: 25% Undervalued
At a last close of $60.37 versus a widely followed fair value of about $80.71, the current Builders FirstSource share price sits well below what the prevailing narrative models as justified on long run earnings power and cash generation.
The company is investing heavily in digital transformation and value-added solutions (e.g., digital tools, ERP integration, prefabricated components). These initiatives are expected to drive higher-margin growth, increase operating efficiency, and strengthen customer relationships as the market recovers, improving both future revenue and net margins.
See why 26 investors see Builders FirstSource as 25% undervalued.
Result: Fair Value of $80.71 (UNDERVALUED)
Still, if housing demand stays weak and commodity pricing remains volatile, the bullish narrative around Builders FirstSource could quickly lose credibility.
Find out about the key risks to this Builders FirstSource narrative.
Another View: Builders FirstSource On Earnings Multiples
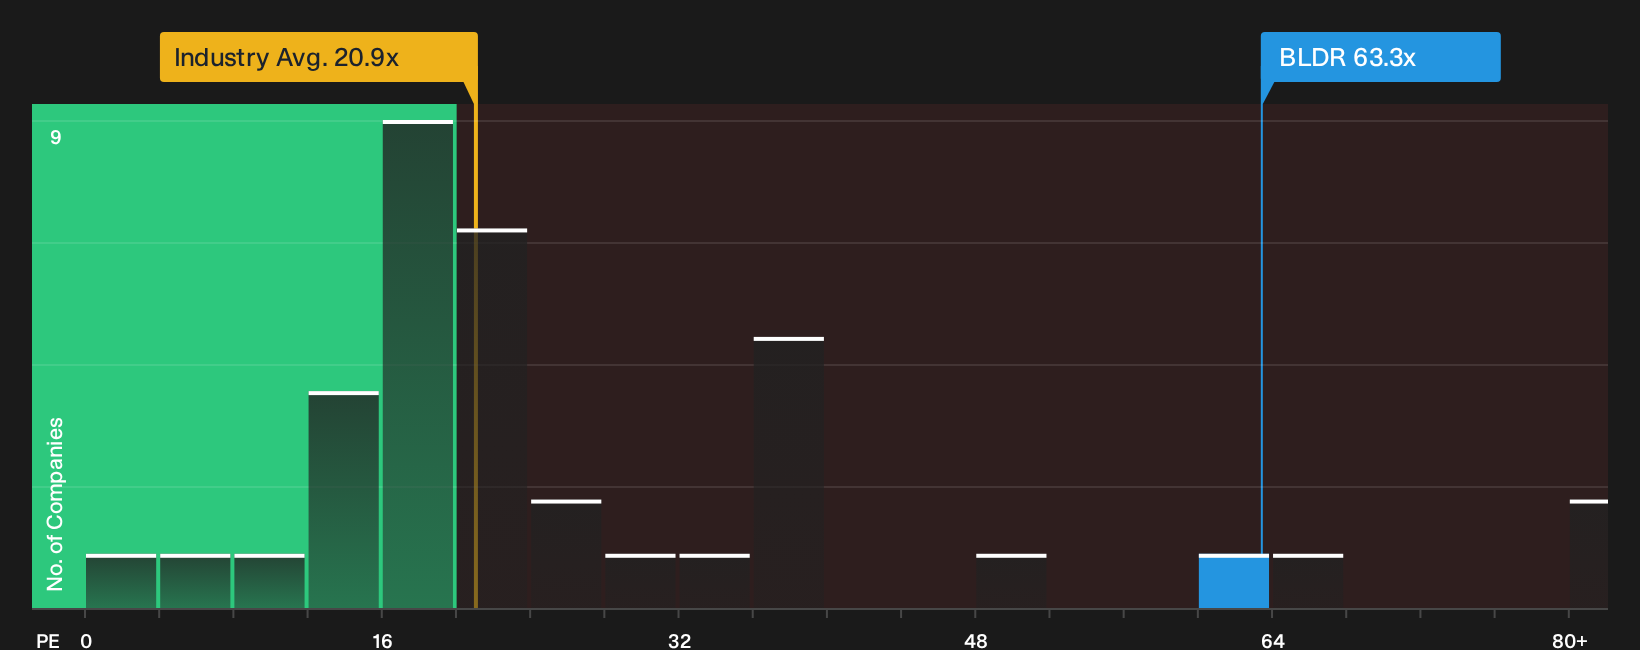
The first narrative paints Builders FirstSource as roughly 25% undervalued, yet the current P/E of 63.3x tells a very different story. That level is roughly 3x both the US Building industry at 20.9x and peers at 21.4x, and even slightly ahead of the 63x fair ratio.
In plain terms, the stock already prices in a lot of future earnings growth, which raises the risk that any disappointment in results or housing activity could hit the valuation hard. Is this a margin of safety, or a bet that everything has to go right for years?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like this only matter if you test them against the underlying numbers yourself and decide where you land. If you want a quick way to weigh both sides before you act, start with the 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Builders FirstSource?
Do not stop with Builders FirstSource alone. The best opportunities often show up where others are not looking, and you do not want to miss them.
- Target potential mispricings by scanning a 32 high quality undervalued stocks that combines strong cash generation with balance sheets built to handle tougher conditions.
- Prioritise resilience first and hunt within a 11 resilient stocks with low risk scores that filters for businesses with more durable financial profiles.
- Get ahead of the crowd by reviewing a 15 high quality undiscovered gems that highlights quality fundamentals before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com