
Why Did Everus Construction Group (ECG) Move Today?
Everus Construction Group (ECG) has reworked its main credit agreement by refinancing senior secured loans, expanding both term and revolving facilities, and securing lower borrowing spreads to support acquisitions and everyday funding needs.
Recent trading has been choppy for Everus Construction Group, with the share price up 3.64% over the last day and 1.86% over the past week, but down 15.33% over 30 days and 21.62% over 90 days. At the same time, the year-to-date share price return of 33.91% and 1-year total shareholder return of 50.71% indicate longer term momentum that remains firmly positive overall.
Spot opportunities around Everus Construction Group's refinancing story by checking a curated list of solid balance sheet and fundamentals (23 results) that could benefit from similar balance sheet flexibility.The refinancing story is clear; the valuation debate is not. Everus Construction Group trades well below analyst targets after a sharp pullback. Is that discount mispricing or a fair warning label on the stock’s risks?
Most Popular Narrative: 33% Undervalued
Everus Construction Group is currently at $119.42, while the most followed narrative anchors fair value at $177.60. This frames the refinancing story inside a wider earnings and backlog thesis built on power infrastructure and complex project demand.
Escalating power infrastructure needs tied to data centers, electric vehicles, industrial reshoring and undergrounding are supporting sustained T&D backlog growth and higher revenue visibility, reinforcing multi year revenue expansion.
Ongoing energy transition investments and utility commitments to grid hardening and substation upgrades are expanding Everus addressable market in renewables and T&D, contributing to an improving project pipeline and more resilient earnings across cycles.
See why 3 investors see Everus Construction Group as 33% undervalued.
Result: Fair Value of $177.60 (UNDERVALUED)
Still, the bullish narrative around Everus Construction Group leans heavily on continued data center build activity and smooth M&A integration. Both of these factors could disappoint and reset expectations.
Find out about the key risks to this Everus Construction Group narrative.
Another View On Everus Construction Group’s Valuation
That upbeat earnings and backlog story runs into a very different signal once the SWS DCF model is applied. On projected cash flows, Everus Construction Group screens as overvalued, with the current $119.42 share price sitting above an estimated future cash flow value of $83.27. It leaves you weighing how much faith to place in long term cash assumptions versus nearer term earnings strength.
Look into how the SWS DCF model arrives at its fair value.
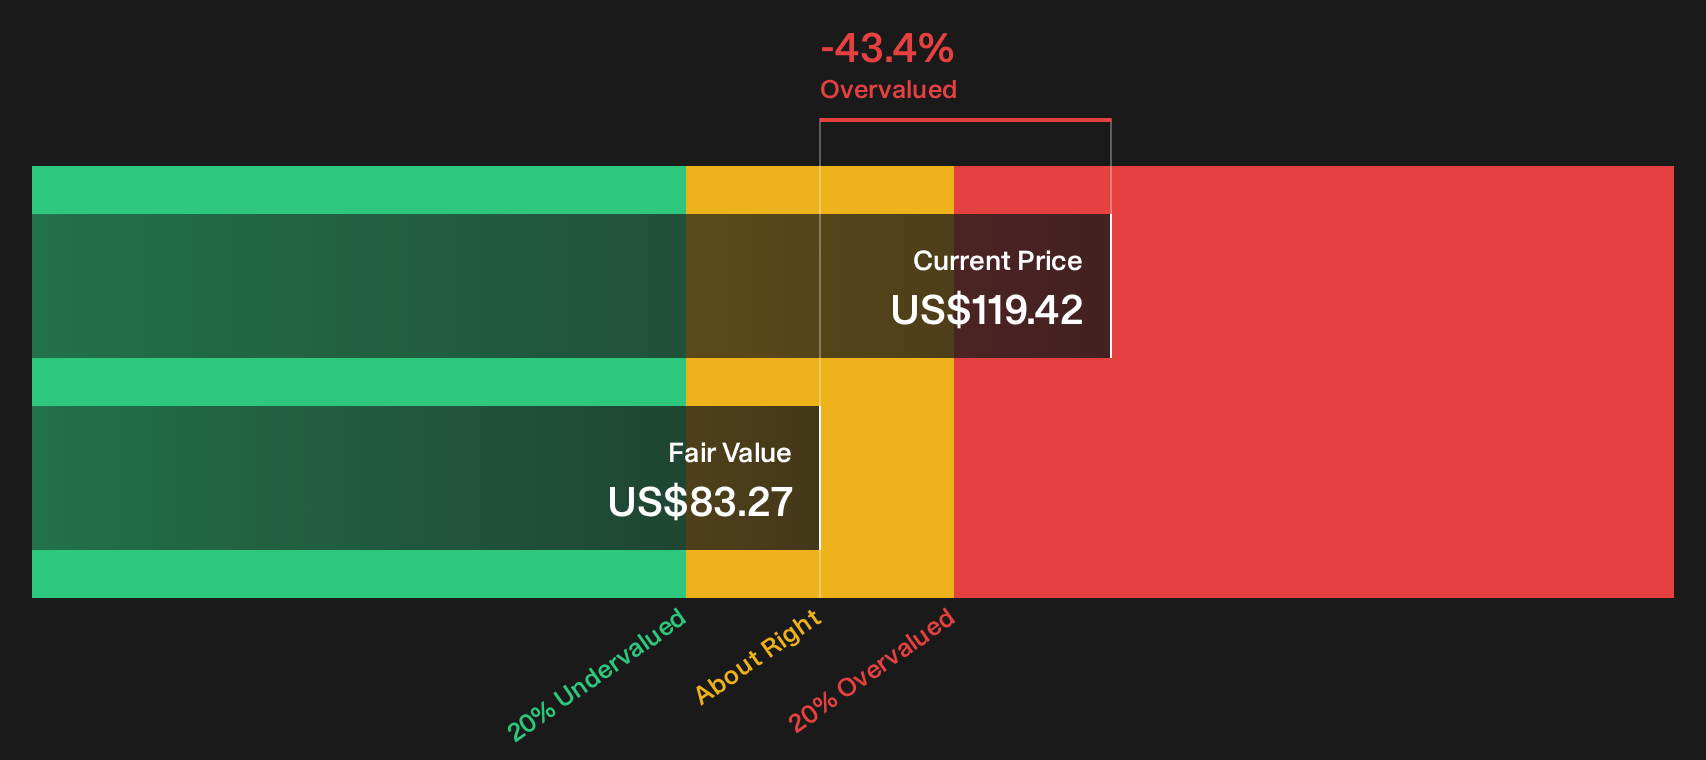
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Everus Construction Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Everus Construction Group is clearly split, which is exactly when fresh eyes on the numbers can matter most. If you want to weigh the tension between potential upside and the issues investors are worried about, start by digging into the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Everus Construction Group?
Do not stop at Everus Construction Group. Use the Simply Wall St screener to compare fresh ideas side by side and pressure test your own thesis.
- Target rock solid balance sheets by reviewing companies in the list of solid balance sheet and fundamentals (23 results) that combine funding strength with disciplined fundamentals.
- Hunt for potential mispricings by scanning the 32 high quality undervalued stocks where quality and pricing conditions may line up more attractively than you expect.
- Build a watchlist of future contenders by checking the 15 high quality undiscovered gems that rarely appear in headlines but still show robust underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com