
3 Stocks Estimated To Be Priced Below Their Intrinsic Value In September 2026
In the last week, the United States market has remained flat, yet it has achieved a 14% increase over the past year with earnings forecasted to grow by 17% annually. In this environment of steady growth, identifying stocks that are priced below their intrinsic value can present unique opportunities for investors seeking to capitalize on potential long-term gains.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Valley National Bancorp (VLY) | $13.80 | $27.10 | 49.1% |
| Pegasystems (PEGA) | $36.24 | $70.56 | 48.6% |
| Northeast Bank (NBN) | $132.64 | $247.02 | 46.3% |
| Insulet (PODD) | $131.96 | $243.56 | 45.8% |
| Futu Holdings (FUTU) | $112.73 | $210.89 | 46.5% |
| Civista Bancshares (CIVB) | $27.44 | $53.11 | 48.3% |
| Chagee Holdings (CHA) | $12.24 | $22.48 | 45.6% |
| Capital Bancorp (CBNK) | $36.25 | $66.81 | 45.7% |
| Autodesk (ADSK) | $212.40 | $414.93 | 48.8% |
| Addus HomeCare (ADUS) | $117.09 | $226.18 | 48.2% |
Let's take a closer look at a couple of our picks from the screened companies.
ChoiceOne Financial Services (COFS)
Overview: ChoiceOne Financial Services, Inc. is the bank holding company for ChoiceOne Bank, offering a range of banking services in Michigan with a market cap of $509.24 million.
Operations: ChoiceOne Bank generates revenue of $169.92 million from its banking services in Michigan.
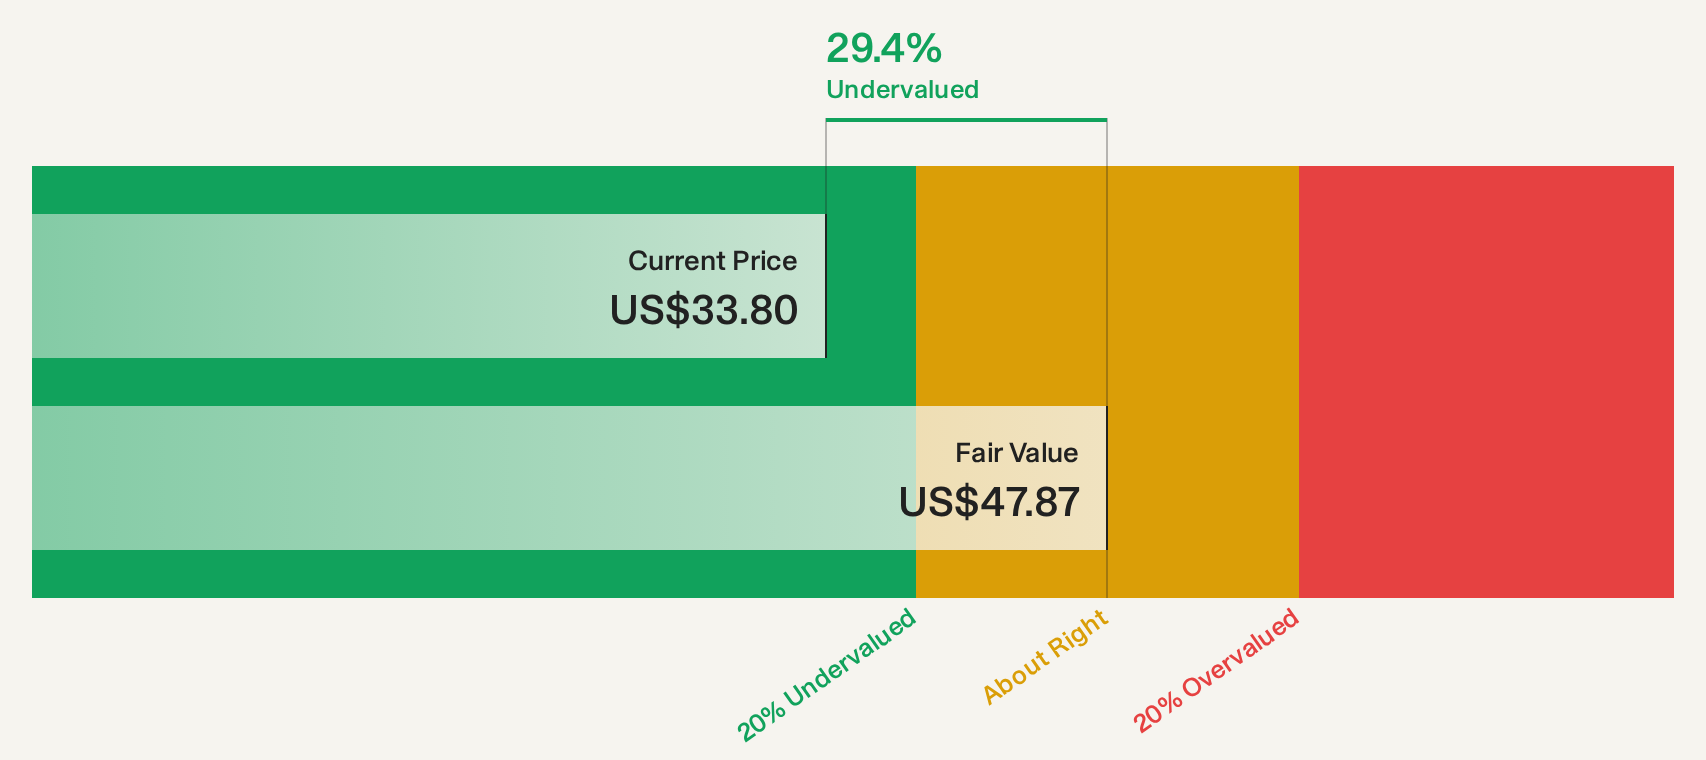
Estimated Discount To Fair Value: 28.6%
ChoiceOne Financial Services is trading at a significant discount to its estimated future cash flow value of US$47.68, currently priced at US$34.05. Despite slower forecasted revenue growth of 4.4% per year compared to the market, the company offers good relative value within its industry and pays a reliable dividend of 3.41%. Recent earnings indicate improved profitability with net income for the first half reaching US$26.17 million, reversing last year's losses, alongside ongoing share buybacks enhancing shareholder value.
- Our earnings growth report unveils the potential for significant increases in ChoiceOne Financial Services' future results.
- Click here to discover the nuances of ChoiceOne Financial Services with our detailed financial health report.
Primis Financial (FRST)
Overview: Primis Financial Corp., with a market cap of $399.47 million, operates as the bank holding company for Primis Bank, offering a range of financial services to individuals and small to medium-sized businesses in the United States.
Operations: The company's revenue is primarily generated through its segments, with Primis Bank contributing $168.96 million and Primis Mortgage adding $51.26 million.
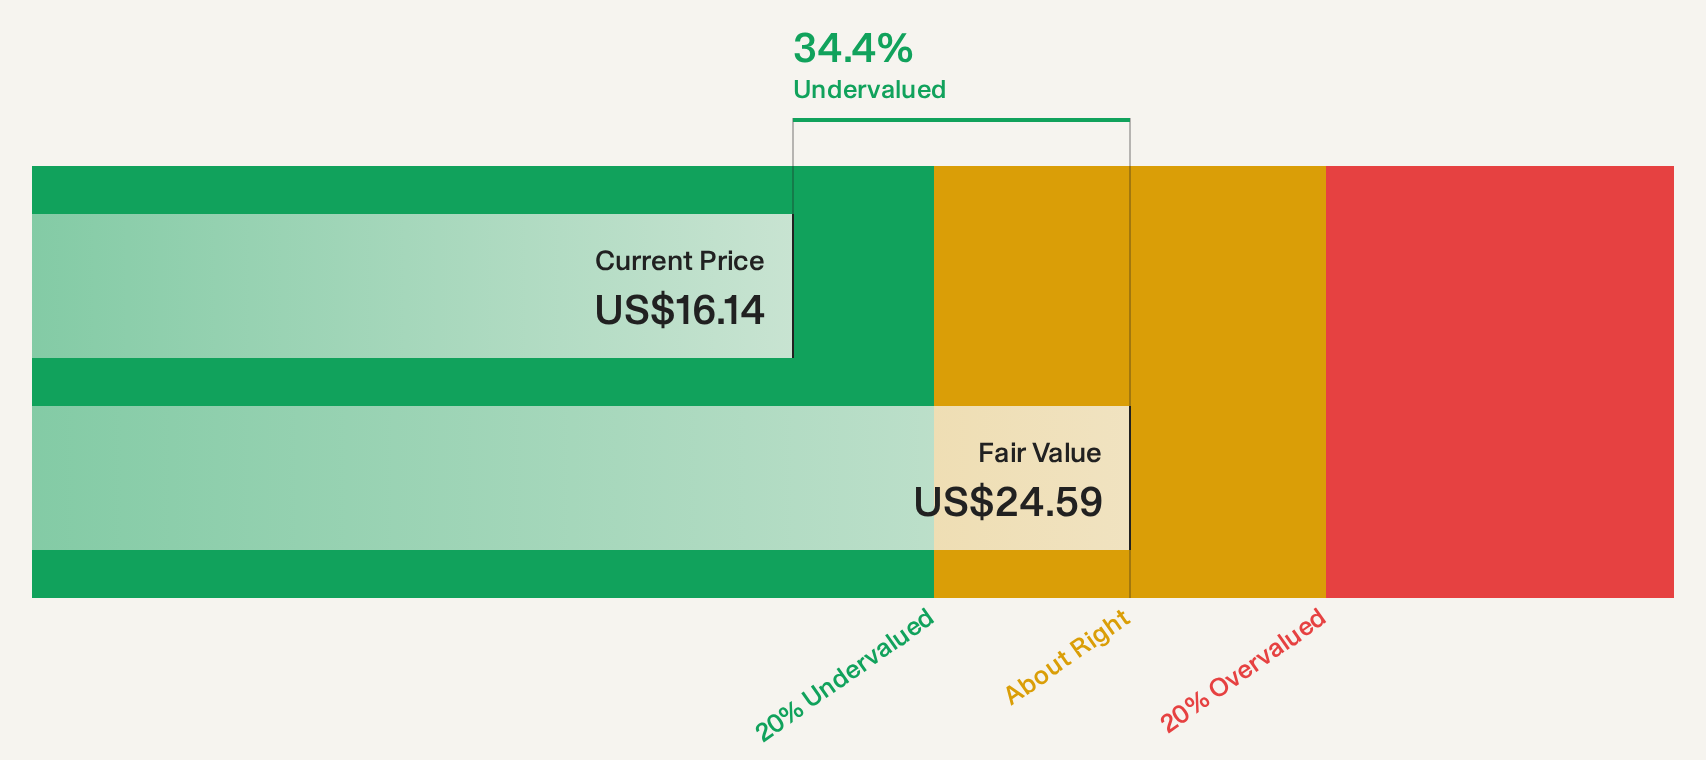
Estimated Discount To Fair Value: 34.2%
Primis Financial is trading at a notable discount to its estimated future cash flow value of US$24.56, with a current price of US$16.15. Despite strong past earnings growth, the company faces challenges with forecasted declines in revenue and earnings over the next three years. The dividend track record appears unstable, and recent executive changes may impact strategic direction. Nonetheless, Primis's low valuation relative to cash flows could attract investors seeking undervalued opportunities.
- According our earnings growth report, there's an indication that Primis Financial might be ready to expand.
- Click to explore a detailed breakdown of our findings in Primis Financial's balance sheet health report.
Northeast Bank (NBN)
Overview: Northeast Bank offers a range of banking services to both individual and corporate clients in Maine, with a market cap of $1.14 billion.
Operations: The company generates $236.96 million in revenue from its banking services provided to individual and corporate customers in Maine.
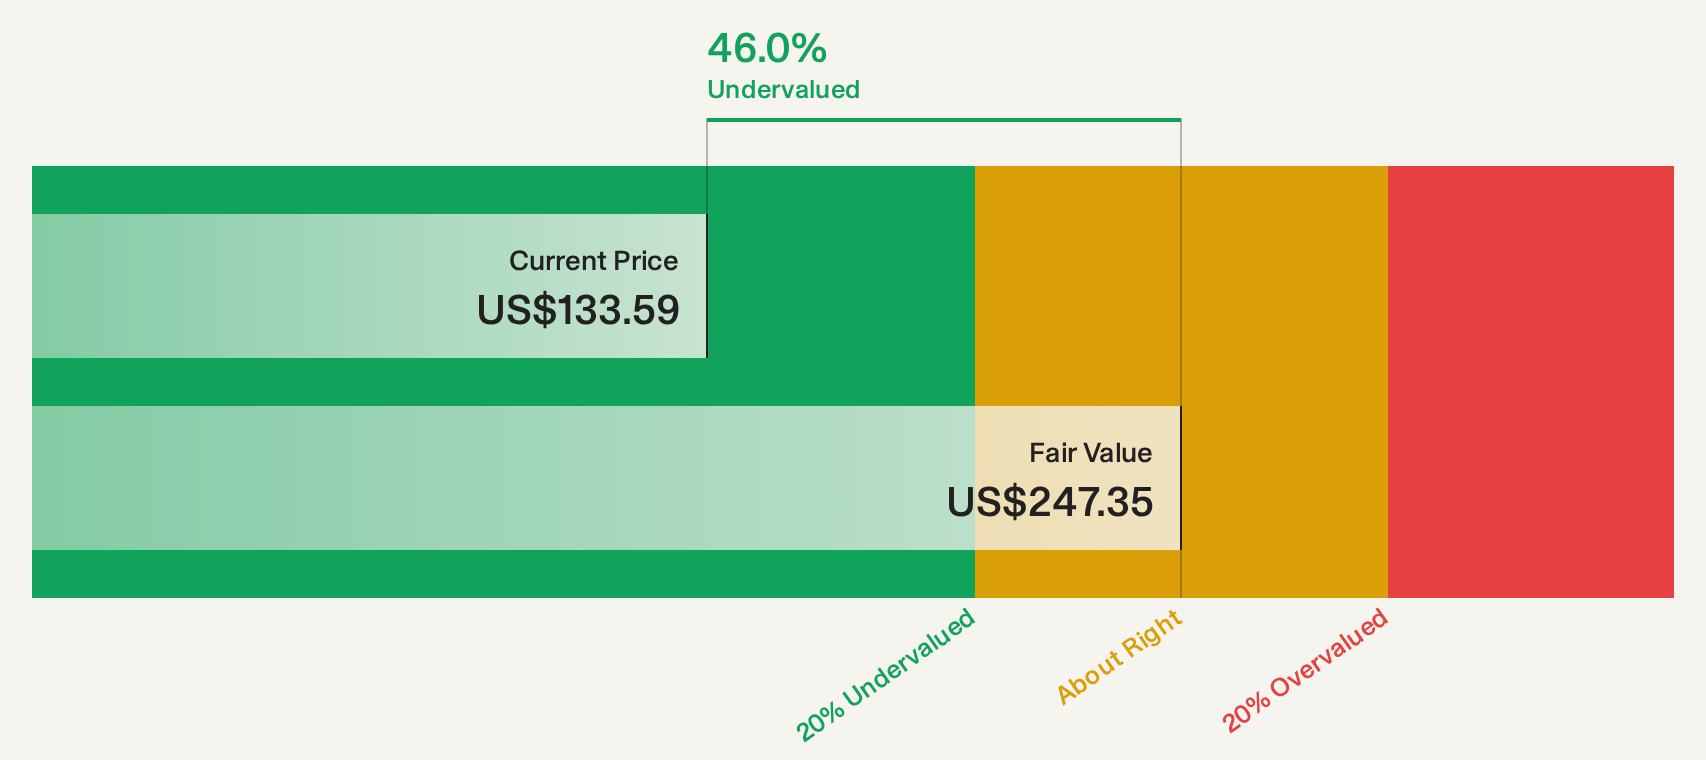
Estimated Discount To Fair Value: 46.3%
Northeast Bank is trading significantly below its estimated fair value, with a current price of $132.64 against a future cash flow value of $247.02. Despite recent earnings growth of 28.8% and increased net interest income, the forecasted annual profit growth is modest at 10.7%, lagging behind the broader U.S. market's expectations. While recent net charge-offs slightly increased, the bank maintains good relative value compared to peers, potentially appealing to investors focused on undervalued stocks based on cash flows.
- Upon reviewing our latest growth report, Northeast Bank's projected financial performance appears quite optimistic.
- Unlock comprehensive insights into our analysis of Northeast Bank stock in this financial health report.
Taking Advantage
- Embark on your investment journey to our 46 Undervalued US Stocks Based On Cash Flows selection here.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com