
Shimizu (TSE:1803) Could Be Fully Valued Following Its $139m Georgia Real Estate Push
Shimizu (TSE:1803) just stepped into a new corner of US real estate by partnering with Kennedy Wilson on a $139m luxury multifamily project in Sandy Springs, Georgia, near key Atlanta job hubs.
Recent trading has been choppy for Shimizu, with the share price slipping over the past quarter and year to date even as the 1-year total shareholder return is 13.97% and the 5-year total shareholder return is more than triple. That mix of shorter term share price weakness and very strong multi year total shareholder returns sets the backdrop for how investors may read this new US real estate project, either as a fresh driver of growth potential or as an added layer of execution risk on an already well rewarded stock.
Scan opportunities related to Shimizu's US expansion theme by comparing it with our curated list of solid balance sheet and fundamentals (19 results).
Given that backdrop of strong long term returns but recent share price softness, plus a fresh US real estate commitment, does Shimizu still offer a favourable risk reward at ¥2,378, or has the easy upside already been earned?
Price-to-Earnings of 9.5x: Is it justified for Shimizu?
On a simple snapshot, Shimizu trades on a P/E of 9.5x at ¥2,378, which looks inexpensive beside both the broader JP market and its Construction peers.
The P/E ratio compares the current share price to earnings per share. For a builder and engineering group like Shimizu, it captures how much investors are paying for each unit of current profit. For capital heavy contractors, this measure often reflects how confident the market feels about the durability of order books and profit margins through future project cycles.
Recent numbers show earnings growth of 128.5% over the past year and profit margins at 8.1% compared with 3.8% a year ago, helped by a very large one off gain of ¥81.5b. That kind of boost can flatter the denominator in the P/E equation, which can make the current 9.5x multiple look lower than it might appear on underlying, recurring profits alone.
Against that backdrop, the market is valuing Shimizu at 9.5x earnings while the JP Construction industry average sits at 10.8x and the peer group average is 12.5x. The estimated fair P/E for the stock is 15x, which is materially higher than where it trades today and indicates that, if earnings normalise toward that fair level, the valuation multiple may have scope to adjust.
Explore the SWS fair ratio for Shimizu.
Result: Price-to-Earnings of 9.5x (UNDERVALUED).
Still, the earnings jump leans heavily on that one-off ¥81.5b gain, and fresh US real estate exposure adds project and execution risk if conditions turn.
Find out about the key risks to this Shimizu narrative.
Another View, Shimizu Through A Cash Flow Lens
There is a different signal once you switch from earnings multiples to our DCF model. Shimizu at ¥2,378 is trading slightly above an estimated future cash flow value of ¥2,267.32, so on this measure the shares look a bit overvalued rather than cheap. That gap is not huge, but it does raise the question of whether recent earnings and the P/E are giving a cleaner picture than long term cash generation.
Look into how the SWS DCF model arrives at its fair value.
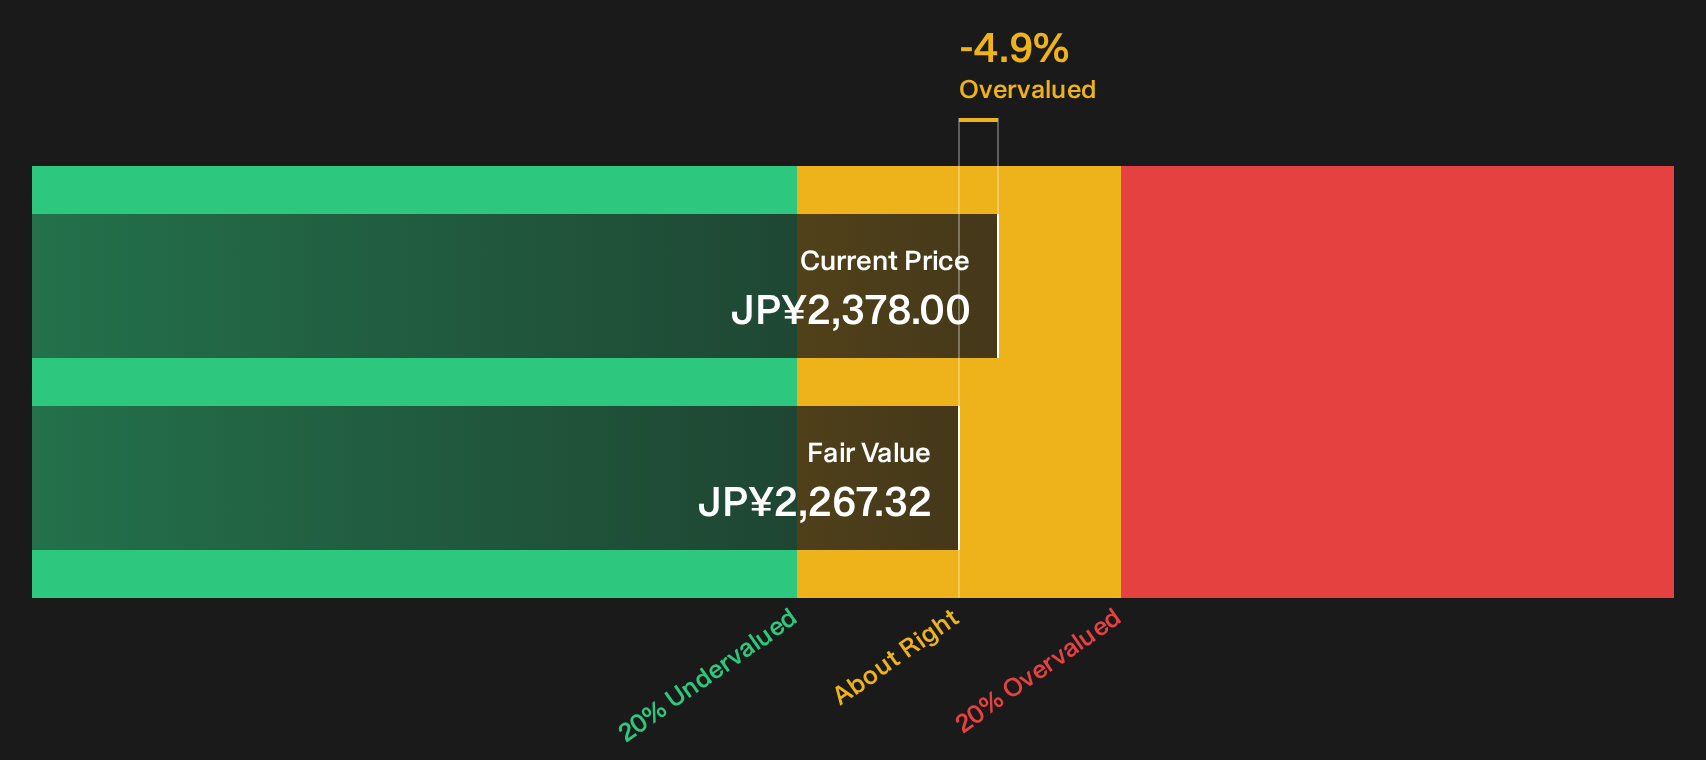
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shimizu for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Shimizu so far, right. If you want to move quickly and build your own stance from the underlying data, it helps to see both sides clearly through 4 key rewards and 3 important warning signs.
Looking for more Shimizu investment ideas?
If you want to pressure test your view on Shimizu and avoid leaving good ideas on the table, broaden your watchlist with a few focused screens.
- Target sturdier balance sheets and fewer unwanted surprises by scanning our curated universe through 12 resilient stocks with low risk scores.
- Hunt for quality at a sensible price by checking companies that screen well using 74 high quality undiscovered gems.
- Zero in on potential value candidates that pair fundamentals with appealing pricing by sorting stocks through 17 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com