
3 Dividend Stocks To Watch As Markets Turn Defensive
Markets are setting up for a rough open, with index futures softer, oil above $100 and rate hike odds high, yet the S&P 500 sits near record territory. Income investors watching dividends and capital preservation now face a real fork in the road. This article examines three large cap dividend payers exposed to these macro shocks and explains how today’s crosscurrents could affect their appeal.
The handful of dividend stocks highlighted below are only a sample, while the full screen surfaced 23 more large cap income plays with equally compelling narratives that are not covered here. If you want to go straight to the source, use the Defensive U.S. Large‑Cap Dividend Payers screener to identify, filter, and analyze the defensive dividend ideas that best fit your risk profile.
Abbott Laboratories (ABT)
Abbott Laboratories fits this defensive dividend screen as a large healthcare group whose cash flows are spread across everyday medical needs rather than discretionary spending. That can matter when rates, oil and headline risk are all pushing markets around.
Abbott Laboratories is a diversified healthcare business spanning diagnostics, medical devices, nutrition and established branded pharmaceuticals, with revenue spread across Medical Devices at about US$22.5b, Diagnostics at roughly US$10.0b, Nutrition at around US$8.3b and Established Pharmaceuticals near US$5.8b, underpinned by a market value around US$176.4b.
"The expansion of healthcare access and rising middle class in key emerging markets (such as India, China, Latin America, and the Middle East) is fueling robust growth in branded generics and biosimilars, highlighted by Abbott's record sales in these regions and imminent biosimilar launches; this trend is poised to drive sustained double-digit top-line growth and greater geographic revenue diversification."
What matters next for Abbott Laboratories is how one unresolved pressure on profitability interacts with that growth engine investors are counting on.
That pressure point is exactly where the story gets interesting, so read the full narrative for Abbott Laboratories to see how Abbott Laboratories’ growth engine could be accelerating or masking emerging risks.

Lamb Weston Holdings (LW)
Lamb Weston Holdings offers a classic defensive staple for this dividend screen, supplying frozen potato products that feed everyday meals rather than discretionary treats, which can matter when rates, oil and consumer budgets all feel tighter.
Lamb Weston Holdings produces frozen potato products and appetizers for restaurants and retailers, fitting the screener as a large U.S. dividend payer with staple-like demand. The business generates about US$4.4b from North America and US$2.2b from International operations, on a market value near US$6.6b.
"The global expansion of QSRs and modernization of foodservice channels, especially in emerging markets, is creating new distribution opportunities for Lamb Weston. The company's focus on strategic investments in priority global markets positions it to capture this demand, potentially driving sustained volume growth and topline revenue expansion."
What really matters for Lamb Weston now is how one persistent squeeze on profitability interacts with that demand story income investors are relying on.
That profitability squeeze is exactly where things get interesting, so read the full narrative for Lamb Weston Holdings to see whether Lamb Weston’s expanding footprint is accelerating strength or quietly masking risk.

Medtronic (MDT)
Medtronic brings a global medical devices footprint to the Defensive U.S. Large Cap Dividend Payers theme, pairing non cyclical healthcare demand with a long dividend track record that can appeal to income focused investors when markets are stressed by rates and oil prices.
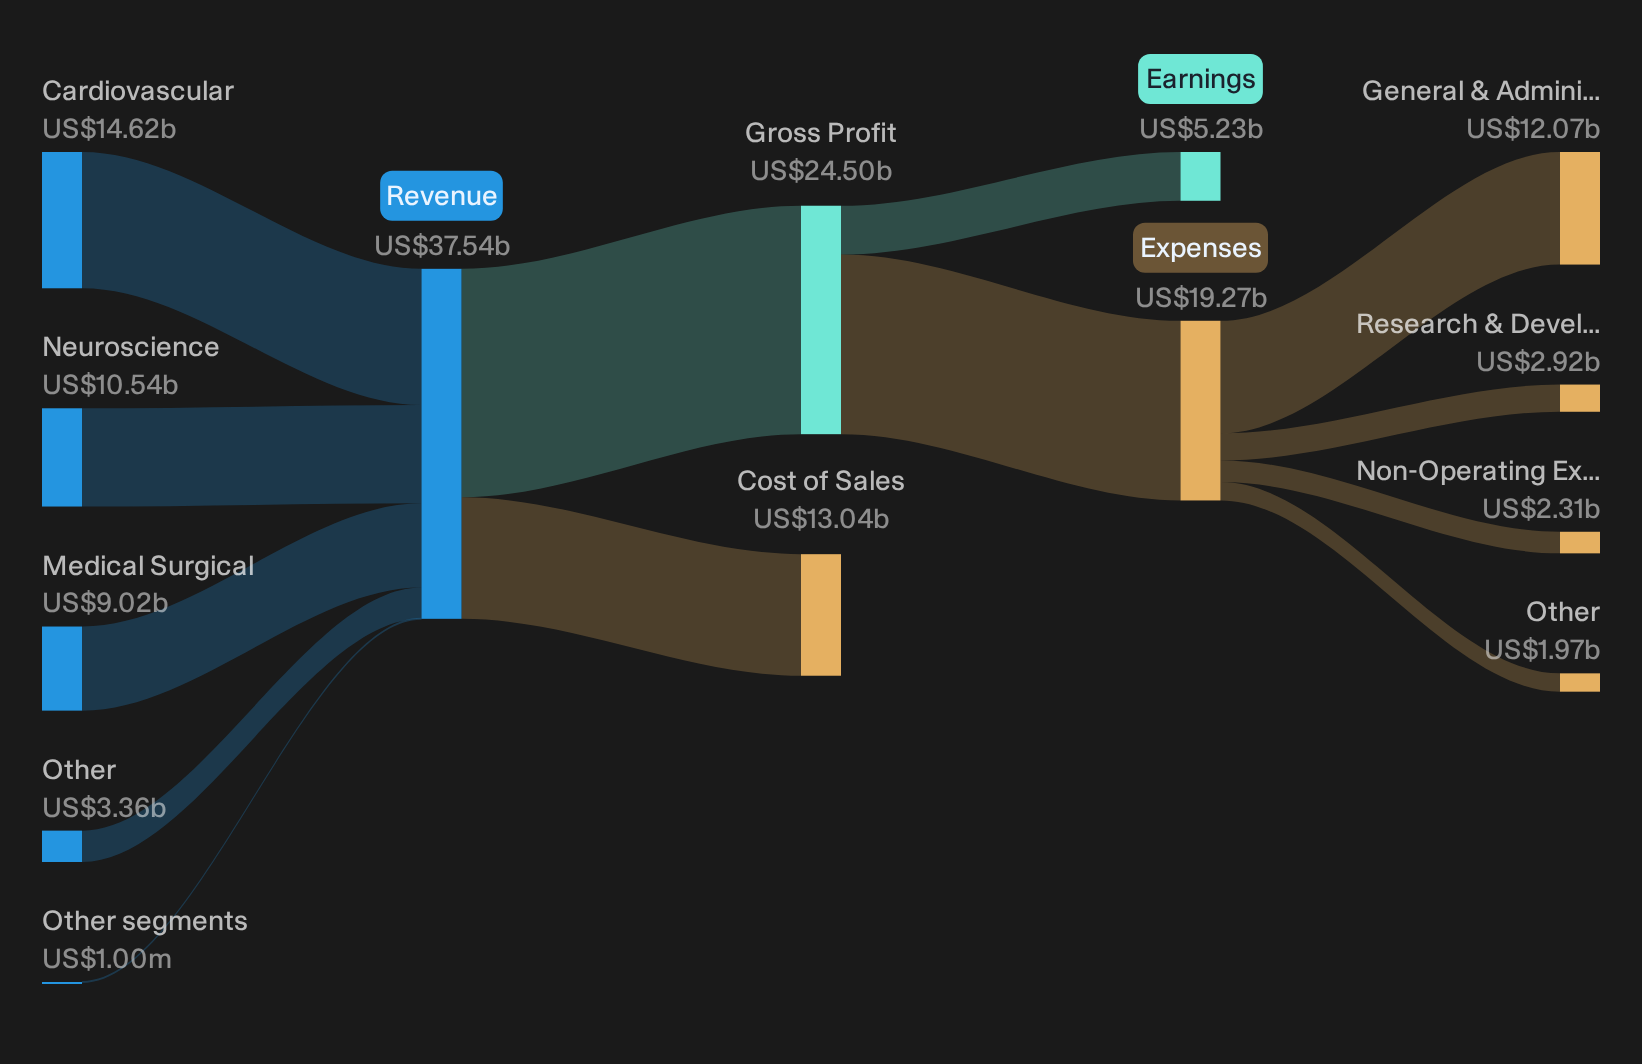
Medtronic develops medical devices across cardiovascular, neuroscience and medical surgical therapies, generating about US$14.6b from Cardiovascular, US$10.5b from Neuroscience, US$9.0b from Medical Surgical and US$3.4b from Other, and carries a market value near US$116.4b.
"Expansion in emerging and international markets, especially in cardiovascular and diabetes, continues to be robust, with double‑digit international growth in several segments, tapping into large underpenetrated populations and providing a durable runway for organic revenue gains."
The real test for Medtronic is how one quiet squeeze on profitability interacts with that growing international demand investors are watching closely.
That profitability squeeze is exactly where you should focus, so read the full narrative for Medtronic to see whether Medtronic’s international momentum is accelerating strengths or quietly masking pressure.
Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first. Breakout trends can gain momentum while many investors are still reacting to old headlines. Use these under-the-radar screeners before the crowd arrives and consider acting earlier in the process.
- Spot early strength in smaller, fast-moving businesses by running the 15 high quality undiscovered gems that filters for quality fundamentals before attention and expectations potentially increase.
- Explore momentum in the AI build-out by checking the 89 AI infrastructure stocks focused on companies involved with data centers, chips, and critical backbone hardware at earlier stages of adoption.
- Find ideas that may keep paying income even when prices move lower by reviewing the 6 dividend fortresses curated for income resilience and balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com