
Is Declining Revenue Altering The Investment Case For Revvity Stock (RVTY)?
- Revvity recently reported pressure on its business, with revenue declining and some customers pushing out purchases, which points to softer current demand.
- The combination of weaker top-line trends and rising regulatory scrutiny in healthcare raises questions about how Revvity balances growth initiatives with risk management.
- We will now look at how Revvity's investment narrative could be affected by declining revenue and postponed customer purchases.
Revvity Investment Narrative Recap
To own Revvity, you need to be comfortable with a story where lower current revenue and delayed customer orders are a setback, not a permanent reset. The short term hinge is whether demand in key diagnostics and life sciences markets stabilises enough for management to lean on its mix shift toward software, consumables and higher margin offerings.
The biggest immediate risk sits in the combination of softer volumes and rising regulatory scrutiny in healthcare. That pairing can pressure pricing and margins at the same time. If reimbursement changes or funding pressures deepen while orders stay slow, Revvity could face a tougher route to the margin profile analysts are modelling.
Recent commentary around regulatory pressure and weaker top line trends puts more focus on earlier catalysts the market had been watching. The most relevant piece is the push into higher growth software, particularly Signals. Analysts previously saw this segment growing above 30% with strong recurring revenue metrics and order momentum.
This software tilt matters because it can offset some demand volatility in instruments and diagnostics, as long as pharma and biotech customers keep prioritising digital tools. Any signs that delayed purchases are spilling into that software pipeline, or that regulatory and funding changes are hitting genomics contracts and diagnostics volumes, would directly affect how quickly Revvity can lean into that higher margin mix story.
Revvity’s current analyst script points to revenues of $3.4b and earnings of $554.4 million by 2029, based on an assumed 4.9% annual revenue growth rate and an earnings increase of about $317 million from $237.4 million today.
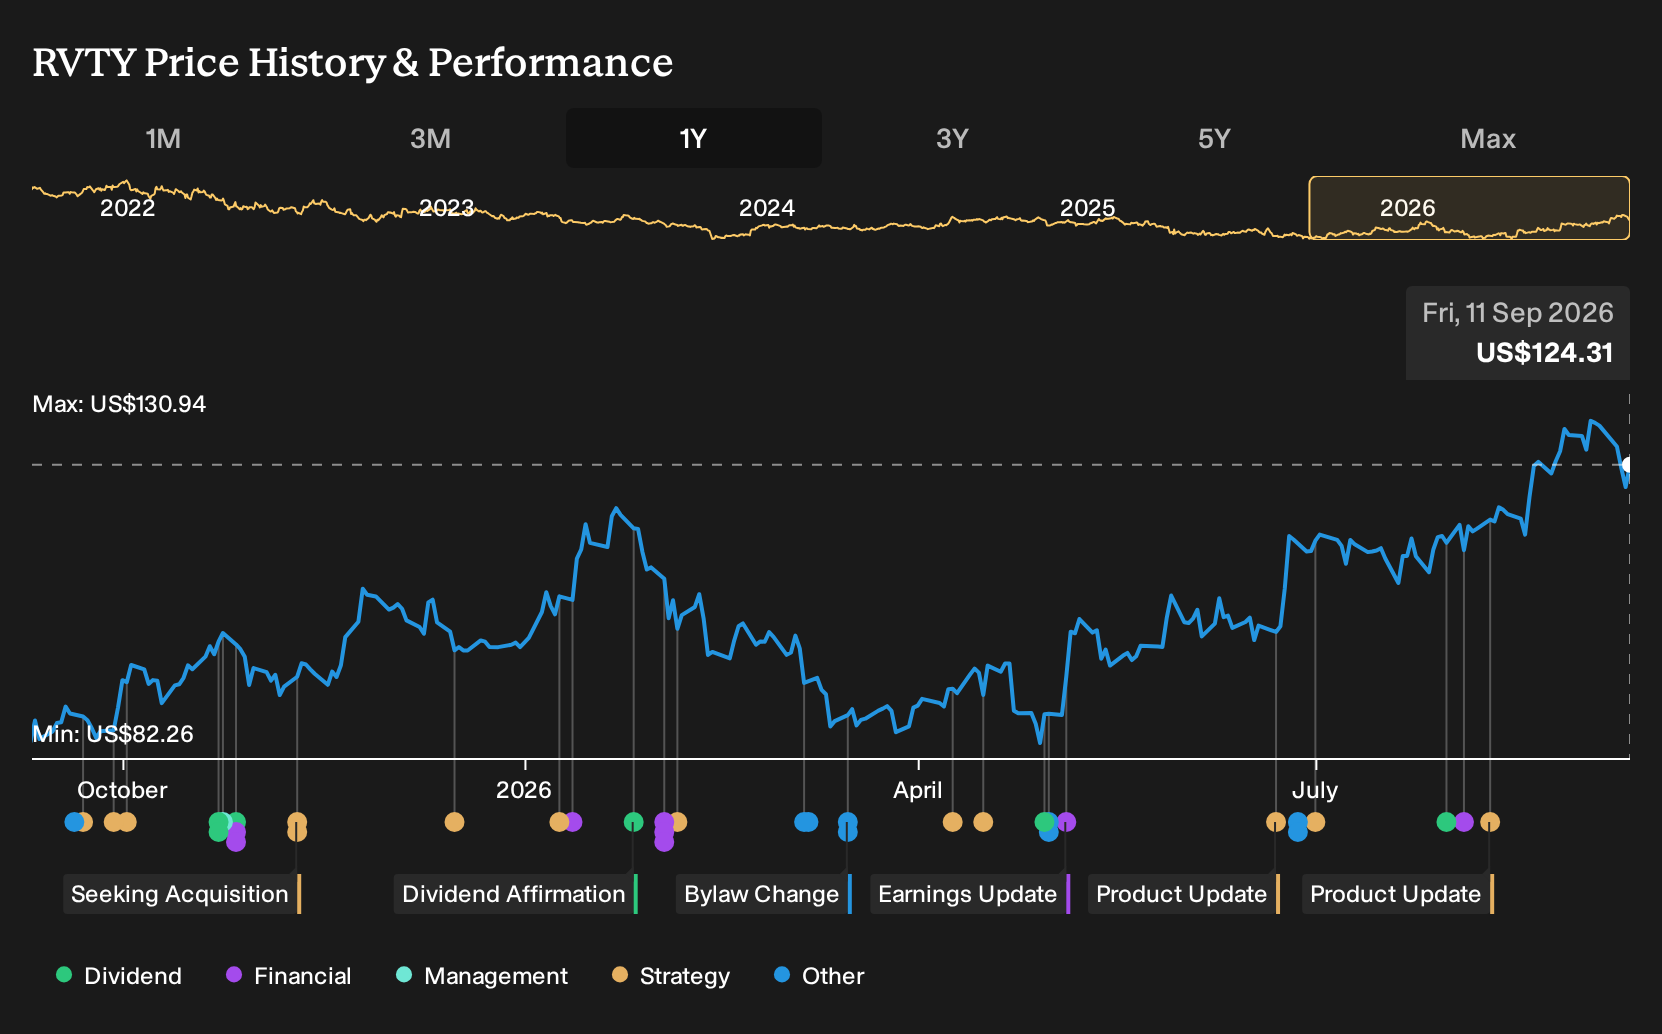
Uncover why Revvity's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For Revvity, the most cautious analysts were already focused on regulatory pressure in China, where they assumed revenue would reach about $3.2b and earnings around $360.3 million by 2029. That is far below the $3.4b and $554.4 million baseline. This more pessimistic script could shift further after the latest demand shock.
Explore 2 other Revvity fair value estimates, including one that suggests it could be worth just $121.07.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider your own research and judgment.
- A great starting point for your Revvity research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Revvity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Revvity's overall financial health at a glance.
Looking For More Ideas Beyond Revvity?
If Revvity feels finely balanced for your risk tolerance, it can help to widen the lens and compare it with other stocks that fit clear, rules based criteria using the Simply Wall St Screener.
- For investors who want income resilience, focus on businesses with robust payouts and balance sheets using 6 dividend fortresses that meet strict yield and stability filters.
- If capital preservation sits near the top of your checklist, narrow your search to companies with sturdier financial profiles through a targeted 11 resilient stocks with low risk scores that prioritises lower risk scores.
- For those hunting for under followed potential, cast a wider net across quality fundamentals by scanning a curated 15 high quality undiscovered gems that may not yet be crowded with attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com