
SpaceX Stock Is Positioned for Robust ARR Growth and EBITDA Margin Expansion
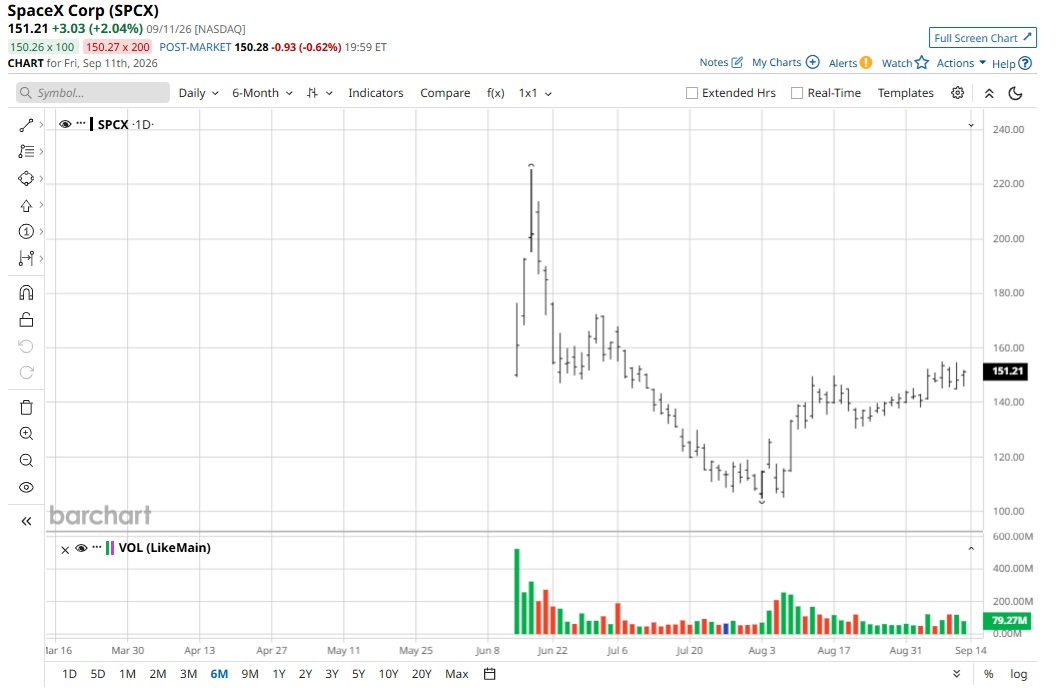
Judging by the volumes and price action, Space Exploration Technologies (SPCX) stock has moved from the phase of volatility and price discovery to a stage of consolidation. While a price-to-sales (P/S) of 105.9 might indicate stretched valuations, robust growth and innovation offset this concern.
Talking about growth, SpaceX CFO Bret Johnsen recently opined that the company had “gained greater conviction that it can reach a $100B annual revenue run rate.” Johnsen pointed out that SpaceX had signed a new deal to provide AI computing power to a customer worth $1.11 billion a month. This contract represents $13 billion in annualized revenue.
Another important plan that was discussed at the Goldman Sachs Communacopia + Technology Conference was SpaceX exploring orbital computing as a long-term opportunity.
With contracts that boost the company’s ARR coupled with innovation-driven growth plans, SpaceX remains attractive. It’s also worth noting that SpaceX ended Q2 with a cash buffer of $100 billion. This gives ample flexibility for aggressive organic growth, investment in R&D, and for opportunistic acquisitions like Cursor.
About SpaceX Stock
Headquartered in Starbase, Space Exploration Technologies is a $2 trillion market valuation company that provides satellite-based broadband services in the United States and internationally.
The company was founded with a mission to make systems and technologies necessary to make life multiplanetary. The company has secured a leadership position in the Space segment with launches that account for 80% of global mass to orbit since 2023.
SpaceX diversified into the Connectivity segment in 2020. Currently, SpaceX has the world’s largest and most advanced high-speed, low-latency satellite internet network. As of Q2 FY26, Starlink had 12 million subscribers with a presence in 164 countries.
SpaceX pursued another diversification in 2023 with entry into the high-growth artificial intelligence segment. In the first six months of 2026, capex in the AI business has been $23.6 billion.
Overall, with multiple growth engines, SpaceX has a bright outlook. While SPCX stock has remained volatile since listing, an uptrend seems likely with robust growth being the key catalyst.
EBITDA Margin Expansion Likely
For the first half of 2026, SpaceX reported total revenue of $12.5 billion and an adjusted EBITDA of $4.7 billion. This implies an adjusted EBITDA margin of 37.6%. However, there seems to be ample scope for EBITDA margin expansion and cash flow upside in the coming years.
To put things into perspective, the AI segment reported revenue of $1.5 billion for the first half of 2025. For the same period, the adjusted EBITDA loss was $387 million. For 1H FY26, revenue swelled to $3.4 billion with a positive adjusted EBITDA of $537 million. As the ARR swells, the segment is positioned for sustained improvement in adjusted EBITDA margin. It’s worth noting that the adjusted EBITDA margin for the connectivity business is already above 60%. As the AI segment revenue and EBITDA swells, cash flows will be attractive.
According to SpaceX, the total addressable market for all business segments is $6 trillion. However, if enterprise applications in the AI segment are included, the addressable market swells to $28.5 trillion. Even with a significantly conservative estimate (50% of the potential market), the addressable market is large enough to propel sustained growth. The long-term opportunity, therefore, makes SpaceX attractive.
What Do Analysts Say About SPCX Stock?
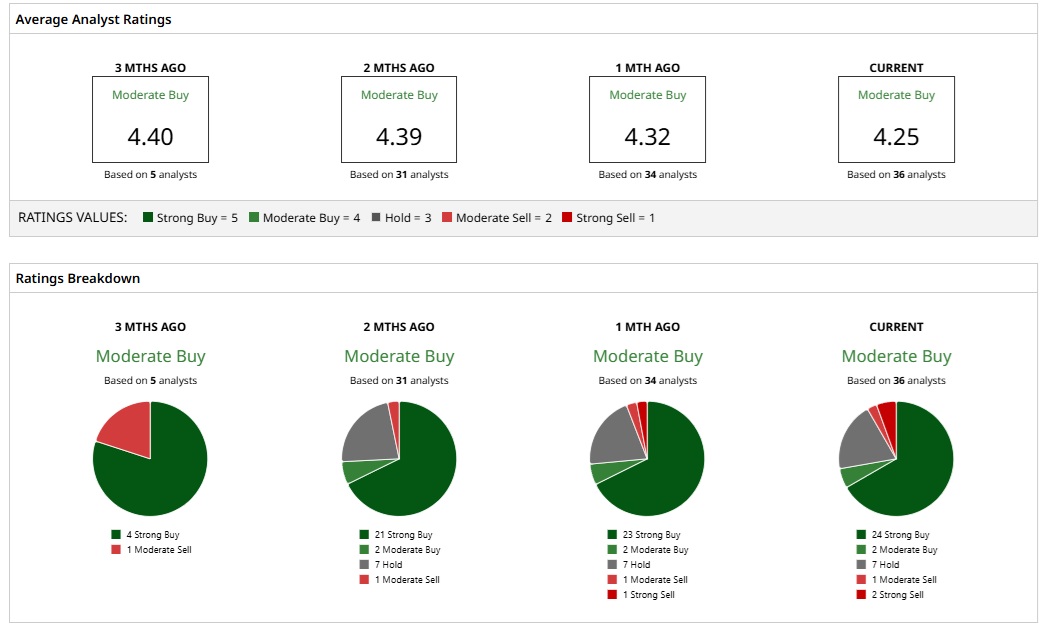
Based on 36 analysts with coverage, SPCX stock has a consensus “Moderate Buy” rating. While 24 analysts have a “Strong Buy” rating for the stock, two have a “Moderate Buy,” and seven have a “Hold” rating. Among the bears, one analyst has a “Moderate Sell” and two analysts have a “Strong Sell” rating.
The mean price target of $219.71 represents a potential upside of 45% from current levels. Further, the most bullish price target of $800 suggests that SPCX stock could climb as much as 429% from here.
On the date of publication, Faisal Humayun Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.