
FLSmidth (CPSE:FLS) Recasts Its Mining Model Following New Deals And A Value Debate
FLSmidth (CPSE:FLS) has put investors on alert with two fresh moves. A planned fourth business line and a new lifecycle agreement in India both reshape how the group serves mining clients.
Against that backdrop, FLSmidth’s share price has eased in the very short term, with a 1-day share price return of 2.79% and a 7-day return of 3.38%. However, the 30-day and year-to-date share price gains of 10.39% and 23.94% suggest momentum is still pointing higher. Over a longer horizon, total shareholder return of 28.64% over one year and 167.02% over five years indicates that investors who stayed in the stock through earlier cycles have so far been rewarded for backing the business through its ongoing reshaping of the mining portfolio and service model.
Compare FLSmidth’s reshaping of its mining flowsheet with other equipment and service specialists by scanning our curated list of 39 power grid technology and infrastructure stocks for potential portfolio candidates.
Fresh contracts and a fourth business line have pushed FLSmidth’s story forward. At about DKK 558 a share and trading below some valuation estimates, does the balance of risk and potential reward still lean toward buyers?
Most Popular Narrative: 10.5% Undervalued
FLSmidth’s most followed valuation story puts fair value at DKK 623.33, which sits above the last close at DKK 558 and frames the current pricing gap through the lens of a long term mining services transition and restructuring effort.
FLSmidth's focus on expanding its service and aftermarket business (which generates recurring, higher-margin revenue and is more resilient through cycles) positions it to grow net margins and earnings stability over time, especially as the company replicates practices from its high-growth, high-profitability PCV segment across its Service operation.
See why 9 investors see FLSmidth as 10% undervalued.
Result: Fair Value of DKK623.33 (UNDERVALUED)
Still, the FLSmidth narrative could be knocked off course if mining capex stays weaker for longer or if the shift toward services proves slower and costlier than analysts expect.
Find out about the key risks to this FLSmidth narrative.
Another View on FLSmidth’s Valuation
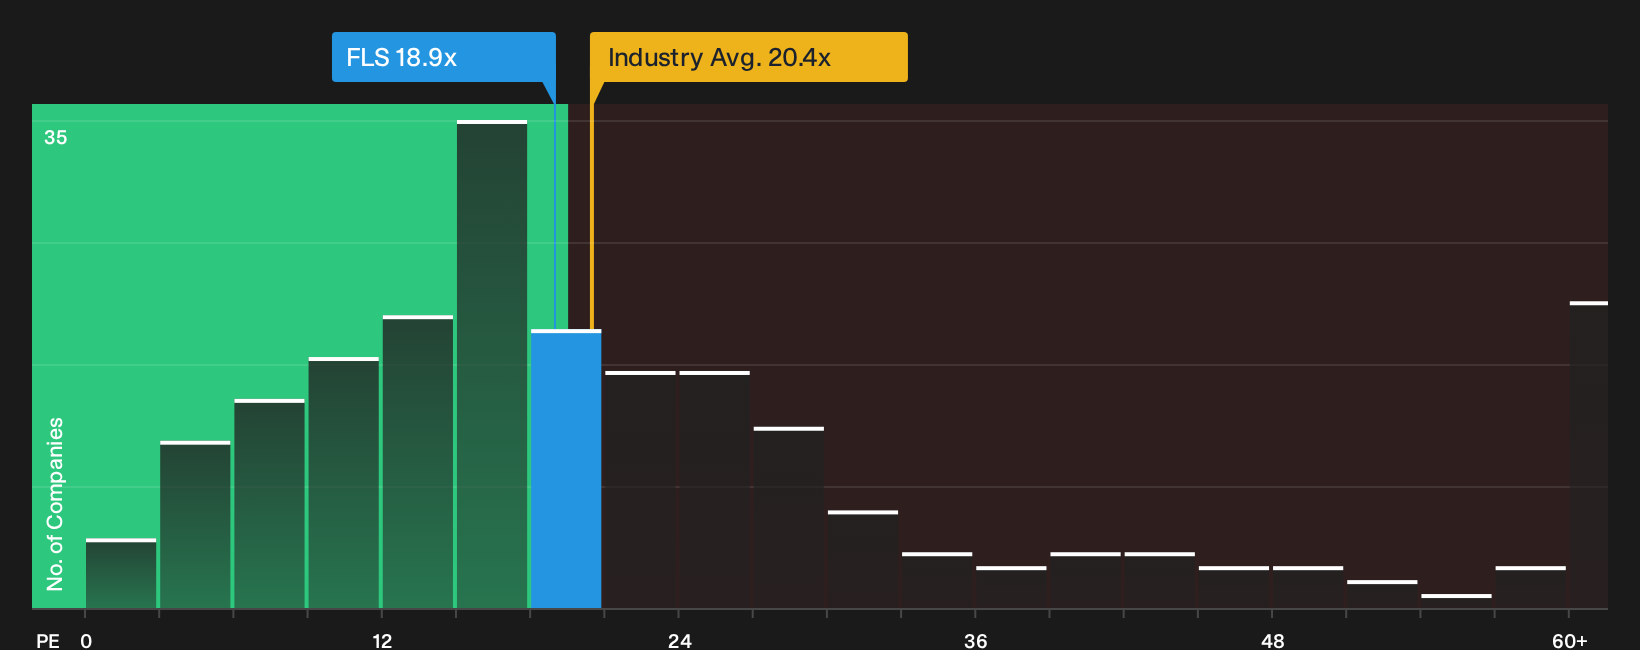
The popular story around FLSmidth leans on analyst targets and fair value of DKK623.33, which points to a 10.5% gap versus the DKK558 share price. On simple ratios though, the picture is less generous. The stock trades on a P/E of 18.9x, above a fair ratio of 13.9x, even if it is below the European Machinery average of 20.4x and the 27.7x peer group level. For investors, that mix suggests the market already prices in a decent amount of quality, so it is worth asking how much mispricing is really left on the table.
To test how much room that leaves at today’s levels, it is worth looking at the fuller valuation breakdown and how it treats earnings versus cash flows, capital intensity and cyclicality risk. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does FLSmidth’s setup feel balanced or stretched to you right now? Check the data for yourself, weigh the signals, then review the 3 key rewards and 1 important warning sign.
Looking for more FLSmidth-sized opportunities?
If FLSmidth has caught your eye, do not stop here. Broaden your watchlist with fresh ideas sourced from data driven stock screens tailored to different priorities.
- Target potential mispricing by scanning companies that score well on quality and value through the 188 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with robust finances using the list of solid balance sheet and fundamentals (194 results).
- Spot underfollowed opportunities before the crowd by reviewing the 616 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com