
Port of Tauranga (NZSE:POT) Could Be 32% Above Fair Value Following Expansion Approval
Port of Tauranga (NZSE:POT) has just cleared a key regulatory hurdle, with its Stella Passage expansion approved under New Zealand’s Fast-track Approvals Act 2024, subject to conditions and potential appeals.
Recent trading has been softer, with the share price down 3.6% over the past week and 3.2% over the past month to NZ$7.95. However, Port of Tauranga’s long-run total shareholder return of 49.3% over three years suggests underlying investor confidence remains in place.
Spot emerging port and infrastructure opportunities by aligning Port of Tauranga’s move with a curated group of 39 power grid technology and infrastructure stocks.Regulatory progress, softer recent trading and a long history on the NZX all pull Port of Tauranga in different directions. Does it make more sense to pay NZ$7.95 today, or to wait for a cleaner entry point once the valuation case is clear?
Preferred P/E of 34.7x: Is it justified for Port of Tauranga?
On the current numbers, Port of Tauranga trades on a P/E of 34.7x, which is well above several benchmarks and sets the tone for how investors are pricing its future.
The P/E ratio compares the share price with earnings per share. For a port operator like Port of Tauranga, it is a quick way to see how much investors are willing to pay today for each dollar of profit, given its established assets, earnings profile and role in New Zealand freight flows.
Against that backdrop, the present valuation looks demanding. The SWS analysis flags Port of Tauranga as expensive relative to its own estimated fair P/E of 26.6x, which is a level the market could move towards if expectations cool. The stock is also described as expensive against New Zealand peers at 26.3x and even more so versus the global infrastructure average at 14.5x. This gap signals that investors are paying a clear premium for this operator.
Explore the SWS fair ratio for Port of Tauranga.
Result: Price-to-earnings of 34.7x (OVERVALUED)
Still, Port of Tauranga’s story can change quickly if appeal challenges slow the Stella Passage project, or if weaker freight volumes pressure earnings at a premium P/E.
Find out about the key risks to this Port of Tauranga narrative.
Another View on Port of Tauranga’s Value
The P/E premium tells one story, but the SWS DCF model points in the same direction. On that framework, Port of Tauranga at NZ$7.95 sits above an estimated future cash flow value of NZ$6.01, which implies limited cushion if sentiment or freight volumes soften.
Investors who want to see how sensitive that conclusion is to different growth and discount rate assumptions can go deeper with the Look into how the SWS DCF model arrives at its fair value.
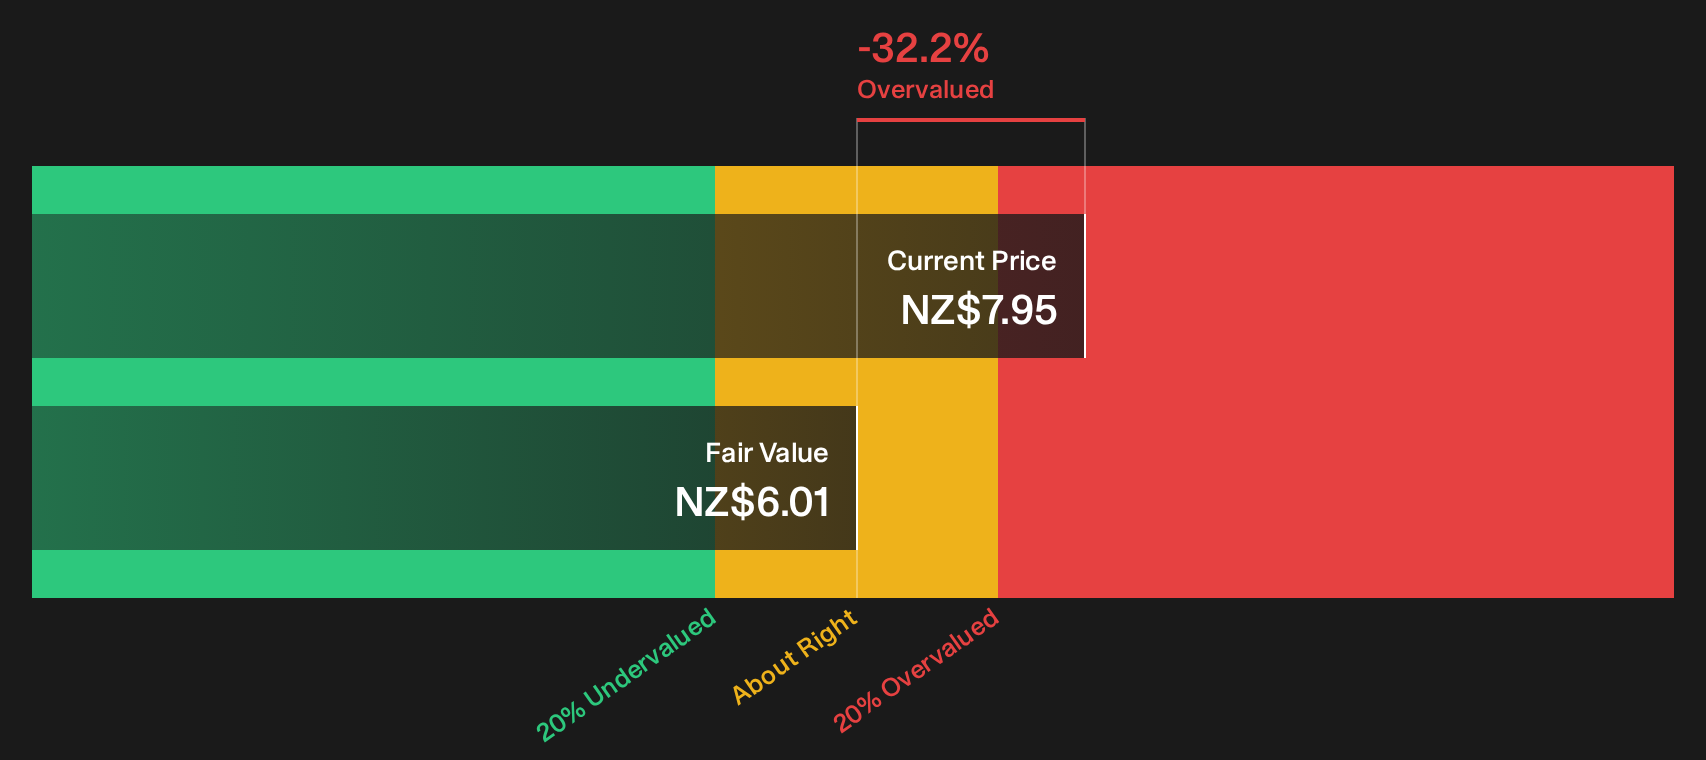
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Port of Tauranga for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 188 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Port of Tauranga is mixed, which is exactly when your own homework matters most. Move quickly to review the upside case in the 1 key reward
Looking for more Port of Tauranga investment ideas?
Port of Tauranga may already be on your radar, but limiting yourself to a single opportunity can leave better risk and reward trade offs off the table.
- Target quality at a discount by scanning a curated 188 high quality undervalued stocks that blend stronger fundamentals with more appealing entry prices.
- Strengthen your income stream by reviewing a focused 162 dividend fortresses built around higher yields and resilient payout histories.
- Dial down portfolio stress by working through a hand picked 103 resilient stocks with low risk scores designed to prioritise financial resilience and steadier returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com