
Exploring Three Undiscovered Gems in Asia with Promising Potential
As geopolitical tensions and rising oil prices weigh on global markets, Asian equities have shown resilience, with certain small-cap stocks presenting intriguing opportunities amidst broader economic fluctuations. In this dynamic landscape, identifying promising stocks involves assessing companies that demonstrate strong fundamentals and adaptability to shifting market conditions.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Kyosan Electric Manufacturing | 46.17% | 7.20% | 17.51% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
Kitazato (TSE:368A)
Simply Wall St Value Rating: ★★★★★★
Overview: Kitazato Corporation specializes in the research, development, manufacturing, and marketing of medical devices and reagents for fertility treatment, with a market capitalization of ¥57.20 billion.
Operations: The primary revenue stream for Kitazato comes from its Medical Equipment Business, generating ¥11.53 billion.
Kitazato, a nimble player in the medical equipment sector, boasts high-quality earnings and trades at 41.2% below its estimated fair value. Over the past year, its earnings surged by 12%, outpacing the industry growth of 4%. Debt-free for five years, this company is well-positioned financially with no interest payment concerns. Recent strategic moves include a joint venture in India to enhance market presence and customer support, indicating potential future growth. For fiscal year ending March 2027, Kitazato forecasts net sales of ¥11.35 billion and operating profit of ¥6.12 billion with stable dividends at ¥41 per share.
- Click to explore a detailed breakdown of our findings in Kitazato's health report.
Evaluate Kitazato's historical performance by accessing our past performance report.

Akatsuki (TSE:3932)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Akatsuki Inc. operates in the entertainment, lifestyle, and solutions sectors in Japan and has a market capitalization of approximately ¥43.20 billion.
Operations: Akatsuki Inc. generates revenue primarily from its entertainment, lifestyle, and solutions sectors in Japan. The company has a market capitalization of approximately ¥43.20 billion.
Akatsuki, a dynamic player in the entertainment industry, has shown impressive earnings growth of 914% over the past year, outpacing its peers significantly. The company's debt to equity ratio has risen from 15 to 90 over five years, suggesting increased leverage. However, Akatsuki trades at a substantial discount of 66% below its estimated fair value. Recent board meetings have focused on strategic changes like amending articles and considering a stock split effective October 2026. This aligns with their innovative ventures such as new game character releases that enhance user engagement and potentially drive future revenue streams.
- Unlock comprehensive insights into our analysis of Akatsuki stock in this health report.
Examine Akatsuki's past performance report to understand how it has performed in the past.
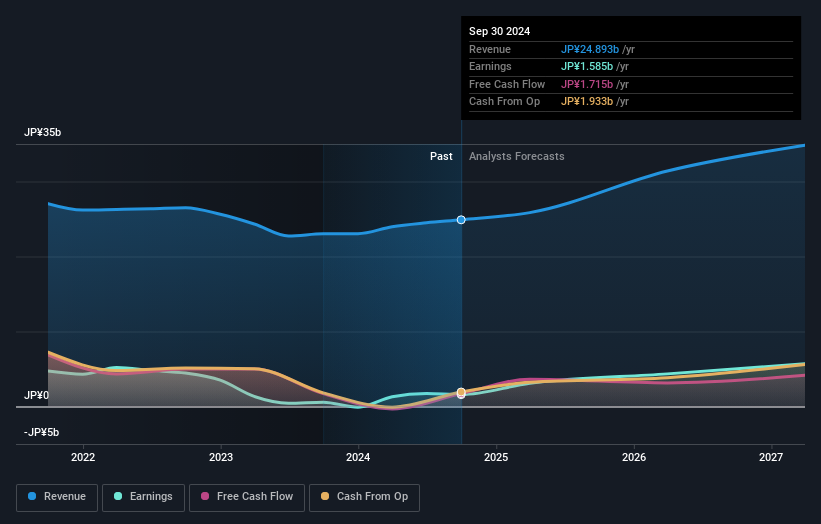
Tachibana Eletech (TSE:8159)
Simply Wall St Value Rating: ★★★★★☆
Overview: Tachibana Eletech Co., Ltd. operates as a technology-driven trading company in Japan and internationally, with a market cap of ¥88.46 billion.
Operations: Tachibana Eletech generates revenue primarily through its technology-driven trading operations. The company's cost structure includes procurement and operational expenses, which impact its profitability. Notably, the gross profit margin is a key metric reflecting its financial health and efficiency.
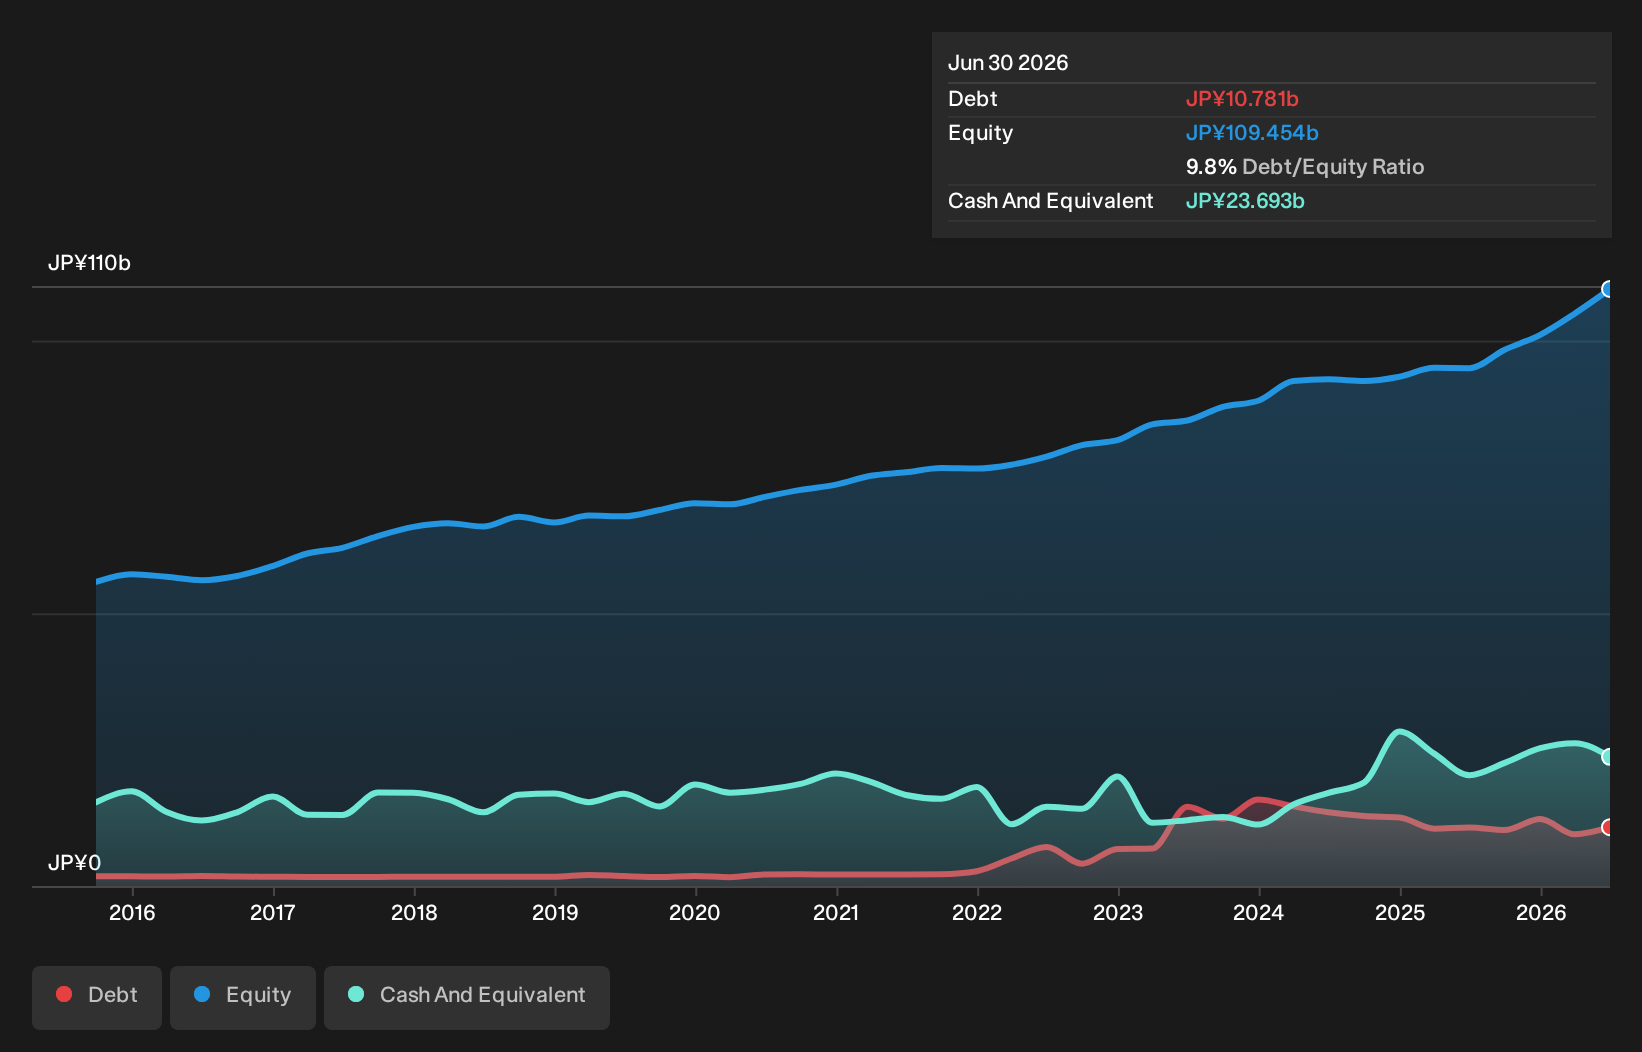
Tachibana Eletech, a nimble player in the electronics sector, has shown remarkable earnings growth of 33.9% over the past year, outpacing its industry peers. The company is trading at a notable 30.1% below its estimated fair value, indicating potential undervaluation. Despite an increase in its debt to equity ratio from 2.8% to 9.8% over five years, it holds more cash than total debt, reflecting sound financial health. Recent earnings reports reveal a significant rise in net income to JPY 1,899 million from JPY 722 million last year and improved basic earnings per share of JPY 86 compared to JPY 32 previously.
- Delve into the full analysis health report here for a deeper understanding of Tachibana Eletech.
Explore historical data to track Tachibana Eletech's performance over time in our Past section.
Where To Now?
- Take a closer look at our Asian Undiscovered Gems With Strong Fundamentals list of 118 companies by clicking here.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com