
Does Activist Push Change The Bull Case For Nichirei Stock (TSE:2871)?
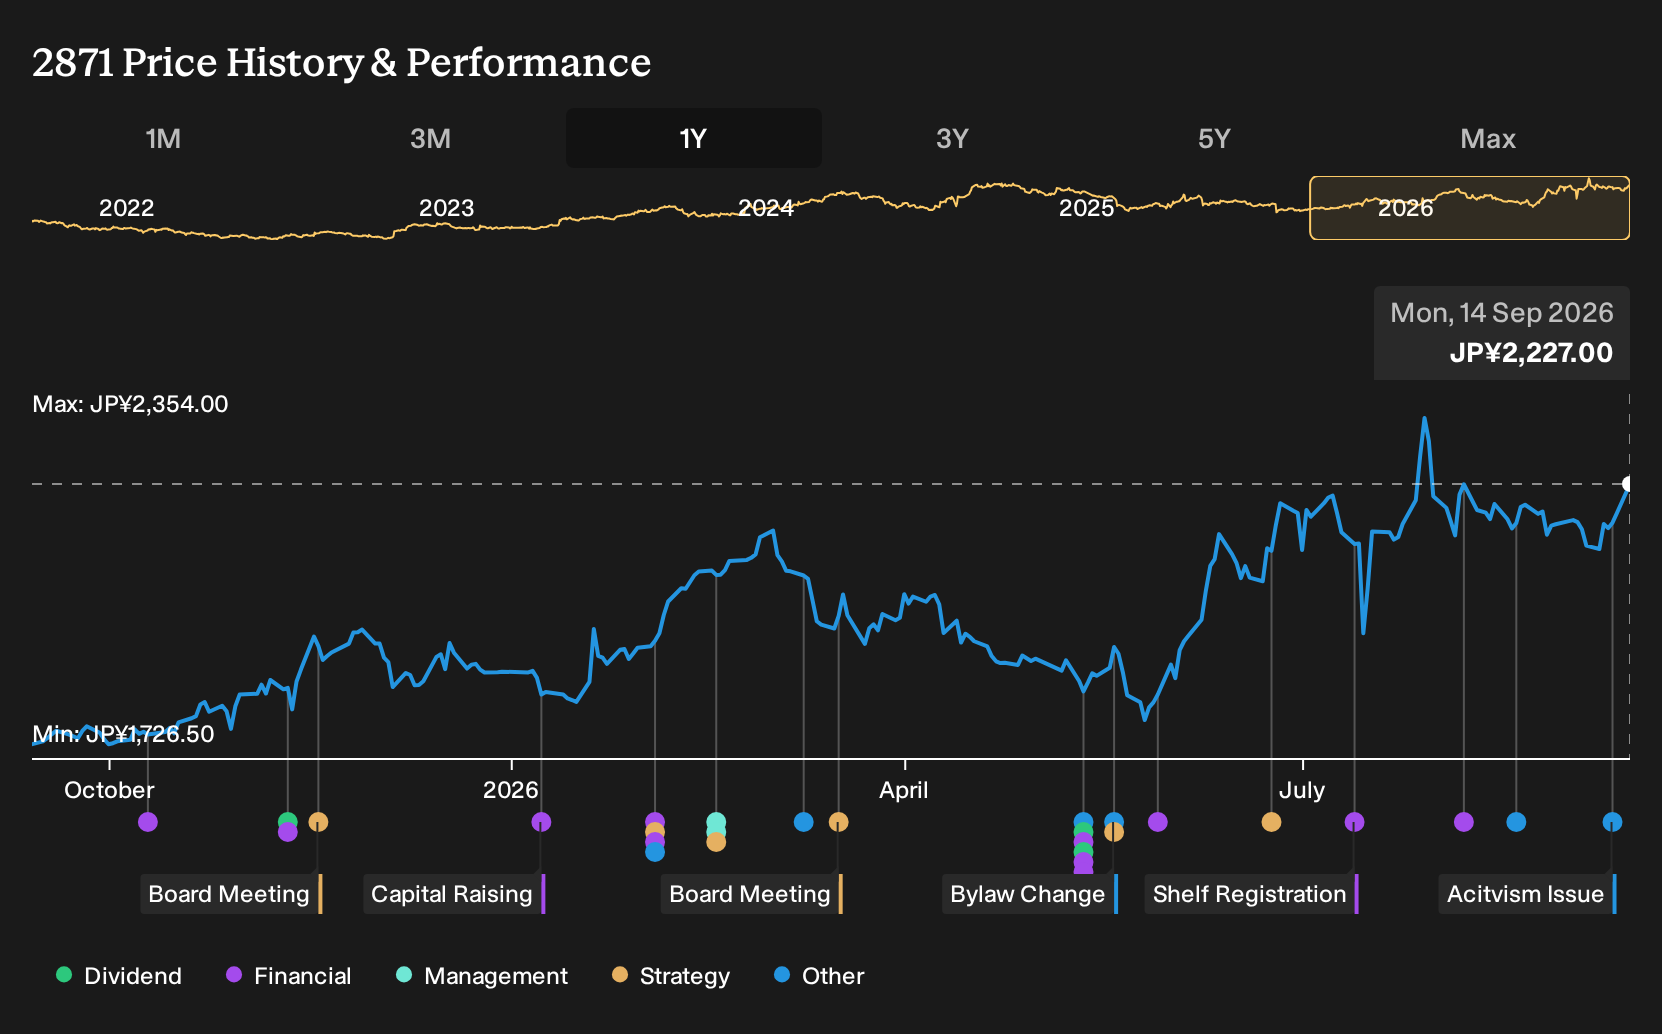
- Oasis Management Company disclosed that it has engaged Nichirei’s leadership with proposals on asset moves, borrowings, officer composition, business scope, and capital and dividend policies, and has also signaled that it may raise its shareholding.
- The wide reach of Oasis’s agenda, from asset allocation to board structure, puts Nichirei’s capital efficiency, risk profile, and long term payout priorities under sharper scrutiny.
- The focus now shifts to how Nichirei’s investment narrative could change if Oasis’s push on capital and dividend policy gains traction.
Scan how other investor-targeted stocks balance capital discipline with shareholder payouts by reviewing the hand picked 18 dividend fortresses in light of Nichirei’s Oasis-driven shake up.
What Is Nichirei's Investment Narrative?
To own Nichirei, you need to be comfortable with a fairly steady, capital intensive food and logistics operation where execution in frozen foods and temperature controlled storage matters more than headline excitement. The business already shows growing earnings and better net profit margins at 3.7% versus 3.4% last year, which hints at improving discipline around pricing and cost. In the short term, the key drivers are day to day demand for processed foods and the utilisation of its low temperature logistics network, rather than any single event.
Oasis entering the picture puts a different kind of pressure on Nichirei. The activist focus on asset use, leverage, officer changes, and dividend and capital policies goes straight to how aggressively management allocates cash. If those conversations gain traction, return on equity and payout consistency move closer to the front line of the story, which matters given the current low 9.7% ROE and an unstable dividend record.
Even so, there is one structural issue around how Nichirei funds itself that could easily be glossed over until you look at ...
There's only one way to know the right time to buy, sell or hold Nichirei. Head to Simply Wall St's company report for the latest analysis of Nichirei's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nichirei research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nichirei. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nichirei's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nichirei?
If Nichirei’s situation has sharpened your focus on capital allocation, income, and resilience, it can help to compare it with other businesses facing very different pressures. The Simply Wall St Screener lets you scan the market using consistent data, so you can line up opportunities next to each other and decide which trade offs fit your own plan.
- For investors who want income streams that look more robust, review a curated range of companies with steady payout profiles through the 18 dividend fortresses.
- If value is your priority and you want stocks that combine quality fundamentals with what may be undemanding prices, filter the market using the 17 high quality undervalued stocks.
- When capital protection comes first and you want balance sheets that look more resilient, start with the 12 resilient stocks with low risk scores to narrow the field.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com