
NXP Stock Faces A Physical AI Push Has The Bull Case Changed?
- NXP Semiconductors recently outlined its push into physical AI, combining security, safety, real-time processing and reliability for edge systems in vehicles, factories and infrastructure, while also highlighting expectations for higher data-center revenue and a shift toward a more asset-light manufacturing model.
- An interesting angle is how NXP Semiconductors is tying physical AI capabilities directly to software-defined vehicles, autonomy-related radar, electrification and connectivity, which now account for nearly half of its automotive revenue mix.
- We will now examine how NXP Semiconductors' physical AI push for software-defined vehicles could reshape the existing investment narrative around the stock.
Scan beyond NXP Semiconductors and line up other physical AI and intelligent-edge contenders with our handpicked 60 AI infrastructure stocks for context on where capital is flowing next in this theme.
NXP Semiconductors Investment Narrative Recap
NXP Semiconductors appeals to shareholders who buy into a long runway for physical AI in cars, factories and connected infrastructure, supported by secure, real time chips at the edge. The near term swing factor still looks like how quickly automotive and industrial customers move from inventory clean up to steadier ordering, since recent revenue trends show only modest recovery.
The biggest operational risk is that weak end demand or tough pricing, especially in China, meets a higher cost base from acquisitions and internal inventory, which could pressure margins. The latest physical AI update does not fundamentally change that near term risk reward balance, but it does sharpen where management is placing its bets.
The fresh messaging around physical AI and software defined vehicles sits alongside earlier moves such as acquiring TTTech Auto, Kinara and Aviva Links. Those deals loaded NXP Semiconductors with more expenses before meaningful revenue contributions, so execution on integration and product roadmaps now matters even more as the firm leans into intelligent edge use cases.
For you as an investor, the tie between these assets and core catalysts is clear. If software defined vehicles, radar heavy ADAS and industrial edge AI move from design wins to higher volume shipments as customer inventories normalize, the acquired capabilities could support that transition. If end markets stall or China pricing undercuts returns, the extra cost from these bets simply adds strain.
NXP Semiconductors' current analyst narrative points to revenues of US$17.1b and earnings of US$4.5b by 2029, based on projected revenue growth of 10.7% per year and an earnings increase of US$1.8b from US$2.7b today.
Uncover why NXP Semiconductors' fair value indicates a 40% potential upside to its current price, which could narrow quickly.
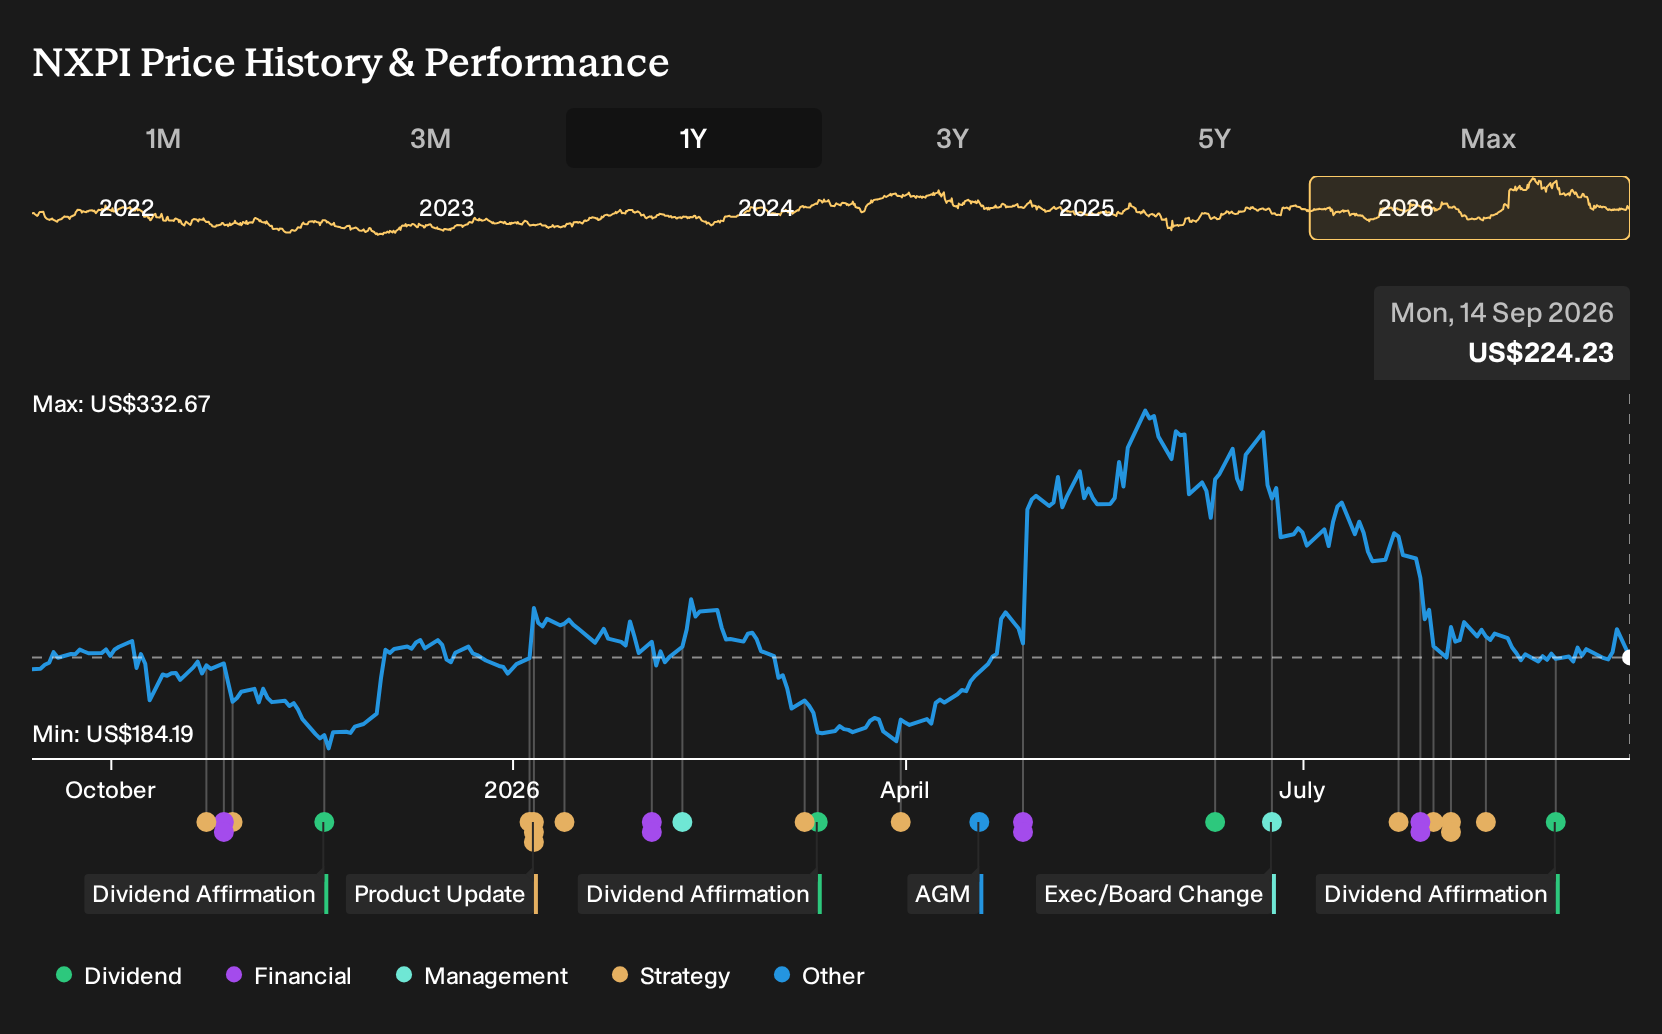
Exploring Other Perspectives
Some of the most optimistic analysts focus on NXP Semiconductors' physical AI acquisitions as a possible accelerator. They were already modeling revenue of about US$19.0b and earnings near US$5.3b by 2029, well above consensus. You can see how this new physical AI push might either reinforce those upbeat views even further or force a rethink.
Explore 5 other NXP Semiconductors fair value estimates, including one that suggests the potential for as much as 72% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NXP Semiconductors research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NXP Semiconductors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NXP Semiconductors' overall financial health at a glance.
Looking For More Investment Ideas Beyond NXP Semiconductors?
If this physical AI story around NXP Semiconductors has sharpened your thinking, it can help to compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan through our 35 high quality undervalued stocks that share strong cash flows and solid balance sheets.
- If capital preservation sits higher on your priority list, weigh NXP Semiconductors against a 11 resilient stocks with low risk scores that aim to keep drawdowns in check.
- If reliable income matters to your plan, line up NXP Semiconductors next to a 6 dividend fortresses that focus on higher-yield payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com