
Patrick Industries (PATK) Stock Looks Fairly Valued Despite A 54% Five Year Return
Patrick Industries has seen a sharp pullback in its share price this year, which naturally puts the focus on whether the current valuation lines up with what the business is earning. With the stock now trading at US$72.98, the key issue is how well that price reflects the earnings power investors are paying for.
- Over the past 5 years, Patrick Industries has delivered a total return of 54.3%, which makes the current setback an important test of how durable its earnings story really is.
- The company’s earnings profile depends heavily on how effectively it converts revenue into cash and manages its capital needs, which can shape how much of today's share price is supported by ongoing profit generation rather than hope for future gains.
- There is a second opinion on Patrick Industries worth weighing. See what analysts think Patrick Industries's shares could be worth.
The issue now is whether Patrick Industries’ current share price is adequately explained by its earnings when set against the Fair Ratio benchmark.
If you are weighing Patrick Industries against other opportunities where earnings carry more of the load than story, a focused screen of 35 high quality undervalued stocks.
Where Does Patrick Industries Sit on Earnings?
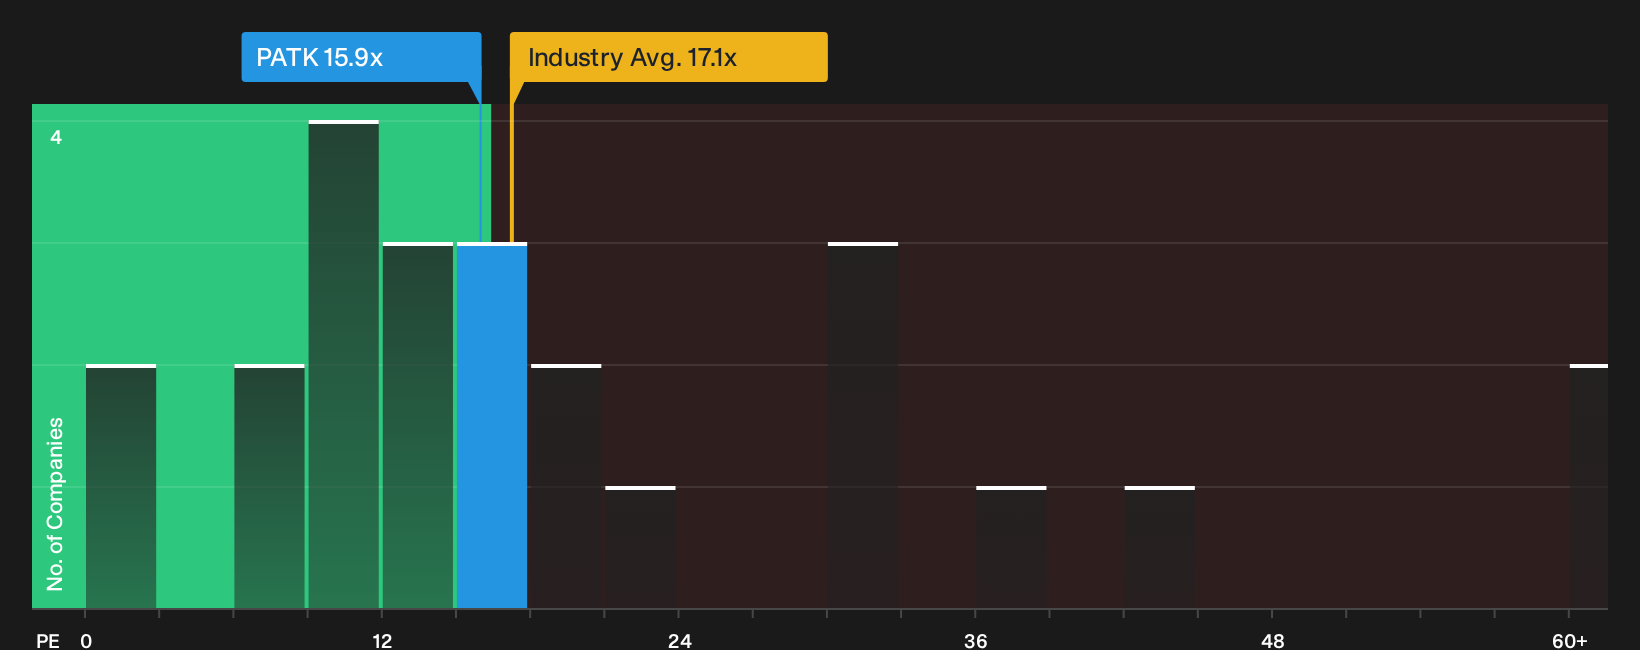
The P/E ratio is a useful fit for Patrick Industries because it links what you pay today with the earnings already on the table. At the current mark, the stock trades on a P/E of 15.9x, which is modestly above the Auto Components peer average of 13.1x yet a touch below the broader industry on 17.1x. That mix suggests investors are paying a slight premium to similar businesses while still not stretching to the higher multiples seen across the wider group.
The Fair Ratio model, which blends Patrick Industries’ growth profile, profitability, size and risk into a tailored benchmark, places the present 15.9x very close to where you might expect it to trade. So the P/E points to a valuation that is neither aggressively cheap nor clearly expensive, and it leaves the share price story hinging more on whether you are comfortable with the quality and durability of those earnings. Explore the numbers behind Patrick Industries's P/E valuation.
The Patrick Industries Narrative: What Would Justify Today's Price?
Patrick Industries' valuation debate only really comes into focus once you spell out the specific future paths that could make today’s price look conservative or demanding. Narratives on Simply Wall St’s Community page do exactly that for Patrick Industries by tying scenarios for growth, margins and earnings to concrete valuation outcomes. Each one sets up fair value as a thesis about the business that you can revisit over time as new information arrives.
One of the top community narratives on Patrick Industries: 44% undervalued
"The LCI Industries combination is cited as strengthening Patrick Industries’ platform, which some analysts view as supportive of the company’s long-term earnings potential…"
Discover why this Narrative puts Patrick Industries at 44% undervalued.
One More Piece Of The Patrick Industries Story To Check
Before treating Patrick Industries' current valuation as the whole picture, it helps to know that our research checks have flagged specific areas of concern that deserve a closer look. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com