
T. Rowe Price (TROW) Stock Could Be Reasonable Following Its 35% Fall
T. Rowe Price Group has had a mixed share price record over the past few years, which puts fresh focus on whether the business is earning strong enough returns on its capital to back up where the stock trades today. With new AI partnerships and product launches now in the mix, investors are asking if those returns can justify the current valuation.
- Over the past 5 years the stock has fallen 35.5%, which puts sharper attention on whether the returns the company earns on its capital can support a recovery from here.
- Recent investments in AI driven research with Anthropic and allocations to high growth private companies like Temporal and Cognition AI may support expectations for improved capital efficiency if those efforts help T. Rowe Price generate better insights or higher fee opportunities over time.
- Prefer to judge T. Rowe Price Group on earnings? See what T. Rowe Price Group's 10.4x P/E says about the price.
The issue now is whether the returns T. Rowe Price Group earns on its capital are strong and resilient enough for investors to view the current share price as sensible.
If you are weighing T. Rowe Price Group against other ways to put capital to work in AI related finance, a focused stock screen built around 60 AI infrastructure stocks.
Is T. Rowe Price Group Still Cheap on Excess Returns?
The Excess Returns model looks at how much profit T. Rowe Price Group can earn above its cost of equity over time. On this view, the firm is treated as a steady return generator rather than a high growth story, which fits a mature asset manager with a long operating history. The model uses a Book Value of $51.58 per share and a Stable Book Value of $52.85 per share, paired with Stable EPS of $9.96 per share and a Cost of Equity of $4.16 per share.
That spread, an Excess Return of $5.80 per share supported by an average Return on Equity of 18.85%, implies the business is expected to earn more on its equity base than investors require. That gap is material when set against the current share price of $105.80. Because the expanded use of Claude with Anthropic is aimed at sharpening research and workflows, the market price may not yet fully reflect the value the Excess Returns model assigns to those projected profits. Find out what T. Rowe Price Group could be worth using our Excess Returns estimate.
The T. Rowe Price Group Narrative: What Would Justify Today's Price?
Narratives pick up where the Excess Returns model leaves off for T. Rowe Price Group, by spelling out which paths for revenue growth, profit margins and earnings would need to play out for the shares to trade meaningfully above or below today's level. They sit on Simply Wall St's Community page. Rather than relying on a single multiple or point estimate, each Narrative lays out the assumptions behind its view of fair value so you can compare them with actual results over time.
Community views on T. Rowe Price Group are split between those who see expense control and new products supporting the story and those who worry that fee pressure and outflows keep the multiple under strain.
Bull case: roughly fairly valued
"Ongoing investment in technology, digital platforms, and artificial intelligence is expected to increase operational efficiency and client customization at scale…"
Discover why this Narrative puts T. Rowe Price Group at roughly fairly valued.
Bear case: 17% overvalued
"T. Rowe Price Group is experiencing significant fee compression with a higher-than-average rate of 2% in 2024, due to a mix shift in sales toward lower-fee vehicles such as ETFs and institutional accounts…"
Explore why this Narrative puts T. Rowe Price Group at 17% overvalued.
One unresolved question for T. Rowe Price Group
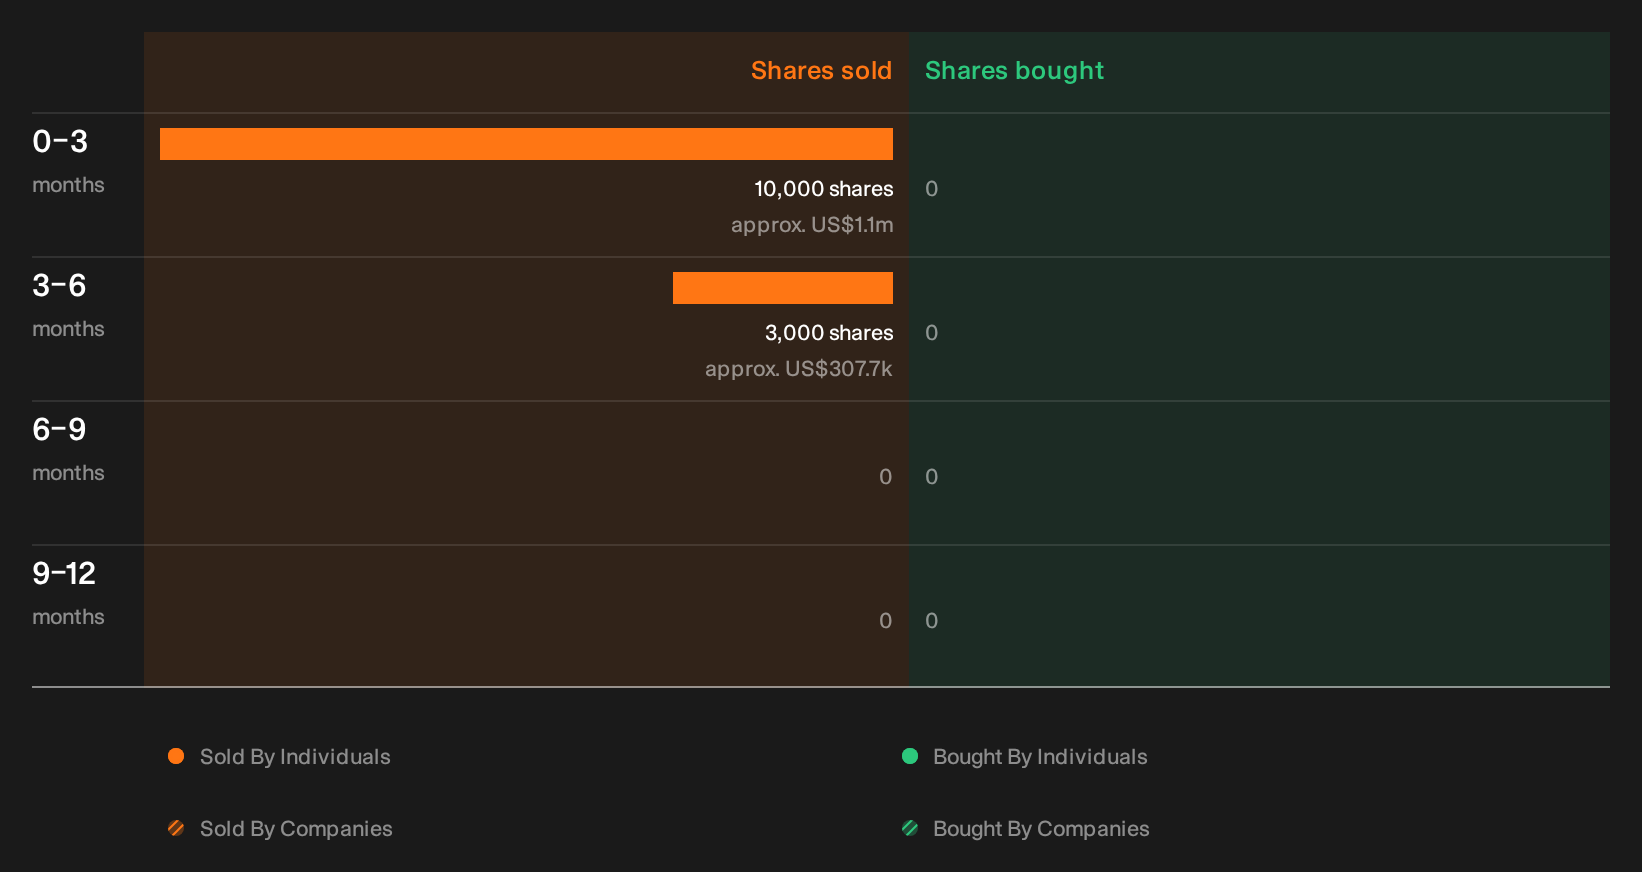
There is one more angle that matters for anyone tracking T. Rowe Price Group, the recent share dealing activity by its own leaders, and our checks have already flagged fresh selling for you to review. See the recent insider selling flagged for T. Rowe Price Group.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com