
3 AI Infrastructure Stocks Facing New Trade Compliance Pressure
Global trade rules are getting more complex, while AI tools are moving from experiment to everyday plumbing for regulated workloads. That mix is creating fresh pressure on infrastructure providers that can support compliance heavy AI deployments inside data centers, at the edge, and in hosted environments. This article walks through three stocks from our AI Infrastructure for Regulated Enterprise Workloads screener that appear particularly exposed to these trade compliance shifts, and explains why that may matter for portfolio construction.
The three stocks covered below are only a small sample, since the full screen surfaced 67 more hardware and infrastructure providers with equally compelling AI and compliance stories that do not fit into this article.
To size up that broader universe, head straight into the AI Infrastructure for Regulated Enterprise Workloads screener so you can identify, filter, and analyze the highest conviction AI infrastructure candidates for regulated workloads.
Insight Enterprises (NSIT)
Overview: Insight Enterprises designs, integrates, and manages secure IT hardware, software, and services, building compliant data-center and on-premise infrastructure for global enterprises.
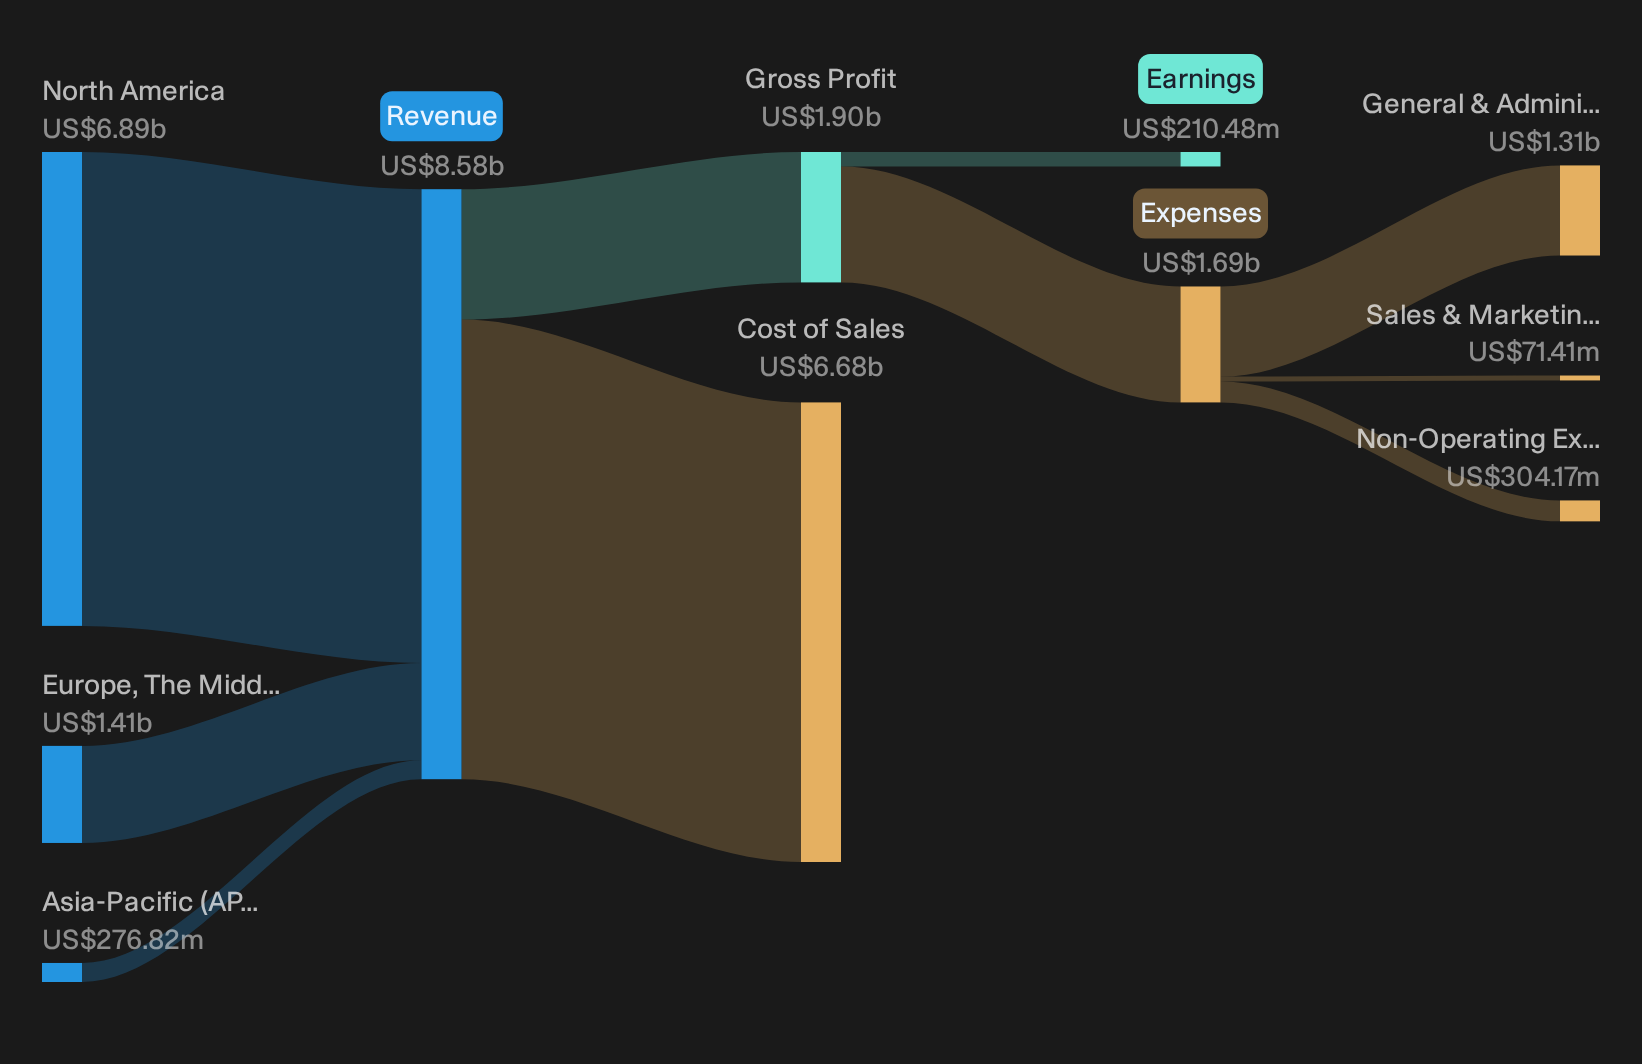
Operations: Insight generates most revenue in North America at about US$6.9b, with EMEA at roughly US$1.4b and APAC near US$277 million.
Market Cap: US$4.7b
Insight Enterprises matters for this screener because it sits close to where regulated clients actually buy and operate AI ready infrastructure, from data centers to edge deployments.
"The rapid adoption of artificial intelligence and the increasing urgency for enterprises to modernize IT infrastructures, particularly to support AI workloads, could drive significant multi-year hardware and services demand. This could directly benefit Insight's revenue and position the company for an upward earnings re-rating as macro uncertainties subside."
What happens to Insight Enterprises' margin story if a single key assumption about AI driven services mix or hardware price pressure breaks.
If that margin puzzle matters to you, read the full narrative for Insight Enterprises to see how Insight Enterprises could balance AI demand, pricing pressure, and service mix inflection.
Belden (BDC)
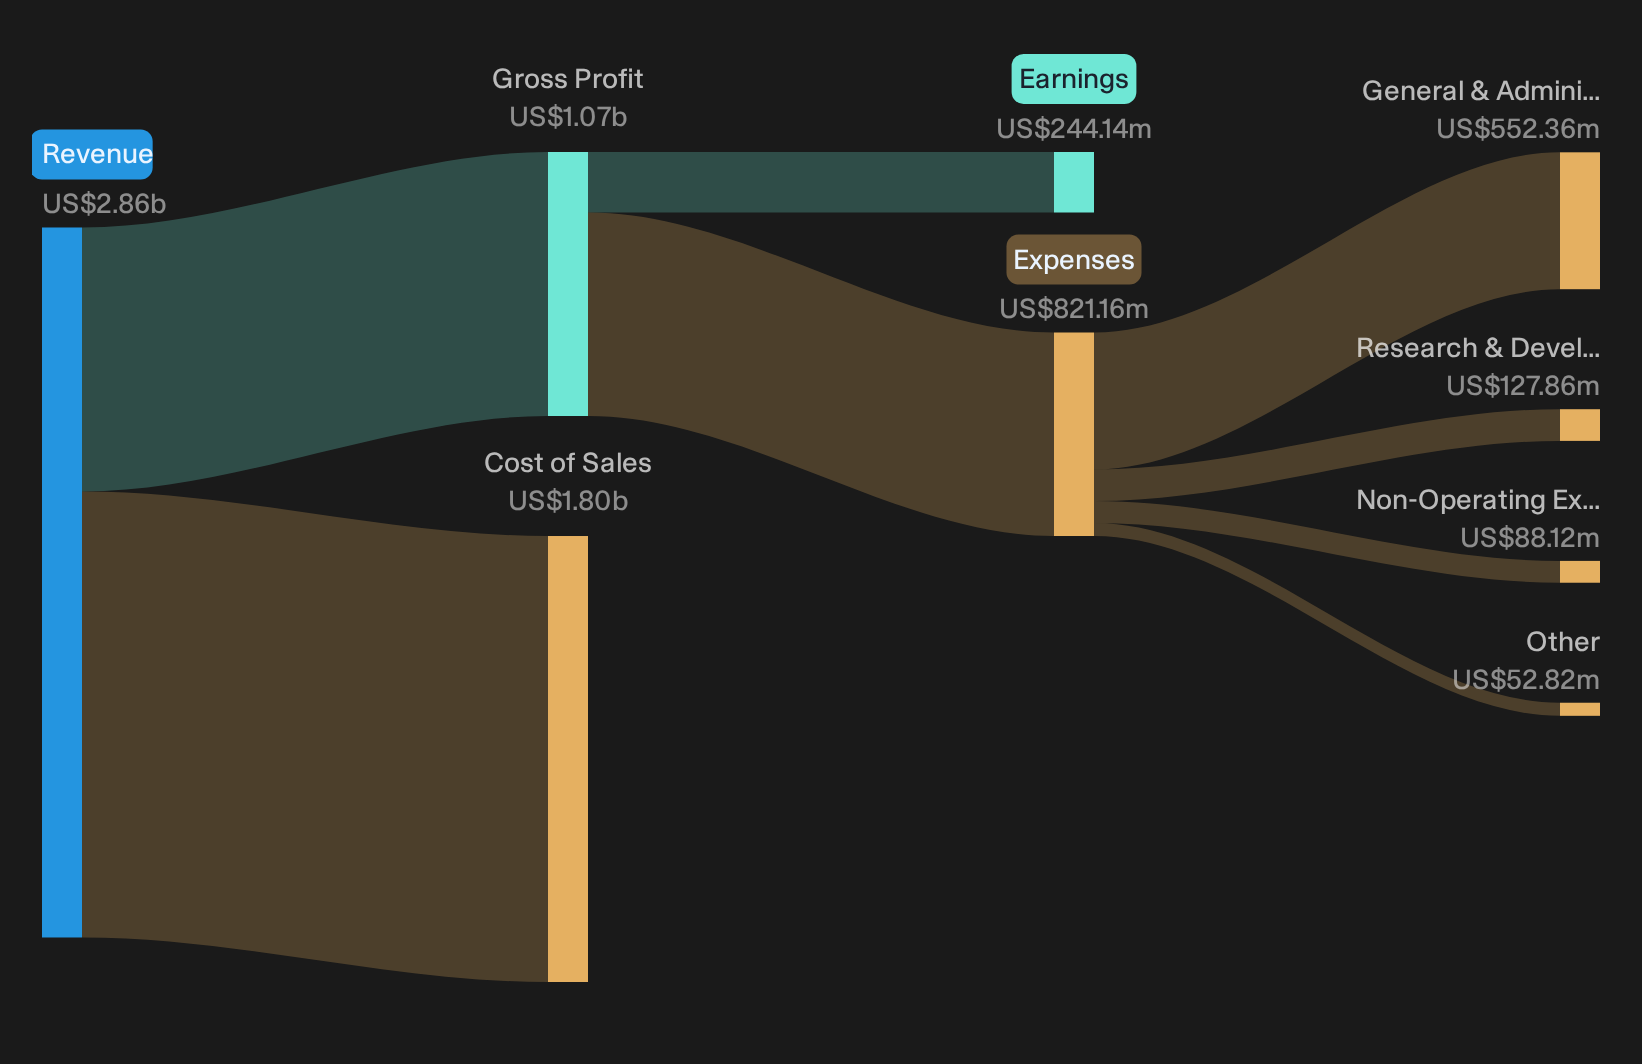
Overview: Belden supplies copper and fiber connectivity, power, cooling and networking gear that underpins industrial and enterprise data centers running regulated AI workloads.
Market Cap: US$4.8b
Belden matters in this AI Infrastructure for Regulated Enterprise Workloads screen because its gear sits inside the physical networks that carry sensitive data between machines, sensors and data centers where regulated AI models actually run.
"Belden is uniquely capitalizing on the integration of IT and OT, addressing customer needs to converge data, automate processes, and enable advanced use-cases in smart manufacturing and energy management; their expertise in this area expands the addressable market and enables higher-value, differentiated solutions, which should support above-market growth and margin expansion."
What happens to Belden’s margin and growth story if one unseen pressure on funding costs or leverage starts to bite harder than expected?
If that funding pressure is what you are watching, read the full narrative for Belden to see whether Belden’s capital structure risks are masking a stronger AI infrastructure story.
Credo Technology Group Holding (CRDO)
Overview: Credo Technology Group Holding supplies high-speed Ethernet and PCIe connectivity chips and cables that move data efficiently inside AI data centers.
Operations: Credo generates US$1.6b in semiconductor revenue, largely tied to connectivity components used across US and international data-center and networking customers.
Market Cap: US$30.6b
Credo Technology Group Holding plugs into this screener because its connectivity products help AI servers in regulated environments move huge datasets quickly without blowing out power and hardware budgets.
"The DustPhotonics acquisition gives Credo a weapon to fight in this longer-range, higher-bandwidth territory that was previously Marvell's exclusive domain."
What happens to Credo’s high-speed connectivity story if a single assumption about customer concentration or product mix resilience breaks?
That question on resilience is where the story really starts, and the full narrative for Credo Technology Group Holding shows how Credo Technology Group Holding could turn today’s concentration risks into accelerating opportunity.

Seeking Alternatives Before Momentum Flies
Fresh opportunities do not wait. Breakout themes gain momentum, prices move, and under the radar stories get caught by the crowd. Scan these curated ideas while it matters and consider your options promptly.
- Spot cash rich businesses before momentum traders notice by running the list of solid balance sheet and fundamentals (23 results) that filters for resilient balance sheets and consistent underlying fundamentals.
- Find dividend payers with yields that could support portfolio income by reviewing the curated 6 dividend fortresses before prices move and yields begin to change.
- Follow developments in automation demand by tracking the hand picked 38 robotics and automation stocks that focuses on businesses wiring factories and warehouses for efficiency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com