
Target (TGT) Names Mark Weinstein Chief Marketing And Guest Experience Officer
- Target (NYSE:TGT) has hired Mark Weinstein as Chief Marketing and Guest Experience Officer, joining from Hilton.
- Weinstein will oversee Target's brand marketing, guest experience, and the development of its retail media and marketplace operations.
- His remit includes creating a more connected experience for shoppers across Target's stores, digital platforms, and loyalty touchpoints.
- The appointment of Mark Weinstein to reshape marketing and guest experience comes alongside broader shifts our research has identified. We have also flagged 2 warning signs for Target.
This move by Target is one example of how large retailers are repositioning around experience and media, and several other stocks are exposed to the same theme through our screener containing 15 high quality undiscovered gems.
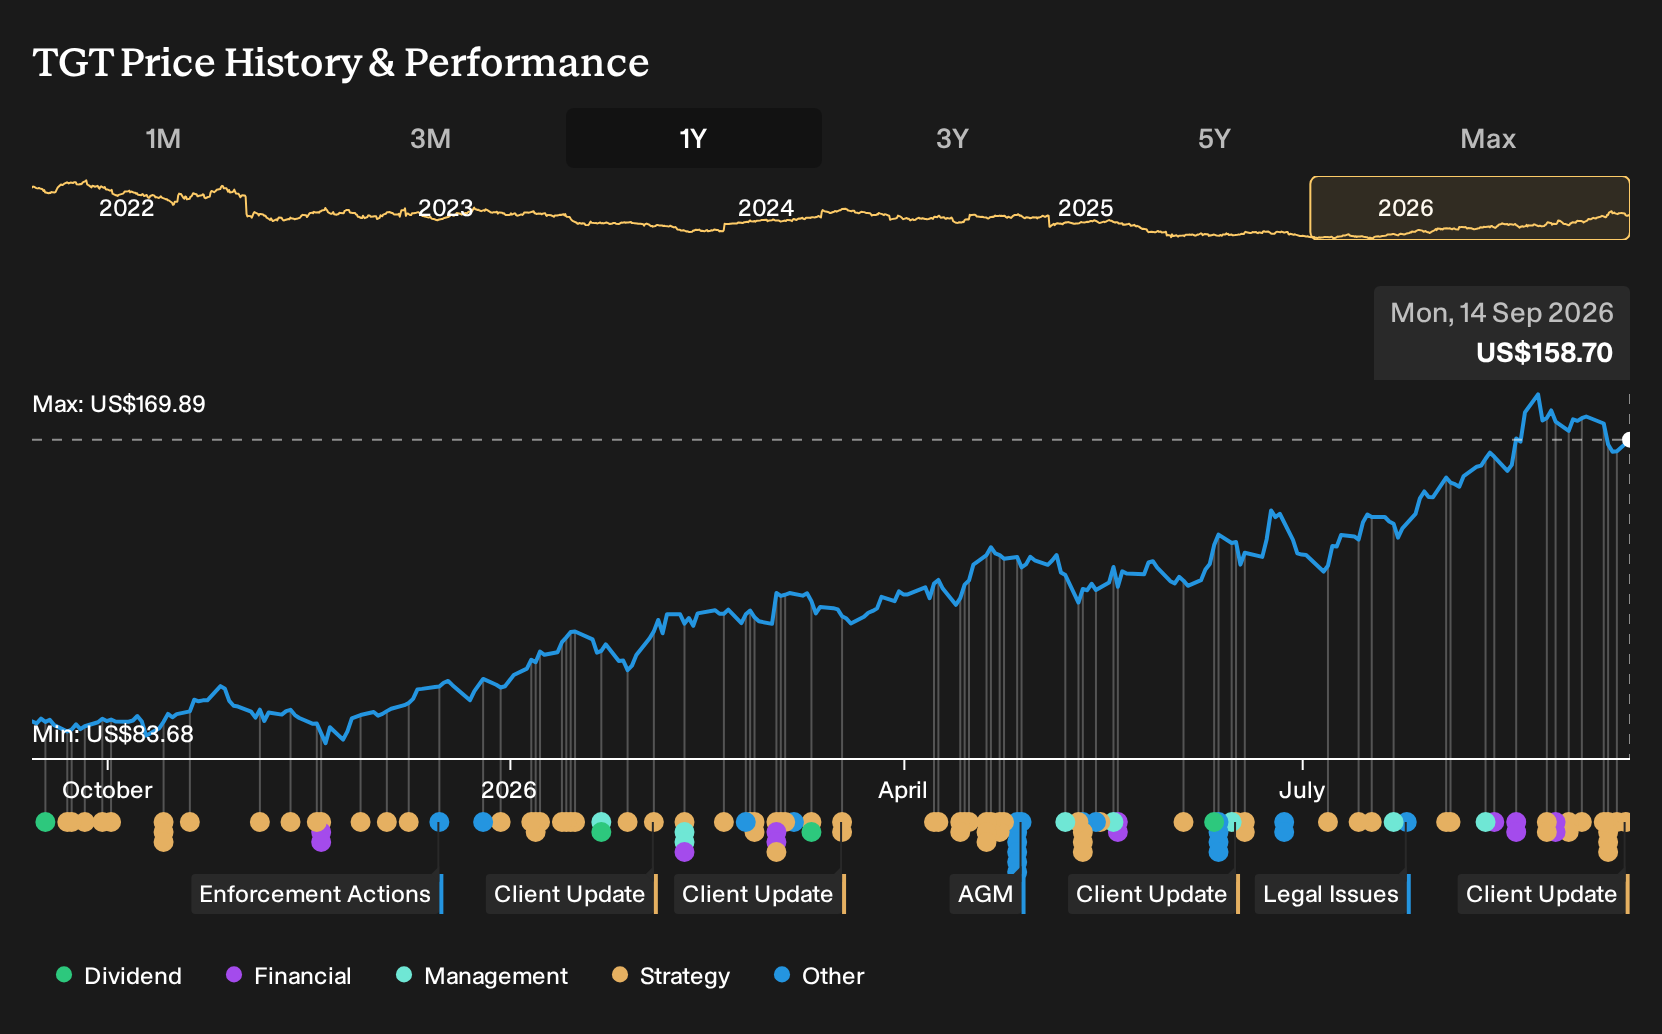
Target operates as a large US general merchandise retailer, so decisions in marketing and guest experience affect a wide range of categories from household essentials to discretionary goods. With a market cap of $70.8b, the company has the scale for Weinstein's retail media and marketplace brief to influence how brands and shoppers interact across its ecosystem.
Target leadership shake-up and the bet on experience-led growth
The Target Narrative hinges on whether reinvestment in technology, owned brands and omnichannel experiences can offset cost pressure and slower discretionary demand, and a new Chief Marketing and Guest Experience Officer goes straight into that debate. This leadership move ties Weinstein’s consumer marketing background to Target’s push on Roundel, Target+ and loyalty, which are central planks in the investment story.
"The growing and profitable first-party digital business, along with double-digit growth in Target's Roundel and Target Plus segments, suggest successful omnichannel integration and new high-margin revenue streams, countering concerns about declining in-store traffic and supporting earnings growth..."
See how the full story points towards a $134 fair value for Target.
This appointment clearly supports the Narrative catalyst that Roundel, Target+ and loyalty programs can become meaningful higher margin revenue streams. Putting one executive over marketing, guest experience and retail media makes the bet more explicit that Target can stitch together stores, digital channels and data in a way that rivals like Walmart and Amazon have been working on for years.
The same hire also puts pressure on the Narrative’s risk around slow adaptation to younger shoppers and fragmented digital experiences. If the marketing and experience engine still feels disjointed, or Roundel and Target+ fail to gain traction under a unified leader, then concerns about operational gaps, higher SG&A and e-commerce disintermediation that analysts have already flagged will look more pressing.
For anyone weighing Target as an investment, a consistent Narrative linking leadership moves like this to specific execution bets is what turns a management headline into a decision you can actually judge.
Add Target to your Watchlist and get alerts as these catalysts play out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com