
FormFactor (FORM) Stock May Be Fully Priced After Its 235% Run
FormFactor has seen a powerful run over the past year, which puts a spotlight on whether the current share price is sensibly aligned with what the business is earning today. With that kind of backdrop, the question is how much of the recent enthusiasm is actually supported by its profit engine.
- FormFactor has delivered a 235.1% return over the past year, which makes it important to ask how much of that move is grounded in the company’s earnings power rather than just momentum.
- The business is closely tied to semiconductor testing demand, so any shift in how effectively it converts that demand into profits can influence how investors judge what a fair earnings multiple looks like.
- There is a second opinion on FormFactor worth weighing. See what analysts think FormFactor's shares could be worth.
The issue now is whether FormFactor's current share price is properly supported by its earnings profile when compared against the Fair Ratio benchmark.
If you are weighing whether FormFactor's 235.1% one year surge feels justified by its earnings, it can help to compare it with a wider pool of 35 high quality undervalued stocks.
Has FormFactor Run Too Far on Earnings?
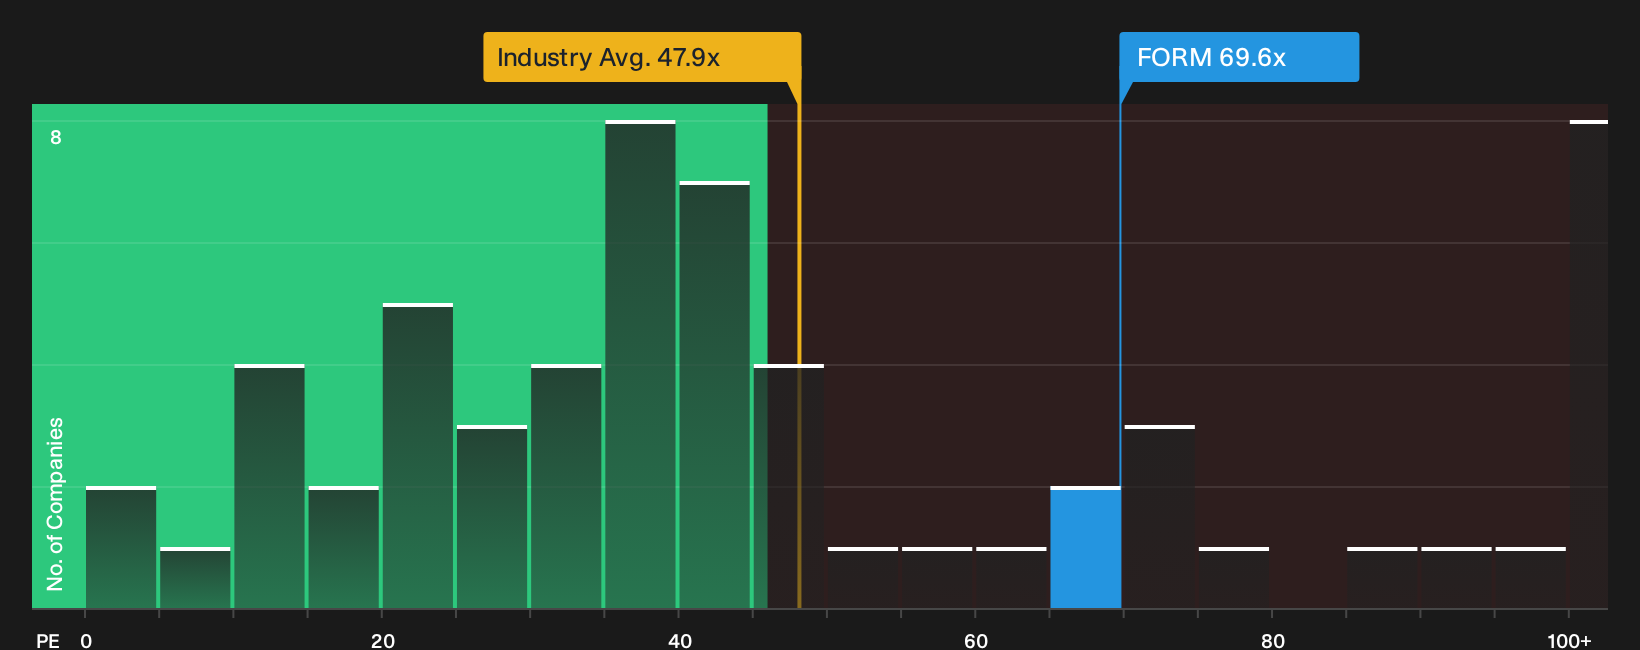
A P/E lens works well for FormFactor because earnings are a key yardstick for how the market prices specialist semiconductor suppliers. Right now, the stock trades on a P/E of 69.6x, which sits above the semiconductor industry average of 47.9x and still comes in below the peer group at 79.1x. That mix indicates that investors are already assigning a premium to the business versus the broader sector, even though it does not carry the highest tag in its immediate peer set.
The Fair Ratio framework, which lines up the P/E you might expect given FormFactor’s growth profile, profitability, size and risk, points to a lower earnings multiple than the market is currently paying. On this measure the stock screens overvalued, so anyone buying at today’s price is accepting a richer than modelled earnings tag and needs to be comfortable that the underlying economics justify it. Explore the numbers behind FormFactor's P/E valuation.
The FormFactor Narrative: What Would Justify Today's Price?
FormFactor's valuation puzzle sets up the role of Simply Wall St Narratives nicely. These sit on the Community page and spell out the specific growth, margin and earnings paths that would need to hold for the stock to be worth materially more or less than today’s price. Where a single ratio or model gives you one headline figure, Narratives unpack the future that figure relies on so you can watch how reality lines up over time.
Community views on FormFactor split between those who see AI driven upside and those who worry the current price already bakes in too much optimism.
Bull case: 26% undervalued
"Accelerating adoption of generative AI, high-performance computing, and HBM DRAM in data centers is driving substantial increases in test complexity and intensity..."
Discover why this Narrative puts FormFactor at 26% undervalued.
Bear case: 61% overvalued
"FormFactor faces the risk of prolonged gross margin and earnings pressure due to persistent adverse shifts in product mix, particularly the growing share of lower-margin DRAM..."
Explore why this Narrative puts FormFactor at 61% overvalued.
FormFactor’s price is visible, the people steering it are not
Valuation only tells you what the market pays today. The real story often sits with who runs FormFactor, how they are rewarded, and whether those incentives truly line up with your interests. See who runs FormFactor and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com