
Is MonotaRO (TSE:3064) Undervalued Following Its Strong August Sales Update?
Why August Sales Put MonotaRO Back on Investor Screens
MonotaRO (TSE:3064) has drawn fresh attention after reporting preliminary non-consolidated August 2026 sales of ¥26,985 million, compared with ¥22,620 million in the same month a year earlier.
This sales update comes alongside news that the company recently completed a ¥173.25 million share repurchase program covering 90,000 shares, a move that slightly reduces the share count and can matter for per share metrics over time.
Against that backdrop, MonotaRO’s recent August sales update and completed buyback arrive as the share price trades at ¥1,992.5, with a 90 day share price return of 14.51% but a year to date share price decline of 17.10%, hinting at momentum rebuilding after a tougher spell. Over a longer horizon the picture is mixed, with a 3 year total shareholder return of 29.12% contrasted with a 1 year total shareholder return decline of 12.79% and a 5 year total shareholder return decline of 18.38%. This suggests investors are reassessing both the company’s growth potential and its risks as fresh trading data comes through.
Spot similar momentum shifts by scanning our 17 high quality undervalued stocks, which combines growth records with balance sheets that investors can scrutinize side by side with MonotaRO.Bulls view MonotaRO’s August sales and recent buyback as signs that the recent share price recovery could continue. Bears highlight the weaker 1-year record. Which side do current valuation metrics appear to support?
Preferred P/E of 27.5x for MonotaRO: Is it justified?
Valuation for MonotaRO currently leans heavily on what investors are willing to pay for each yen of earnings, with the stock trading on a P/E of 27.5x at a share price of ¥1,992.5. Internal modelling flags the shares as trading at a 22.3% discount to an estimated fair value, and a separate DCF estimate of future cash flow value points to ¥2,564.1 per share.
The P/E multiple captures how much the market prices the company’s current profit stream relative to its bottom line. For a business like MonotaRO that runs an online MRO platform and reports high quality earnings, a richer multiple can sometimes reflect expectations around future profit expansion, the asset light nature of the operation, or confidence in the business model.
Evidence from the statements points both ways. Earnings grew by 21.7% over the past year and have risen by 16.3% per year over the past 5 years, with net profit margins at 9.7% compared with 9.5% a year earlier and Return on Equity currently at 29.1%, which is described as high. Forecasts also point to revenue growth of 10.5% per year and earnings growth of 11.16% per year, both ahead of the broader JP market figures provided. This helps explain why the SWS DCF model suggests a future cash flow value of ¥2,564.1 per share, above the latest close.
On the other hand, the same checks say that a P/E of 27.5x looks expensive when stacked against several benchmarks. The fair P/E ratio implied by regression analysis is 20.1x, so the current multiple is well above a level the market could move towards if sentiment cools. Relative to the JP Trade Distributors industry average of 10.6x and a peer group average of 11.3x, the valuation is described as rich by a wide margin, which suggests buyers are already paying up considerably compared with similar stocks.
Explore the SWS fair ratio for MonotaRO.
Result: Price-to-Earnings of 27.5x (OVERVALUED)
Still, any slip in MonotaRO’s earnings momentum, or a reset in market appetite for higher P/E stocks, could quickly challenge the current premium narrative.
Find out about the key risks to this MonotaRO narrative.
Another View on MonotaRO’s Value
The SWS DCF model paints a different picture. On that measure, MonotaRO at ¥1,992.5 is described as trading below an estimated future cash flow value of ¥2,564.1 per share, which frames the current quote as undervalued rather than expensive. Which signal do you trust more when earnings expectations change?
Look into how the SWS DCF model arrives at its fair value.
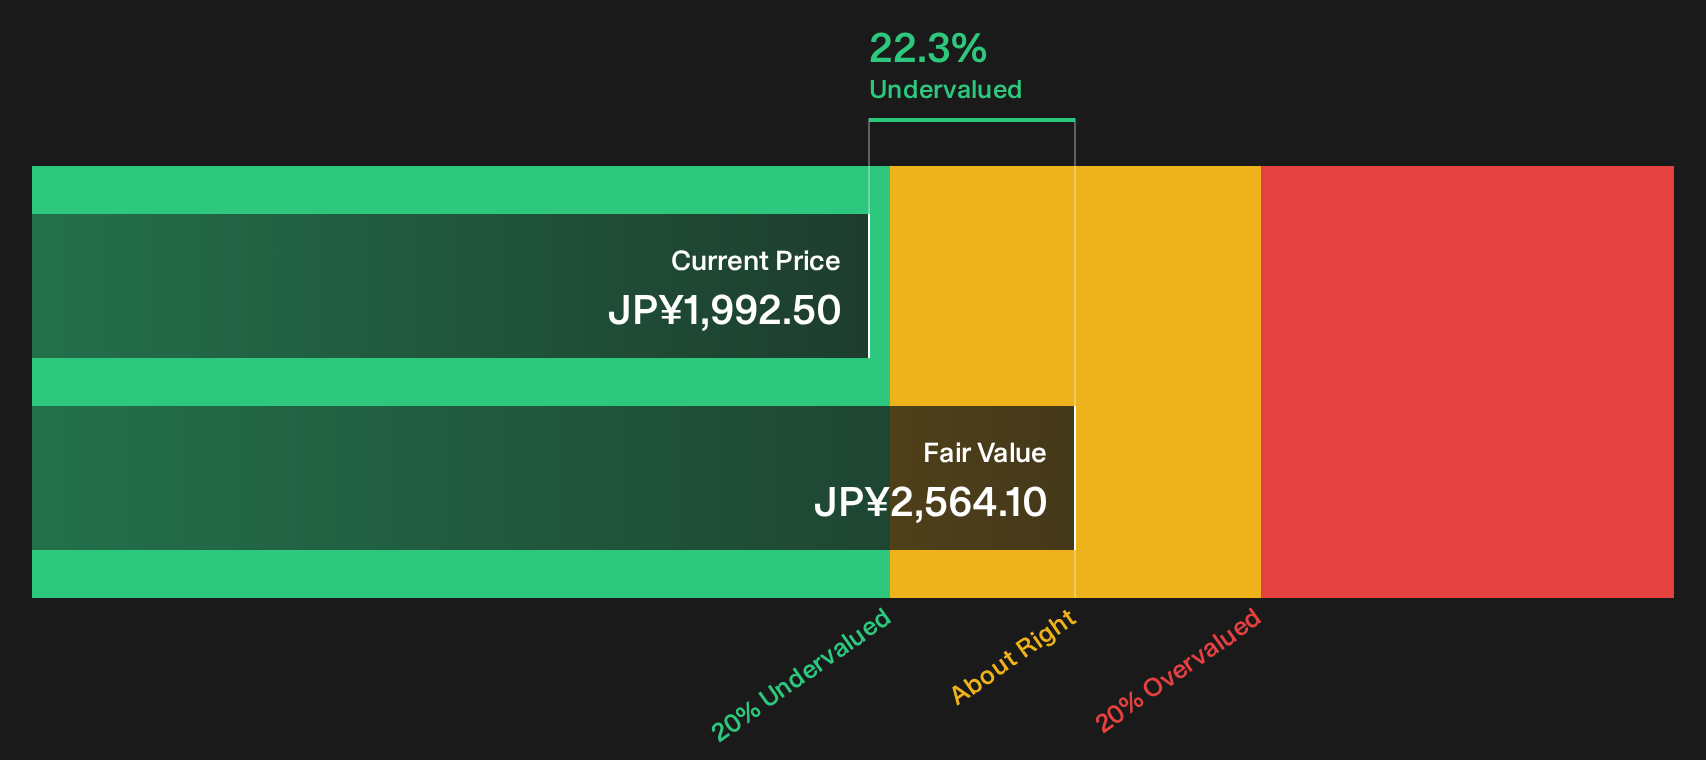
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MonotaRO for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
There are mixed signals regarding MonotaRO so far. If you want a clearer view before the next data point is released, consider both sides of the story and review the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond MonotaRO?
If MonotaRO has sharpened your interest, do not stop here. Fresh ideas often come from scanning wider, not staring longer at one ticker.
- Target resilient balance sheets by reviewing a list of solid balance sheet and fundamentals (19 results) that you can line up against MonotaRO's financial position.
- Seek potential mispricing by running through a 17 high quality undervalued stocks that highlights businesses where fundamentals and share prices appear out of sync.
- Hunt for future leaders early by checking a 74 high quality undiscovered gems before the rest of the market starts paying close attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com